Category: Medical Equipment

  • Understand How The Transcatheter Embolization And Occlusion Devices Market Is Poised To Grow Through 2024-2033

    Understand How The Transcatheter Embolization And Occlusion Devices Market Is Poised To Grow Through 2024-2033

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    As per The Business Research Company’s Transcatheter Embolization And Occlusion Devices Global Market Report 2024, the transcatheter embolization and occlusion devices market is expected to show significant growth in the forecast period.

    Rapid Market Expansion
    The transcatheter embolization and occlusion devices market has experienced significant growth recently. The market size, valued at $4.31 billion in 2023, is expected to rise to $4.76 billion in 2024, reflecting a compound annual growth rate (CAGR) of 10.4%. This increase is driven by several factors:

    • Expansion of the target patient population
    • Rise in minimally invasive vascular surgeries
    • Growing incidence of vascular and chronic diseases
    • Demand for effective treatment options

    Forecasted Market Growth
    Looking ahead, the market is projected to reach $7.13 billion by 2028, with a CAGR of 10.6%. This anticipated growth is attributed to:

    • Increased research and development activities
    • Expansion of the healthcare sector
    • Growing adoption of minimally invasive techniques
    • Rising older population
    • Increased workshops and awareness initiatives

    View More On The Transcatheter Embolization And Occlusion Devices Market Report 2024 – https://www.thebusinessresearchcompany.com/report/transcatheter-embolization-and-occlusion-devices-global-market-report

    Key trends influencing this period include:

    • Technological advancements
    • Improved imaging techniques
    • Integration of artificial intelligence and machine learning
    • Ongoing improvements in device design and delivery systems

    Minimally Invasive Surgery Driving Demand
    Minimally invasive surgical techniques are significantly propelling the growth of the transcatheter embolization and occlusion devices market. These techniques use small incisions or natural openings to minimize trauma, offering benefits such as:

    • Reduced invasiveness
    • Shorter recovery times
    • Localized treatment
    • Less pain
    • Lower risk of complications
    • Potential for outpatient procedures

    For instance, Intuitive Surgical Inc. reported that in 2022, around 1,875,000 surgeries were performed with Vinci systems, marking an 18% increase from the previous year. This growing preference for minimally invasive techniques is driving market expansion.

    Technological Advancements
    Major companies in the market are focusing on technological innovations to stay competitive. Advanced features such as multi-catheter compatibility enhance versatility and efficiency in procedures. Notable advancements include:

    • Boston Scientific’s EMBOLD Fibered Detachable Coil: Received FDA clearance in April 2022, designed for embolization in peripheral vasculature. This device features multi-catheter compatibility and a nitinol delivery system to streamline procedures and reduce complications.

    Strategic Acquisitions
    Boston Scientific’s acquisition of Obsidio Inc. in August 2022 exemplifies strategic moves to strengthen their embolization portfolio. Obsidio Inc. is known for its novel transcatheter embolic hydrogel (GEM) designed for minimally invasive delivery. This acquisition enhances Boston Scientific’s offerings in interventional oncology and embolization.

    Market Segmentation
    The transcatheter embolization and occlusion devices market is segmented as follows:

    1. By Type: Coil, Non-Coil
    2. By Application: Peripheral Vascular Disease, Oncology, Neurology, Urology, Other Applications
    3. By End User: Hospitals, Ambulatory Surgical Centers, Clinics, Other End Users

    Regional Insights
    In 2023, North America was the leading region in the transcatheter embolization and occlusion devices market. The region’s dominance is attributed to advanced healthcare infrastructure, high prevalence of vascular diseases, and significant investment in medical technologies.

    Conclusion
    The transcatheter embolization and occlusion devices market is poised for substantial growth, driven by advancements in technology, increasing demand for minimally invasive procedures, and strategic industry developments. As the market evolves, continued innovation and strategic acquisitions will play a crucial role in shaping its future.

    Request A Sample Of The Global Transcatheter Embolization And Occlusion Devices Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=15944&type=smp

  • Understand How The Wound Contact Layer Dressing Market Is Poised To Grow Through 2024-2033

    Understand How The Wound Contact Layer Dressing Market Is Poised To Grow Through 2024-2033

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    As per The Business Research Company’s Wound Contact Layer Dressing Global Market Report 2024, the wound contact layer dressing market is expected to show significant growth in the forecast period.

    The wound contact layer dressing market has experienced rapid expansion in recent years and is set to continue growing. This blog explores the market dynamics, including current trends, drivers of growth, and future prospects.

    Current Market Overview

    Growth Trajectory

    • 2023: Market size was $0.35 billion.
    • 2024: Expected to reach $0.39 billion.
    • CAGR: 11.8% during this period.

    Key Growth Drivers

    • Aging Population: An increasing number of elderly individuals requiring wound care.
    • Awareness and Expenditure: Rising awareness about wound care products and increased healthcare spending.
    • Home Healthcare Services: Growth in services provided at home.
    • Regulatory Approvals: More products gaining regulatory approvals and market entry.
    • Diabetes and Obesity: Increased incidence contributing to higher demand for wound care solutions.

    Future Market Prospects

    Projected Growth

    • 2028: Market size anticipated to reach $0.62 billion.
    • CAGR: 11.9% from 2024 to 2028.

    View More On The Wound Contact Layer Dressing Market Report 2024 – https://www.thebusinessresearchcompany.com/report/wound-contact-layer-dressing-global-market-report

    Forecast Drivers

    • Chronic Wounds: Increasing prevalence of chronic wounds requiring advanced care.
    • Geriatric Population: Growing number of elderly individuals needing specialized wound care.
    • Advanced Wound Care Awareness: Rising understanding and use of advanced wound care solutions.
    • Healthcare Infrastructure: Expansion and improvement of healthcare facilities.

    Trends to Watch

    • Advanced Materials: Development of new, more effective materials.
    • Biodegradable Solutions: Emphasis on environmentally friendly and sustainable products.
    • Customization: Increased focus on tailored wound care solutions.
    • Smart Technology: Integration of smart technologies for better wound management.
    • Chronic Wounds Focus: Greater attention on addressing chronic wounds.

    Accident-Driven Market Growth

    Impact of Accidents

    • Increased Incidents: Higher accident rates due to vehicle usage, distracted driving, and insufficient safety measures.
    • Demand for Dressings: Increased need for effective wound care products to manage injuries from accidents.

    Statistics

    • 2022: 2.8 million nonfatal workplace injuries and illnesses reported, a 7.5% increase from 2021.
    • Injury Increase: 4.5% rise in injuries and 26.1% rise in illnesses.

    Innovative Developments

    Smart Technologies and Delivery Systems

    • Dynamic Exudate Removal: Advanced technologies like dynamic exudate removal are enhancing wound care outcomes.
    • Example: Medela’s Invia integrated wound dressing launched in August 2023, featuring a three-layer fluid handling pad and Quick-Connector.

    Strategic Moves in the Market

    Essity’s Acquisition

    • December 2021: Essity AB acquired Hydrofera LLC for $116 million.
    • Purpose: To strengthen its advanced wound care portfolio and market position.

    Market Segmentation

    By Type

    • Silver, Silicone, Honey, Other Types

    By Product

    • Antimicrobial, Non-Antimicrobial

    By Application

    • Hospital, Clinic, Homecare, Other Applications

    Regional Insights

    • 2023: North America was the largest market.
    • Forecast: Asia-Pacific is expected to be the fastest-growing region.

    The wound contact layer dressing market is on a strong growth trajectory, driven by technological advancements, increasing healthcare needs, and strategic market expansions. The focus on innovation and addressing chronic wounds will be crucial for market participants aiming to capture future opportunities.

    Request A Sample Of The Global Wound Contact Layer Dressing Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=15964&type=smp

  • How Is The Biological Sample Collection Kits Market Expected To Grow Through 2024-2033

    How Is The Biological Sample Collection Kits Market Expected To Grow Through 2024-2033

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    According to The Business Research Company’s Biological Sample Collection Kits Global Market Report 2024, the biological sample collection kits market is expected to show promising growth in the forecast period.

    The biological sample collection kits market has experienced substantial growth in recent years and is set for continued expansion. The market size surged from $9.09 billion in 2023 to $10.20 billion in 2024, reflecting a compound annual growth rate (CAGR) of 12.2%. This growth is driven by several factors, including heightened disease screening awareness, a rise in home healthcare, an aging population, and an increased focus on preventive medicine. The expansion of infectious disease testing also plays a significant role.

    Future Growth Projections

    Looking ahead, the market is expected to reach $16.23 billion by 2028, maintaining a CAGR of 12.3%. This anticipated growth is attributed to several trends:

    • Point-of-Care Testing: Increasing preference for immediate test results.
    • Chronic Diseases: Higher incidence rates of chronic conditions.
    • Remote Patient Monitoring: Rising demand for monitoring patients from a distance.
    • Preventive Healthcare: Growing emphasis on health maintenance.
    • Infectious Diseases Awareness: Increased public knowledge about infections.

    Key trends for the future include advancements in point-of-care testing, microfluidics, personalized medicine, and technological innovations.

    View More On The Biological Sample Collection Kits Market Report 2024 – https://www.thebusinessresearchcompany.com/report/biological-sample-collection-kits-global-market-report

     Impact of Infectious Diseases

    The rise in infectious diseases significantly impacts the biological sample collection kits market. Infectious diseases, caused by pathogens like bacteria and viruses, are increasing due to global travel, urbanization, antimicrobial resistance, and environmental changes. Biological sample collection kits are essential for diagnosing, monitoring, and researching these diseases. For example, the CDC reported a 5.9% rise in tuberculosis (TB) cases in the U.S. in 2022, highlighting the growing need for efficient diagnostic tools.

    Innovations Enhancing Market Growth

    Innovation is a key driver of market growth. Companies are developing advanced products like personalized diagnostic test kits, tailored to individual health profiles. For instance, Cue Health’s at-home diagnostic test kits, launched in March 2023, offer a convenient solution for private and secure sample collection. Results are processed by a CLIA-certified lab and delivered through the Cue Health App.

    Strategic Partnerships and Market Expansion

    Strategic partnerships also play a crucial role in market development. In May 2022, Babson Diagnostics Inc. and Becton, Dickinson, and Company expanded their partnership to improve diagnostic blood collection in retail settings. This collaboration aims to deliver laboratory-quality results from small-volume capillary blood samples, enhancing accessibility and efficiency.

    Market Segmentation and Regional Insights

    The biological sample collection kits market is segmented as follows:

    • By Product: Swabs, Viral Transport Media, Blood Collection Kits, Other Products
    • By Application: Diagnostics, Research
    • By End-Use: Hospitals and Clinics, Homecare, Diagnostics Centers, Other End-Uses

    In 2023, North America was the largest market region. However, the Asia-Pacific region is projected to experience the fastest growth in the coming years, driven by increasing healthcare needs and technological advancements.

    Conclusion

    The biological sample collection kits market is on a strong upward trajectory, fueled by innovations, increased disease screening, and strategic partnerships. With ongoing advancements and a rising focus on personalized and preventive healthcare, the market is well-positioned for continued growth and development.

    Request A Sample Of The Global Biological Sample Collection Kits Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=15995&type=smp

  • Key Trends And Drivers In The Heart Defect Closure Device Market 2024

    Key Trends And Drivers In The Heart Defect Closure Device Market 2024

    The Business Research Company’s market reports offer an in-depth analysis on the market’s growth potential, major drivers, key trends and more.

    Market Overview

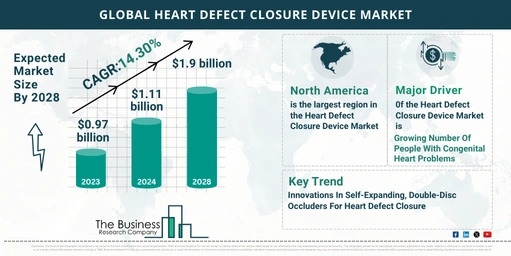
    The heart defect closure device market has experienced significant growth recently and is projected to continue expanding.

    • 2023: $0.97 billion
    • 2024: $1.11 billion (CAGR of 14.2%)
    • 2028: $1.90 billion (CAGR of 14.3%)

    This growth is driven by several factors, including the increasing prevalence of congenital heart problems, an aging population, rising health awareness, and advancements in medical technology.

    Key Drivers of Market Growth

    1. Rising Incidence of Congenital Heart Problems
    • Structural defects in the heart present from birth are on the rise.
    • Genetic factors, environmental influences, and maternal health issues contribute to the growing incidence.
    • Heart defect closure devices provide minimally invasive treatments to correct these defects, improving cardiac function and reducing complications.
    1. Technological Advancements
    • Improvements in catheterization techniques and diagnostic technologies are driving market growth.
    • The rise in MRI procedures and the use of 3D imaging in heart defect closure are notable trends.
    1. Aging Population
    • The prevalence of heart defects increases with age, impacting a significant portion of the elderly population.

    Read More On The Heart Defect Closure Device Market Report 2024 – https://www.thebusinessresearchcompany.com/report/heart-defect-closure-device-global-market-report

    Innovations in Heart Defect Closure Devices

    1. Self-Expanding, Double-Disc Occluders
    • Companies are developing advanced occluders that enhance procedural safety and patient outcomes.
    • Example: Abbott Laboratories’ Amplatzer Talisman PFO Occlusion System, launched in September 2022, uses a self-expanding, double-disc occluder to seal patent foramen ovale (PFO) with minimal invasiveness.
    1. Expansion of Product Portfolios
    • Haemonetics Corporation’s acquisition of Cardiva Medical in March 2021 expands its range of vascular closure solutions, offering more options for heart defect treatments.

    Major Market Players

    The heart defect closure device market features several prominent companies:

    • Abbott Laboratories
    • Medtronic
    • Koninklijke Philips N.V.
    • Boston Scientific Corporation
    • Terumo Corporation
    • Edwards Lifesciences
    • W L Gore and Associates
    • BIOTRONIK SE & Co. KG
    • Lepu Medical Technology
    • Meril Life Sciences Pvt. Ltd.
    • MicroPort Scientific Corporation
    • AtriCure Inc.
    • LifeTech Scientific Corporation
    • Baylis Medical Company Inc.

    Market Segmentation

    1. By Type
    • Atrial Septal Defect (ASD) Closure Devices
    • Left Atrial Appendage (LAA) Closure Devices
    • Patent Foramen Ovale (PFO) Closure Devices
    • Patent Ductus Arteriosus (PDA) Closure Devices
    • Ventricular Septal Defect (VSD) Closure Devices
    1. By Material
    • Nitinol-Based Devices
    • Stainless Steel Devices
    • Other Materials
    1. By Mode of Delivery
    • Transcatheter Delivery
    • Surgical Delivery
    • Other Modes
    1. By End-User
    • Hospitals
    • Clinics
    • Ambulatory Surgical Centers
    • Other End-Users

    Regional Insights

    • North America: The largest market in 2023.
    • Asia-Pacific: Expected to be the fastest-growing region in the forecast period.

    Conclusion

    The heart defect closure device market is poised for robust growth, fueled by technological innovations, increasing prevalence of heart defects, and advancements in diagnostic and treatment methods. The market’s future looks promising with continued development and adoption of advanced devices aimed at improving patient outcomes.

    Request for A Sample Of The Global Heart Defect Closure Device Market Report:
    https://www.thebusinessresearchcompany.com/sample_request?id=16074&type=smp

  • What’s The Growth Forecast For Histology Equipment Market Through 2024-2033?

    What’s The Growth Forecast For Histology Equipment Market Through 2024-2033?

    The Business Research Company’s global market reports provide comprehensive analysis on the various markets in 27 industries across 60 geographies.

     Steady Growth in Recent Years

    The histology equipment market has experienced consistent growth, with the market size increasing from $0.62 billion in 2023 to $0.65 billion in 2024. This growth represents a compound annual growth rate (CAGR) of 4.4%. Several factors have contributed to this steady rise:

    • High Prevalence of Chronic Diseases: Increased chronic disease rates drive demand for diagnostic equipment.
    • Increased Healthcare Expenditure: Greater investment in healthcare infrastructure boosts equipment demand.
    • Technological Innovations: Advancements in imaging technologies improve diagnostic accuracy.
    • Expansion of Research Activities: Enhanced research drives the need for advanced histology tools.
    • Aging Population: An older global population increases the demand for diagnostic equipment.

    Forecasted Growth and Market Drivers

    Looking ahead, the histology equipment market is projected to grow to $0.78 billion by 2028, at a CAGR of 4.6%. This future growth is attributed to several key factors:

    • Increasing Cancer Prevalence: The rising incidence of cancer necessitates advanced diagnostic tools.
    • Demand for Personalized Medicine: Tailored treatment approaches drive demand for precise diagnostic equipment.
    • Growing Healthcare Infrastructure: Expansion in emerging markets supports market growth.
    • Technological Advancements: Innovations in imaging techniques enhance diagnostic capabilities.
    • Expanding Geriatric Population: A larger elderly demographic increases diagnostic needs.
    • R&D in Life Sciences: Continued research in life sciences fuels demand for histology equipment.

    View More On The Histology Equipment Market Report 2024 – https://www.thebusinessresearchcompany.com/report/histology-equipment-global-market-report

    Major Trends Shaping the Market

    Several trends are shaping the histology equipment market, including:

    • Automation Adoption: Increasing use of automated systems to improve efficiency.
    • Digital Pathology: Rising demand for digital imaging and pathology solutions.
    • Personalized Medicine: Growth in tailored treatment approaches.
    • Advancements in Tissue Staining: Improved staining technologies enhance diagnostic accuracy.
    • Oncology Research: Expanding focus on cancer research drives equipment demand.
    • Workflow Efficiency: Increased focus on optimizing lab workflows.
    • Infrastructure Investments: Higher investments in laboratory facilities.

    Rising Cancer Burden

    The growing burden of cancer significantly impacts the histology equipment market. Cancer diagnosis and treatment require precise and detailed tissue examination. Factors contributing to the rise in cancer cases include:

    • Lifestyle Factors: Modifiable lifestyle choices impact cancer prevalence.
    • Biological and Demographic Factors: Non-modifiable factors such as genetics and age contribute to cancer risk.

    For example, in 2021, it was projected that 151,000 individuals in Australia would be diagnosed with cancer, excluding basal cell and squamous cell carcinomas. By 2031, new cancer cases are expected to rise to 185,000, highlighting the increasing need for advanced histology equipment.

    Innovations and Acquisitions

    Next-Generation Slide Scanners: Companies are developing advanced slide scanners to enhance image quality and diagnostic precision. For instance, Roche launched the VENTANA DP 600 slide scanner in June 2022, offering high-resolution images and improved workflow integration.

    Acquisition by StatLab Medical Products: In March 2024, StatLab Medical Products acquired Poly Scientific R&D Corp., including its subsidiary Histology Control Systems, Inc. This acquisition expands StatLab’s manufacturing capabilities and market reach, enhancing its product offerings in histology.

    Market Segmentation

    The histology equipment market is segmented into:

    1. By Type: Includes slide staining systems, scanners, tissue processing systems, microtomes, coverslippers, and other types.
    2. By Product: Comprises instruments and analysis software systems, consumables, and reagents.
    3. By Application: Serves hospitals, pharmaceutical companies, diagnostic centers, academic institutes, research laboratories, and other applications.

    Regional Insights:

    • North America: Dominated the market in 2023.
    • Asia-Pacific: Expected to be the fastest-growing region during the forecast period.

    Conclusion

    The histology equipment market is poised for steady growth driven by technological advancements, increasing cancer prevalence, and expanding healthcare infrastructure. Innovations in imaging and automation, along with strategic acquisitions, are expected to further propel the market. As the demand for precise diagnostic tools continues to rise, the histology equipment market remains a critical component of modern medical diagnostics.

    Request A Sample Of The Global Histology Equipment Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=16080&type=smp


  • Comprehensive Analysis On Size, Share, And Drivers Of The Pipettes And Accessories Market

    Comprehensive Analysis On Size, Share, And Drivers Of The Pipettes And Accessories Market

    The Business Research Company’s global market reports provide comprehensive analysis on the various markets in 27 industries across 60 geographies. 

    Market Overview

    The pipettes and accessories market has experienced robust growth recently and is set to continue expanding. The market size grew from $1.35 billion in 2023 to $1.42 billion in 2024, reflecting a compound annual growth rate (CAGR) of 5%. This upward trend is driven by several key factors:

    • Increased Demand for Precision: The need for accurate liquid handling in laboratories is rising.
    • Pharmaceutical Research Expansion: Growth in drug research and development is pushing demand.
    • Prevalence of Chronic Diseases: More chronic conditions require precise diagnostic tools.
    • High-Throughput Screening: There’s a growing requirement for efficient screening processes.
    • Funding for Life Sciences: Increased investments in research drive market growth.
    • Lab Expansion: Clinical and diagnostic labs are expanding, boosting demand for pipettes and accessories.

    Future Growth Projections

    Looking ahead, the market is expected to reach $1.73 billion by 2028, with a CAGR of 5.1%. Several factors will contribute to this growth:

    • Precision Demand: Continued focus on accuracy in lab research.
    • Clinical Diagnostics Growth: Rising needs in clinical settings.
    • Environmental Testing: Increased focus on testing for environmental applications.
    • Biopharmaceutical R&D: Expanding research and development in biopharma.
    • Investment in Life Sciences: Growing funding supports market expansion.
    • Personalized Medicine: Rising demand for customized treatment solutions.

    View More On The Pipettes And Accessories Market Report 2024 – https://www.thebusinessresearchcompany.com/report/pipettes-and-accessories-global-market-report

    Key trends shaping the future include:

    • Automated Liquid Handling: Increasing adoption of automation technologies.
    • Ergonomic Designs: Advancements in pipette ergonomics.
    • Electronic Pipettes: Growing use of advanced electronic pipettes.
    • Multi-Channel Pipettes: Rising adoption for high-throughput screening.
    • Eco-Friendly Tips: Development of recyclable and eco-friendly pipette tips.
    • IoT and AI Integration: Enhanced lab efficiency through smart technologies.

    Impact of the Pharmaceutical Industry

    The pharmaceutical industry’s expansion is significantly influencing the pipettes and accessories market. As pharmaceutical companies grow, so does the demand for precision instruments crucial in drug formulation and analytical testing. The industry’s progress is driven by:

    • Chronic Diseases: Increasing cases necessitate precise medical testing.
    • Research and Technology Advances: New technologies and research methodologies boost demand.
    • Healthcare Expenditures: Higher investments in healthcare contribute to market growth.

    For example, the European pharmaceutical market saw a value increase from €2,360.90 million in 2020 to an estimated €2,550.00 million in 2021, highlighting the sector’s economic significance and its impact on related markets like pipettes and accessories.

    Major Market Players

    Leading companies in the pipettes and accessories market include:

    • Thermo Fisher Scientific Inc.
    • Corning Incorporated
    • VWR International LLC
    • Mettler Toledo
    • Bio-Rad Laboratories Inc.
    • Eppendorf SE
    • Sarstedt AG & Co. KG
    • Hamilton Company
    • Greiner Bio-One International GmbH
    • Cole-Parmer Instrument Company LLC

    These companies are at the forefront of innovation, continually developing new technologies to enhance lab workflows and data management.

    Technological Advancements

    Recent advancements in Bluetooth connectivity are revolutionizing pipetting workflows. For example, Sartorius AG’s Picus 2 electronic pipettes, launched in September 2023, feature Bluetooth connectivity. This integration allows for:

    • Seamless Data Transfer: Efficient communication with lab software.
    • Real-Time Data Sharing: Instant access to data for better decision-making.
    • Streamlined Workflows: Enhanced efficiency in laboratory operations.

    Strategic Acquisitions

    The acquisition of VistaLab Technologies by CELLTREAT Scientific Products in March 2022 exemplifies the strategic moves within the market. This acquisition enhances CELLTREAT’s lab product portfolio and extends its distribution reach, fostering innovation and delivering superior solutions.

    Market Segmentation

    The pipettes and accessories market is segmented as follows:

    1. By Type:
      • Manual Pipettes
      • Electronic Pipettes
      • Accessories
    2. By Channel Type:
      • Single Channel
      • Multi-Channel
    3. By Application:
      • Hospitals
      • Academic and Research Institutes
      • Pharmaceutical and Biotechnology Companies
      • Other Applications

    Regional Insights

    In 2023, North America was the largest market for pipettes and accessories. However, the Asia-Pacific region is expected to experience the fastest growth in the forecast period due to increasing investment in research and expanding healthcare infrastructure.

    As the pipettes and accessories market continues to grow, technological innovations and strategic developments will play crucial roles in shaping its future.

    Request A Sample Of The Global Pipettes And Accessories Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=16148&type=smp

  • What Is The Forecast Growth Rate For The Surgical Meshes Market?

    What Is The Forecast Growth Rate For The Surgical Meshes Market?

    The Business Research Company’s market reports offer an in-depth analysis on the market’s growth potential, major drivers, key trends and more.

    Market Overview

    The surgical meshes market has witnessed significant growth in recent years, driven by various factors including technological advancements and increasing surgical procedures. The market size surged from $1.87 billion in 2023 to $2.03 billion in 2024, reflecting a compound annual growth rate (CAGR) of 8.3%. This growth is attributed to the high demand for advanced meshes, improved patient outcomes, and the growing economy and population in emerging countries.

    Looking ahead, the market is expected to continue its upward trajectory, reaching $2.66 billion by 2028 at a CAGR of 7.0%. This anticipated growth is fueled by the increase in surgical procedures, the rising incidence of hernias, the aging population, and expanding research and development activities.

    Growth Drivers

    Rising Number of Surgical Procedures

    • Increasing Procedures:The growing number of surgical interventions is a major driver for the surgical meshes market. Aging populations are more prone to conditions requiring surgery, such as joint replacements and heart bypasses.
    • Global Surge in Surgeries:For instance, in January 2023, the International Society of Aesthetic Plastic Surgery reported a 19.3% global rise in procedures, highlighting a surge in cosmetic and reconstructive surgeries.
    • Role of Surgical Meshes:Surgical meshes are crucial for reinforcing weakened tissues, preventing hernia recurrence, aiding wound closure, and facilitating minimally invasive techniques.

    Read More On The Surgical Meshes Market Report 2024 – https://www.thebusinessresearchcompany.com/report/surgical-meshes-global-market-report

    Key Market Trends

    Technological Advancements

    • Innovative Products:Companies are developing advanced products like dual surgical meshes. These meshes combine permanent and temporary features, offering benefits such as reduced foreign body reactions and easy customization.
    • Recent Innovations:For example, Futura Surgicare Pvt Ltd. launched a dual surgical mesh range in February 2022 with features such as precision laser-cut fused edges and a lightweight design.

    Product Variety and Customization

    • Diverse Mesh Types:The market offers various types of surgical meshes including synthetic, biosynthetic, biologic, and hybrid or composite meshes.
    • Customization:The availability of surgical netting in various sizes, textures, and types enhances flexibility and effectiveness in surgical procedures.

    Major Companies

    Several prominent players are leading the surgical meshes market:

    • Medtronic Plc
    • Becton, Dickinson and Company
    • Boston Scientific Corporation
    • Braun Melsungen AG
    • Zimmer Biomet Holdings Inc.
    • Ethicon Inc.
    • L. Gore & Associates Inc.
    • Maquet Getinge Group
    • Mölnlycke Health Care AB
    • R. Bard Inc.
    • LifeNet Health Inc.
    • TELA Bio
    • LifeCell International Pvt. Ltd.
    • Lotus Surgicals Private Limited

    Strategic Developments

    Becton, Dickinson and Company’s Acquisition

    • Tissuemed Ltd. Acquisition:In December 2021, Becton, Dickinson and Company acquired Tissuemed Ltd., a UK-based manufacturer of surgical mesh. This acquisition enhances BD’s global offerings and introduces an innovative surgical sealant to their product suite.

    Market Segmentation

    The surgical meshes market is segmented as follows:

    1. By Product Type:
      • Synthetic Surgical Meshes
      • Biosynthetic Surgical Meshes
      • Biologic Surgical Meshes
      • Hybrid or Composite Surgical Meshes
    2. By Nature:
      • Absorbable Surgical Meshes
      • Non-Absorbable Surgical Meshes
      • Partially Absorbable Surgical Meshes
    3. By Sales Channel:
      • Direct Channel
      • Indirect Channel
    4. By Application:
      • Hernia Repair
      • Traumatic or Surgical Wounds
      • Abdominal Wall Reconstruction
      • Facial Surgery
    5. By End-User:
      • Hospitals
      • Ambulatory Surgical Centers
      • Clinics
      • Other End-Users

    Regional Insights

    • North America:Dominated the surgical meshes market in 2023.
    • Asia-Pacific:Expected to be the fastest-growing region during the forecast period.

    In summary, the surgical meshes market is set for robust growth, driven by technological advancements, increased surgical procedures, and strategic developments by major players. The industry is poised to continue evolving with innovations that enhance surgical outcomes and patient safety.

    Request for A Sample Of The Global Surgical Meshes Market Report:
    https://www.thebusinessresearchcompany.com/sample_request?id=14211&type=smp

  • Global 3D And 4D Ultrasound Devices Market Key Insights 2024-2033

    Global 3D And 4D Ultrasound Devices Market Key Insights 2024-2033

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    According to The Business Research Company’s 3D And 4D Ultrasound Devices Global Market Report 2024, the 3D and 4D ultrasound devices market is expected to show promising growth in the forecast period.

    Market Overview

    • Current Market Size: The 3D and 4D ultrasound devices market grew from $9.34 billion in 2023 to $11.53 billion in 2024.
    • Growth Rate: This represents a compound annual growth rate (CAGR) of 23.4%.
    • Historic Drivers:
      • Increased prevalence of chronic diseases
      • Growing aging population
      • Rising awareness and education
      • Expanding applications in obstetrics and gynecology
      • Government initiatives and funding

    Future Projections

    • Forecasted Growth: The market is expected to reach $26.26 billion by 2028.
    • Forecast CAGR: Projected CAGR of 22.8%.
    • Forecast Drivers:
      • Focus on telemedicine
      • Economic growth and emerging markets
      • Advancements in 4D imaging technology
      • Personalized medicine and precision healthcare
      • Miniaturization and portability
    • Major Trends:
      • Technological advancements in 4D imaging
      • Innovations in imaging technology
      • Enhanced image resolution and clarity

    View More On The 3D And 4D Ultrasound Devices Market Report 2024 – https://www.thebusinessresearchcompany.com/report/3d-and-4d-ultrasound-devices-global-market-report

    Addressing Chronic Diseases with Advanced Ultrasound Technologies

    • Impact of Chronic Diseases: The growing prevalence of chronic diseases drives demand for advanced diagnostic technologies.
    • Role of 3D and 4D Ultrasound: Provides detailed, three-dimensional images for diagnosing and monitoring chronic conditions.
    • Example: By 2050, the number of individuals aged 50 and above with at least one chronic illness is projected to double, emphasizing the need for advanced imaging solutions.

    Leading Companies in the Market

    • Key Players:
      • Hitachi Ltd.
      • Medtronic plc
      • Toshiba Corporation
      • Siemens Healthineers
      • Koninklijke Philips N.V.
      • GE HealthCare Technologies Inc.
      • Fujifilm Holdings Corporation
      • Konica Minolta Healthcare Americas Inc.
      • Hologic Inc.
      • Mindray Medical International Limited
      • Canon Medical Systems Corporation
      • Carestream Health Inc.
      • Samsung Medison Co. Ltd.
      • Analogic Corporation
      • Alpinion Medical Systems Co. Ltd.
      • Shenzhen Bestman Instrument Co. Ltd.
      • Chison Medical Technologies Co. Ltd.

    Innovations in Portable Ultrasound Devices

    • Technological Focus: Companies are developing advanced ultrasound technologies such as ultrasound-on-chip.
    • Benefits of Innovation:
      • Miniaturizes components onto a single chip
      • Enables compact and portable ultrasound devices
      • Enhances accessibility for point-of-care and wearable applications
    • Example: Butterfly Network Inc. launched the Butterfly iQ3 in June 2023, featuring the P4.3 ultrasound-on-chip technology. This system offers enhanced high-resolution imaging and greater portability compared to its predecessor.

    Strategic Acquisitions and Expansions

    • GE Healthcare Acquisition: In December 2021, GE Healthcare acquired BK Medical Systems Inc. for $1.45 billion.
    • Strategic Impact:
      • Expands GE Healthcare’s capabilities in advanced surgical imaging
      • Broadens its ultrasound enterprise to include surgical and therapeutic applications
    • BK Medical Systems: Known for its expertise in 3D ultrasound devices and surgical visualization products.

    Market Segmentation

    • By Type:
      • Stationary 3D and 4D Ultrasound Devices
      • Portable 3D and 4D Ultrasound Devices
    • By Display:
      • Color Ultrasound
      • Black and White (B/W) Ultrasound
    • By Portability:
      • Trolley or Cart-Based Ultrasound Systems
      • Compact or Handheld Ultrasound Systems
      • Point-of-Care (PoC) Ultrasound Systems
    • By Application:
      • Radiology or General Imaging
      • Obstetrics or Gynecology
      • Cardiology
      • Urology
      • Vascular
      • Orthopedic and Musculoskeletal
      • Pain Management
      • Other Applications
    • By End-User:
      • Hospitals
      • Surgical Centers and Diagnostic Centers
      • Maternity Centers
      • Ambulatory Care Centers
      • Other End-Users

    Regional Insights

    • Current Leading Region: North America was the largest market for 3D and 4D ultrasound devices in 2023.
    • Future Growth: Asia-Pacific is anticipated to be the fastest-growing region in the forecast period.

    The 3D and 4D ultrasound devices market is experiencing substantial growth driven by technological advancements, increased chronic disease prevalence, and expanding applications. As the market evolves, innovations in imaging technology and strategic acquisitions will continue to shape its future landscape.

    Request A Sample Of The Global 3D And 4D Ultrasound Devices Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=14233&type=smp

  • How Is The Serum Separation Gel Market Expected To Grow Through 2024-2033

    How Is The Serum Separation Gel Market Expected To Grow Through 2024-2033

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    According to The Business Research Company’s Serum Separation Gel Global Market Report 2024, the serum separation gel market is expected to show promising growth in the forecast period.

    Market Growth Overview

    • Current Market Size
      • The serum separation gel market is set to grow from $8.22 billion in 2023 to $8.92 billion in 2024, at a robust CAGR of 8.5%.
      • Growth drivers include increased healthcare expenditure, higher demand for diagnostic testing, expansion of the healthcare industry, and rising prevalence of chronic diseases.
    • Future Market Projections
      • The market is expected to reach $12.58 billion by 2028, with a CAGR of 9.0%.
      • Future growth is driven by the increasing incidence of hematologic disorders, emphasis on point-of-care testing, expansion in emerging markets, and demand for personalized medicine.

    Drivers of Market Growth

    Rising Demand for Diagnostic Testing

    • Importance of Diagnostic Testing
      • Diagnostic testing helps in early disease detection and preventive healthcare measures.
      • Serum separation gel is crucial in separating serum from blood cells, enabling accurate disease analysis.
    • Market Impact
      • Increased diagnostic tests drive the demand for serum separation gels.
      • For example, in January 2024, there was a 13% increase in diagnostic tests in the UK compared to January 2020.

    Key Players in the Market

    • Major Companies
      • Leading companies include Cardinal Health Inc., Thermo Fisher Scientific Inc., Danaher Corporation, Becton Dickinson and Company, Corning Incorporated, and Bio-Rad Laboratories Inc.

    View More On The Serum Separation Gel Market Report 2024 – https://www.thebusinessresearchcompany.com/report/serum-separation-gel-global-market-report

    Technological Innovations

    Introduction of Serum Fast Separator Tubes

    • Innovative Solutions
      • Companies are developing novel products like serum fast separator tubes for faster blood sample processing.
      • These tubes use specialized gel and clot activators to speed up serum separation.
    • Case Study: Greiner Bio-One
      • In May 2023, Greiner Bio-One launched VACUETTE CAT Serum Fast Separator.
      • This tube accelerates the clotting process, reducing coagulation time to approximately 5 minutes.

    Strategic Acquisitions

    Abcam Acquires BioVision Inc.

    • Expansion of Capabilities
      • In October 2021, Abcam acquired BioVision Inc. for $340 million.
      • This acquisition enhances Abcam’s immunoassay capabilities and expands its range of research tools.

    Market Segmentation and Regional Insights

    Market Segmentation

    • By Type
      • Serum Separation Gel Integrated with Tube
      • Serum Separation Gel Without Tube
    • By Formulation
      • Powder Gel
      • Liquid Gel
    • By End User
      • Hospitals and Clinics
      • Pharmaceutical and Biotechnology Companies
      • Diagnostic Laboratories
      • Blood Banks

    Regional Dynamics

    • Largest Market: North America
      • North America held the largest market share in 2023.
    • Fastest-Growing Region: Asia-Pacific
      • Asia-Pacific is expected to experience the fastest growth during the forecast period, driven by increased healthcare investments and technological advancements.

    Conclusion

    • The serum separation gel market is poised for significant growth, driven by rising healthcare expenditure, increasing demand for diagnostic testing, and technological innovations.
    • Strategic acquisitions and the introduction of novel products will further enhance market dynamics.
    • With North America leading the market and Asia-Pacific showing rapid growth, the global serum separation gel market is set for a transformative journey, addressing the evolving needs of the healthcare industry.

    Request A Sample Of The Global Serum Separation Gel Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=15270&type=smp

  • 5 Key Insights On The Rehabilitation Equipment Market 2024

    5 Key Insights On The Rehabilitation Equipment Market 2024

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    As per The Business Research Company’s Rehabilitation Equipment Global Market Report 2024, the rehabilitation equipment market is expected to show significant growth in the forecast period.

    Market Expansion and Growth Projections

    • Current Growth
      • The rehabilitation equipment market grew from $16.27 billion in 2023 to an anticipated $17.36 billion in 2024, at a 6.7% CAGR.
      • Historical growth driven by an aging population, rising incidences of disabilities, increased sports participation, chronic diseases, sports injuries, and preventive healthcare focus.
    • Future Growth
      • Expected to reach $22.84 billion by 2028, with a 7.1% CAGR.
      • Growth drivers include personalized medicine, rising healthcare expenditure, telemedicine, and increasing degenerative diseases prevalence.

    Rising Demand for Home Healthcare Services

    • Home Healthcare Trends
      • Home healthcare services encompass a range of medical and non-medical care provided at home.
      • Growth factors: aging populations, medical technology advancements, and a shift towards value-based care.
    • Market Impact
      • Rehabilitation equipment in home healthcare promotes recovery, independence, and patient safety.
      • In 2021, Medicare Fee for Service users utilizing home health care increased by 8.3% to about 3 million, with 11,474 Medicare-certified home health organizations.

    View More On The Rehabilitation Equipment Market Report 2024 – https://www.thebusinessresearchcompany.com/report/rehabilitation-equipment-global-market-report

    Key Players in the Market

    • Major Companies
      • Leading companies include Medtronic plc, Medline Industries Inc., Koninklijke Philips N.V., Stryker Corporation, Hill-Rom Holdings Inc., and Arjo.

    Technological Advancements: VR-Based Rehabilitation

    • Innovative Solutions
      • Companies are developing VR-based rehabilitation platforms to stay competitive.
      • VR platforms facilitate rehabilitation for physical or cognitive impairments, enhancing patient engagement and outcomes.
    • Case Study: Penumbra Inc.
      • In November 2022, Penumbra Inc. launched the REAL y-Series, a full-body VR-based rehab platform for upper and lower extremities.
      • The platform supports physical, cognitive, and mental well-being, offering comprehensive therapy solutions.

    Strategic Acquisitions: Ekso Bionics and Parker Hannifin

    • Expanding Portfolio
      • In December 2022, Ekso Bionics acquired Parker Hannifin Corporation for $10 million.
      • The acquisition enhances Ekso Bionics’ product portfolio for home use and strengthens its position in lower-extremity robotic products.
    • Global Reach
      • The acquisition enables key commercial and research partnerships, including with Vanderbilt University, expanding Ekso Bionics’ global footprint.

    Market Segmentation and Regional Dynamics

    • Segmentation Overview
      • By Product:Therapy Devices, Daily Living Aids, Mobility Equipment, Exercise Equipment, Body Support Devices.
      • By Application:Physiotherapy, Occupational Therapy, Other Applications.
      • By End-use:Hospitals and Clinics, Rehab Centers, Home Care Settings, Physiotherapy Centers.
    • Regional Insights
      • North America was the largest region in 2023.
      • Asia-Pacific is expected to be the fastest-growing region in the forecast period, driven by increased healthcare investments and technological adoption.

    Conclusion

    • The rehabilitation equipment market is set for robust growth, fueled by advancements in personalized medicine, telemedicine, and AI integration.
    • Innovations in VR-based rehabilitation and strategic acquisitions are reshaping the market landscape.
    • As demand for home healthcare services rises, the market evolves to meet diverse needs, promoting recovery and independence in patient care.
    • With significant growth in North America and rapid expansion in Asia-Pacific, the global rehabilitation equipment market continues to innovate and expand, addressing the needs of an aging population and a growing prevalence of chronic conditions.

    Request A Sample Of The Global Rehabilitation Equipment Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=15256&type=smp