Category: Medical Equipment

  • Respiratory Devices And Equipment (Therapeutic) Market Report 2024: Market Size, Drivers, And Trends

    Respiratory Devices And Equipment (Therapeutic) Market Report 2024: Market Size, Drivers, And Trends

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    Introduction: An Expanding Horizon The therapeutic respiratory devices and equipment market have experienced a remarkable surge, witnessing substantial growth from $19.9 billion in 2023 to an estimated $22.01 billion in 2024, boasting a robust Compound Annual Growth Rate (CAGR) of 10.6%. The roots of this growth can be traced back to the prevalence of respiratory conditions, an aging population, continuous technological advancements, and the effective management of respiratory diseases.

    Rapid Growth on the Horizon Projections for 2028: The therapeutic respiratory devices and equipment market are poised for rapid growth, projected to reach $32.61 billion by 2028, with a CAGR of 10.3%. This surge is fueled by factors such as the rise in chronic diseases, lifestyle-related issues, the expansion of telehealth, technological innovations, and the effective management of Chronic Obstructive Pulmonary Disease (COPD).

    Smoker Population Driving Demand Alarming Statistics: The surge in the number of smokers is anticipated to be a significant catalyst for the growth of the therapeutic respiratory devices and equipment market. Smokers, engaging in tobacco consumption through various means, are increasingly relying on respiratory devices like inhalers and nebulizers to manage conditions such as COPD, chronic bronchitis, and lung cancer. Statistics from Canada: In July 2022, Statistics Canada reported a 5.8% increase in cigarette production compared to June 2021, with a total of 1.4 billion cigarettes sold in June 2022. This uptick underscores the growing demand for therapeutic respiratory devices among smokers.

    Market Players: Pioneering the Way Forward Key Industry Players: Major companies contributing to the growth of the therapeutic respiratory devices and equipment market include Hamilton Medical AG, Koninklijke Philips N.V., Smiths Medical, GE Healthcare, and others. These entities play a crucial role in shaping the landscape of respiratory healthcare.

    View More On The Respiratory Devices And Equipment (Therapeutic) Market Report 2024 – https://www.thebusinessresearchcompany.com/report/respiratory-devices-and-equipment-therapeutic-global-market-report

    Innovations in Artificial Intelligence (AI): Revolutionizing Treatment AI Integration: The industry is witnessing a paradigm shift with the integration of Artificial Intelligence (AI) in the development of respiratory devices. AI supports the creation of innovative sensors-equipped inhalers, enabling patients to monitor their dosage intake. These sensors, both add-on and embedded, track data automatically, providing real-time insights to both doctors and patients. AI-powered Wearable Lung Monitor: In March 2022, Respira Labs introduced ‘Sylvee,’ an AI-powered wearable lung monitor. Utilizing acoustic resonance, it assesses lung function and detects variations, showcasing the potential of AI in respiratory care.

    Strategic Acquisitions: Expanding Solutions Portfolio Zoll Medical Corporation’s Acquisition: In April 2021, ZOLL Medical Corporation acquired Respicardia Inc., a move aimed at expanding its portfolio to cater to patients with respiratory and cardiovascular diseases. This strategic acquisition aligns with the industry’s commitment to providing comprehensive solutions for respiratory health.

    Market Segmentation: A Holistic View Product Segmentation: The therapeutic respiratory devices and equipment market is segmented by product, including nebulizers, humidifiers, oxygen concentrators, positive airway pressure devices, ventilators, capnographs, and gas analyzers. Technology Segmentation: The market is further segmented by technology, encompassing HEPA filter, electrostatic filtration, microsphere separation, hollow fiber filtration, and other technologies. End-User Segmentation: The end-user landscape includes homecare settings and hospitals, reflecting the diverse applications of therapeutic respiratory devices.

    Dominance in Asia-Pacific: A Regional Spotlight Regional Landscape: In 2023, Asia-Pacific emerged as the largest region in the therapeutic respiratory devices market. The region’s dominance is indicative of the growing healthcare needs and the increasing prevalence of respiratory conditions.

    Conclusion: A Breath of Progress The therapeutic respiratory devices and equipment market stand at the forefront of innovation and growth. With a focus on technological advancements, strategic acquisitions, and a commitment to providing holistic solutions, the industry is poised to address the evolving needs of patients with respiratory conditions. As digital health, remote monitoring, and AI continue to shape the landscape, the future holds promise for a more accessible and effective respiratory healthcare ecosystem. Stakeholders across the healthcare spectrum must stay attuned to these developments to capitalize on the opportunities presented by this dynamic market.

    Request A Sample Of The Global Respiratory Devices And Equipment (Therapeutic) Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=2844&type=smp

  • Global PCR And Realtime PCR Testing Market Analysis 2024: Size, Share, And Key Trends

    Global PCR And Realtime PCR Testing Market Analysis 2024: Size, Share, And Key Trends

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    As per The Business Research Company’s PCR And Realtime PCR Testing Global Market Report 2024, the PCR and realtime PCR testing market is expected to show significant growth in the forecast period.

    The PCR and real-time PCR testing market has experienced robust growth in recent years, showcasing a steady upward trajectory. With the market size set to reach $22.03 billion in 2024 and a projected surge to $27.78 billion by 2028 at a CAGR of 6.0%, various factors contribute to this upward trend.

    Historical Growth Catalysts

    • Disease Diagnosis and Research:PCR and real-time PCR have played a pivotal role in disease diagnosis and genomic studies.
    • Automation and High Throughput:The adoption of automation and high throughput technologies has accelerated the market’s historical growth.
    • Pharmaceutical and Biotechnology Applications:PCR’s applications in pharmaceutical and biotechnology industries have been crucial for research and development.
    • Point-of-Care Testing:The convenience of point-of-care testing has significantly contributed to market expansion.

    Forecasted Growth Drivers

    • Pandemic Response:The ongoing need for effective testing in response to pandemics fuels market growth.
    • Precision Medicine:Growing applications in precision medicine contribute to the anticipated market surge.
    • Cancer Diagnostics:PCR’s role in cancer diagnostics enhances its significance in the healthcare landscape.
    • Infectious Disease Surveillance:The focus on infectious disease surveillance continues to drive demand for PCR testing.

    View More On The PCR And Realtime PCR Testing Market Report 2024 – https://www.thebusinessresearchcompany.com/report/pcr-and-realtime-pcr-testing-global-market-report

    Key Trends in the Forecast Period

    • Infectious Disease Testing:Increased emphasis on infectious disease testing aligns with global health priorities.
    • Point-of-Care Testing:The demand for convenient and rapid point-of-care testing remains a key trend.
    • Digital PCR:Advancements in digital PCR technology offer enhanced accuracy and sensitivity.
    • Multiplex Assays:Multiplex assays enable the simultaneous detection of multiple targets, improving efficiency.

    Rising Approvals for Personalized Medicines Driving Market Growth

    The rising approvals for personalized medicines emerge as a significant driver for the PCR and real-time PCR testing market. Personalized medicines, tailored to individual patient characteristics, utilize PCR technology for precise genetic identification. In 2021, 35% of FDA-approved new molecular entities were classified as personalized medicines, demonstrating the increasing role of PCR in this field. This personalized approach enhances treatment efficacy by aligning interventions with patients’ genetic, biomarker, and psychosocial characteristics.

    Major Players Shaping the Market

    Leading companies influencing the PCR and real-time PCR testing market include:

    • Abbott Laboratories
    • Agilent Technologies Inc.
    • bioMérieux SA
    • Bio-Rad Laboratories Inc.
    • Hoffmann-La Roche Ltd.
    • QIAGEN N.V.
    • GenMark Diagnostics Inc.
    • Thermo Fisher Scientific Inc.
    • BioFire Diagnostics LLC
    • Cepheid Inc.
    • Illumina Inc.
    • Oxford Nanopore Technologies Ltd.
    • Myriad Genetics Inc.

    Advanced Diagnostic Tool for Ankylosing Spondylitis

    Major companies in the market are focused on developing advanced diagnostic tools. For instance, Mylab Discovery Solutions launched the Discover Series HLAB*27 Detection Kit, an RT-PCR diagnostic instrument designed to diagnose Ankylosing Spondylitis. This kit, utilizing real-time PCR technology, offers almost 100% accuracy, addressing a critical need for early detection in genetically susceptible individuals.

    Market Segmentation: Unraveling Complexity

    The PCR and real-time PCR testing market is segmented based on:

    1. Product:Consumables and Reagents, Instruments, Software, and Services
    2. Technology:Quantitative PCR, Digital PCR
    3. Application:Clinical Diagnostics, Life Science Research, Industrial Applications, Other Applications
    4. End-Use:Academic and Research Institutes, Pharmaceutical and Biotechnology, Clinical Diagnostics Labs and Hospitals, Other End Users

    Conclusion: Anticipating a Flourishing Future

    With a blend of historical foundations and futuristic trends, the PCR and real-time PCR testing market is poised for continuous growth. From personalized medicine to advanced diagnostics, the industry’s focus on innovation ensures its relevance in addressing evolving healthcare needs. As the market expands, the diverse applications of PCR technology underscore its pivotal role in shaping the landscape of modern diagnostics and research.

    Request A Sample Of The Global PCR And Realtime PCR Testing Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=2841&type=smp

  • What Is The Forecast Growth Rate For The Respiratory Monitoring Devices Market?

    What Is The Forecast Growth Rate For The Respiratory Monitoring Devices Market?

    The Business Research Company’s market reports offer an in-depth analysis on the market’s growth potential, major drivers, key trends and more.

    Market Growth and Projections
    The respiratory monitoring devices market has witnessed rapid growth in recent years, with a substantial increase in its market size. In 2023, the market size was $1.5 billion, and it is expected to reach $1.67 billion in 2024, exhibiting a compound annual growth rate (CAGR) of 11.0%. Looking ahead, the market is poised for continued expansion, projected to grow to $2.39 billion in 2028 at a CAGR of 9.5%. This growth is attributed to various factors, including respiratory health awareness, chronic diseases, remote patient monitoring, wearable technology, and technological advancements.

    Driving Forces Behind Market Growth

    Rising Incidence of Chronic Respiratory Diseases
    The surge in chronic respiratory diseases, such as asthma, bronchitis, and pneumonia, is a significant driving force for the respiratory monitoring devices market. The prevalence of these conditions, often resulting from bacterial and viral infections, underscores the critical need for effective monitoring tools. For instance, in 2021, the Centers for Disease Control and Prevention reported 142,342 deaths in the U.S. due to chronic lower respiratory diseases. Similarly, in Australia, 30% of the population, approximately 7.5 million people, have been diagnosed with chronic respiratory diseases.

    Essential Devices for Monitoring
    Respiratory monitoring devices, including spirometers and pulse oximeters, play a pivotal role in monitoring vital respiratory parameters. Key players in the market include Covidien LLC, GE Healthcare Inc., Philips Healthcare, ResMed Corp., Siemens Healthcare GmbH, and others. These companies contribute to the development and distribution of essential monitoring devices to address the growing demand.

    Innovations in Respiratory Monitoring

    Innovative Solutions for Improved Respiratory Care
    Major companies operating in the respiratory monitoring devices market are actively focusing on innovation to enhance their product offerings. One notable example is the HeroTracker Sense, introduced by AptarGroup, Inc. This device, designed as a respiratory monitoring tool, transforms a standard metered dose inhaler (pMDI) into a smart, connected healthcare device. The HeroTracker Sense not only helps patients with asthma and chronic obstructive pulmonary disease (COPD) adhere to their medication regimens but also collects healthcare analytics, enabling better care delivery by healthcare providers.

    Read More On The Respiratory Monitoring Devices Market Report 2024 – https://www.thebusinessresearchcompany.com/report/respiratory-monitoring-devices-global-market-report

    Strategic Moves and Acquisitions

    Senzime Ab Enhances Product Portfolio
    In June 2022, Senzime AB, a U.S.-based manufacturer of patient monitoring systems, acquired Respiratory Motion for an initial cash payment of $19 million. This strategic acquisition is poised to expand Senzime’s product portfolio in the monitoring devices market, strengthening the company’s capabilities. Respiratory Motion, a U.S.-based respiratory medical device manufacturer, adds valuable assets to Senzime’s offerings.

    Market Segmentation
    The respiratory monitoring devices market is segmented based on various criteria, providing a comprehensive understanding of its dynamics.

    Market Segmentation:

    1. By Type:
      • Capnographs
      • Gas Analyzers
      • Pulse Oximeters
      • Peak Flow Meters
      • Spirometers
      • Polysomnographs
      • Others Types
    2. By Application:
      • Chronic Obstructive Pulmonary Disease (COPD)
      • Infectious Diseases
      • Asthma
      • Other Applications
    3. By End-User:
      • Laboratories
      • Hospitals
      • Home Use

    Geographical Insights
    In 2023, Asia-Pacific emerged as the largest region in the respiratory monitoring devices market, reflecting the global nature of the industry and the diverse healthcare landscape.

    In conclusion, the respiratory monitoring devices market is experiencing robust growth driven by factors such as the rising incidence of chronic respiratory diseases, technological innovations, and strategic acquisitions. With ongoing advancements in connected devices, data analytics, and artificial intelligence, the future of respiratory monitoring holds promising opportunities for improved patient care and enhanced healthcare outcomes.

    Request for A Sample Of The Global Respiratory Monitoring Devices Market Report:
    https://www.thebusinessresearchcompany.com/sample_request?id=2845&type=smp

  • 5 Key Insights On The Electrosurgical Devices And Equipment Market 2024

    5 Key Insights On The Electrosurgical Devices And Equipment Market 2024

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    As per The Business Research Company’s Electrosurgical Devices And Equipment Global Market Report 2024, the electrosurgical devices and equipment market is expected to show significant growth in the forecast period.

    The electrosurgical devices and equipment market have witnessed robust growth, expanding from $9.7 billion in 2023 to $10.44 billion in 2024, at a commendable Compound Annual Growth Rate (CAGR) of 7.7%. Projections indicate further expansion, reaching $13.52 billion in 2028, with a CAGR of 6.7%. This growth is fueled by various factors, including an aging population, the surge in minimally invasive surgeries, increased surgical procedure volumes, and the advent of telemedicine and remote surgery.

    The Impact of Rising Chronic Diseases: A Driving Force Increasing Prevalence: The prevalence of chronic diseases has played a pivotal role in propelling the electrosurgical devices and equipment market. These devices are crucial in treating life-threatening conditions such as skin cancer, basal cell carcinomas, squamous cell carcinoma, wound surgery, skin surgery, non-cancerous moles, and dentistry. Alarming Statistics: According to the National Library of Medicine, individuals aged 50 and older with at least one chronic condition in the United States are projected to increase by 99.5%, from 71.522 million in 2020 to 142.66 million by 2050. Market Players: Major companies contributing to the market’s growth include Bovie Medical Corporation, Johnson & Johnson Private Limited, B. Braun Melsungen AG, Medtronic PLC, and others.

    View More On The Electrosurgical Devices And Equipment Market Report 2024 – https://www.thebusinessresearchcompany.com/report/electrosurgical-devices-and-equipment-global-market-report

    Electrosurgical Generator Technology: Paving the Way for Advanced Surgical Treatments Innovative Technological Advancements: Leading companies in the electrosurgical devices and equipment market are focusing on cutting-edge technology, particularly electrosurgical generators, to solidify their market position. Olympus Corporation’s Breakthrough: In June 2023, Olympus Corporation introduced the ESG-410 Electrosurgical Generator, equipped with PLASMA+ Technology. This system brings forth advancements in surgical treatments, featuring faster ignition, enhanced plasma stability, and versatile applicability in various surgical procedures without direct tissue contact. Segmentation of the Market: The electrosurgical devices and equipment market is segmented by product (Electrosurgery Generators, Electrosurgery Instruments & Accessories, Argon and Smoke Management Systems), application (General Surgery, Gynecology Surgery, Urologic Surgery, Orthopedic Surgery, Cardiovascular Surgery, Cosmetic Surgery, Neurosurgery), and end-user (Hospitals, Specialized Clinics, Ambulatory Surgery Centers).

    Major Trends Shaping the Future Energy-Efficient Devices: The market is witnessing a trend towards energy-efficient electrosurgical devices, contributing to sustainability efforts. Integration of Imaging Technologies: The incorporation of advanced imaging technologies is becoming prevalent, enhancing precision in surgical procedures. Smart and Connected Devices: Electrosurgical devices are evolving to become smarter and more connected, facilitating seamless integration with other healthcare systems. Enhanced Safety Features: Safety remains a paramount concern, leading to the incorporation of advanced safety features in electrosurgical devices.

    Regional Dominance: North America Takes the Lead Market Landscape: In 2023, North America emerged as the largest region in the global electrosurgical devices market, showcasing a strong foothold. Contributing Factors: Factors contributing to North America’s dominance include robust healthcare infrastructure, technological advancements, and a high prevalence of chronic diseases.

    Request A Sample Of The Global Electrosurgical Devices And Equipment Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=2522&type=smp

  • Implantable Infusion Pumps Market Report 2024: Market Size, Drivers, And Trends

    Implantable Infusion Pumps Market Report 2024: Market Size, Drivers, And Trends

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    The implantable infusion pumps market has experienced robust growth in recent years, witnessing a leap from $19.11 billion in 2023 to $20.13 billion in 2024, demonstrating a commendable Compound Annual Growth Rate (CAGR) of 5.3%. This growth surge is attributed to factors such as chronic disease management, an aging population, pain management, and regulatory approvals.

    Anticipated Growth: A Glimpse into the Future

    The market is poised for continued strength, with projections indicating a further rise to $25.3 billion in 2028, showcasing a compelling CAGR of 5.9%. The anticipated growth is fueled by the adoption of personalized medicine, remote patient monitoring, advancements in drug development, and the ongoing demand for effective chronic disease management. Notable trends in this forecast period include minimally invasive implantation, remote monitoring and programming, intrathecal pain management, and interdisciplinary collaboration.

    Growing Prevalence Of Chronic Diseases Fuels The Demand For Implantable Infusion Pumps Market

    • Rising Chronic Diseases: The increased prevalence of chronic pain, cancer, and diabetes is a key driver for the demand in implantable infusion pumps.
    • Efficient Pain Relief: Implantable infusion pumps are especially effective in conditions like chronic arachnoiditis, providing efficient pain relief with lower drug dosages.
    • Cancer Statistics: According to a report by the American Cancer Society, the US is expected to witness 1.9 million new cancer cases and 609,360 cancer deaths in 2022, emphasizing the critical role of implantable infusion pumps.
    • Market Leaders: Major companies leading this market include Medtronic PLC, Boston Scientific Corporation, Nevro Corp, and others.

    View More On The Implantable Infusion Pumps Market Report 2024 – https://www.thebusinessresearchcompany.com/report/implantable-infusion-pumps-global-market-report

    Product Innovations In The Implantable Infusion Pumps Market

    • Insulin Pumps: Major companies are focusing on developing innovative products like insulin pumps to cater to broader customer bases and increase revenue.
    • Medtronic’s Breakthrough: Medtronic’s MiniMed 780G System, with FDA approval, stands out for its unique features, including the ability to set the lowest glucose target and an infusion set that can be worn for up to 7 days.
    • Advanced Materials: Extended wear time is achieved through the use of advanced materials, minimizing insulin preservative loss and ensuring consistent insulin flow.

    Medtronic’s Strategic Acquisition: Advancing Insulin Delivery

    • Acquisition of Implanted Infusion Pump Technology: Medtronic’s acquisition of technology from Alfred E. Mann Foundation in September 2021 aims to enhance insulin delivery for individuals with type-1 diabetes.
    • Alfred E. Mann Foundation: This US-based scientific research foundation specializes in developing implantable infusion pumps and other medical devices.

    Market Segmentation for In-Depth Insights

    • By Type: Patient-Controlled Analgesia (PCA) Pumps, Enteral Pumps, Insulin Pumps, Elastomeric Pumps, Syringe Pumps, Other Types.
    • By Applications: Oncology, Pediatrics/Neonatology, Gastroenterology, Hematology, Diabetes, Other Applications.
    • By End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics.

    Regional Dominance: North America Takes the Lead

    • North America: Emerging as the largest region in the implantable infusion pumps market in 2023, reflecting the significant contribution of this region to the overall market.

    In conclusion, the implantable infusion pumps market is undergoing a remarkable transformation, fueled by a rising prevalence of chronic diseases, innovative product developments, strategic acquisitions, and a focus on personalized medicine. As technology continues to advance, interdisciplinary collaboration and the integration of remote monitoring are set to reshape the landscape, promising a future where implantable infusion pumps play a pivotal role in enhancing patient care and treatment outcomes.

    Request A Sample Of The Global Implantable Infusion Pumps Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3347&type=smp

  • Intravenous Infusion Pumps Market Growth Analysis Till 2033 By The Business Research Company

    Intravenous Infusion Pumps Market Growth Analysis Till 2033 By The Business Research Company

    The Business Research Company’s market reports offer an in-depth analysis on the market’s growth potential, major drivers, key trends and more.

    The intravenous infusion pumps market has demonstrated robust growth, escalating from $5.71 billion in 2023 to $6.15 billion in 2024, boasting a Compound Annual Growth Rate (CAGR) of 7.9%. This expansion is fueled by key factors such as advances in medical technology, an aging population, the rise of home healthcare services, and the expansion of hospitals and healthcare facilities, all conforming to regulatory standards.

    Future Projections: A Promising Outlook

    The market is poised for continued strength, with projections indicating a surge to $8.51 billion by 2028, driven by a CAGR of 8.5%. The anticipated growth is attributed to the increasing burden of chronic diseases, technological innovations, the rise of home infusion services, and the integration of telehealth and remote monitoring.

    Catalyst for Growth: Bleeding Disorders

    One significant driver for the intravenous infusion pumps market is the rising prevalence of bleeding disorders. These conditions, impairing the body’s clotting mechanisms, necessitate precise and controlled delivery of medications, a role expertly filled by intravenous infusion pumps.

    • Prevalence Data:The Australian Bleeding Disorders Registry reported 7,040 active patients in June 2021.
    • Impact:Bleeding disorders, including hereditary hemophilia A (HMA) and von Willebrand disease, contribute to the market’s growth.

    Industry Giants: Key Players

    Major companies shaping the intravenous infusion pumps market include B. Braun Melsungen AG, Baxter International Inc., Medtronic PLC, and several others. Their innovative products and strategic moves contribute significantly to market dynamics.

    • Market Leaders:Prominent companies like Becton Dickinson, Terumo Corporation, and Johnson & Johnson play pivotal roles.
    • Diverse Offerings:Companies such as Tandem Diabetes Care Inc. and Q-Core Medical Ltd. bring diverse products to the market.

    Read More On The Intravenous Infusion Pumps Market Report 2024 – https://www.thebusinessresearchcompany.com/report/intravenous-infusion-pumps-global-market-report

    Innovations Driving Market Evolution

    Companies are focusing on pioneering products to meet the evolving needs of consumers. Innovations like the Novum IQ syringe infusion pump showcase the commitment to enhancing patient care and safety.

    • Novum IQ Syringe Infusion Pump:Baxter International Inc.’s FDA-approved Novum IQ brings safety software and dosage error reduction solutions, enhancing infusion safety.
    • Technological Integration:Innovations underscore the infusion pump market’s commitment to integrating technology for enhanced efficiency and safety.

    Strategic Acquisitions: Fresenius Kabi’s Move

    In March 2022, Fresenius Kabi made a strategic acquisition by acquiring Ivenix for $240 million. This move underscores the importance of strategic partnerships and acquisitions in bolstering companies’ offerings and serving customer needs effectively.

    • Ivenix Acquisition:The acquisition of Ivenix positions Fresenius Kabi to enhance its infusion pump offerings.
    • Market Expansion:Strategic acquisitions contribute to the market’s evolution and growth.

    Market Segmentation for Precision Insights

    Understanding the market’s nuances requires a segmentation approach based on product types, applications, and end-users.

    • Product Segmentation:Volumetric, Syringe, Enteral, Ambulatory, IV Disposables, Other Products.
    • Application Segmentation:Chemotherapy, Diabetes, Gastroenterology, Analgesia/Pain Management, Pediatrics/Neonatology, Hematology, Other Applications.
    • End-User Segmentation:Hospitals, Ambulatory Surgical Centers, Cancer Treatment Centers, Specialty Clinics, Other End Users.

    Regional Dominance: North America at the Helm

    In 2023, North America emerged as the largest region in the intravenous infusion pumps market, emphasizing the region’s pivotal role in steering market dynamics.

    • North America’s Influence:The region’s prominence signifies its impact on the intravenous infusion pumps market.

    Future Trends: Charting the Course Ahead

    Anticipated trends in the coming years include the integration of smart infusion pumps, the adoption of wireless and remote monitoring, the rise of home infusion therapy, and the growing importance of precision medicine and personalized infusion.

    • Smart Infusion Pumps:Technological advancements in infusion pumps for smarter and more efficient delivery.
    • Wireless and Remote Monitoring:Embracing connectivity for real-time monitoring and enhanced patient care.
    • Home Infusion Therapy:A rising trend in providing healthcare services within the comfort of patients’ homes.
    • Precision Medicine:Tailoring infusion therapies to individual patient needs for optimal outcomes.

    Conclusion: Navigating Healthcare’s Intricate Network

    As the intravenous infusion pumps market continues its upward trajectory, fueled by technological innovations, strategic acquisitions, and a focus on addressing critical healthcare needs, the future holds promising developments. Charting the course ahead involves not only meeting current demands but also anticipating and adapting to evolving trends in healthcare delivery and patient care.

    Request for A Sample Of The Global Intravenous Infusion Pumps Market Report:
    https://www.thebusinessresearchcompany.com/sample_request?id=3305&type=smp

  • Global Cervical Cancer Diagnostics Market Key Insights 2024-2033

    Global Cervical Cancer Diagnostics Market Key Insights 2024-2033

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    According to The Business Research Company’s Cervical Cancer Diagnostics Global Market Report 2024, the cervical cancer diagnostics market is expected to show promising growth in the forecast period.

    The cervical cancer diagnostics market has witnessed robust growth in recent years, reaching $8.89 billion in 2023 and expected to grow to $9.52 billion in 2024 at a Compound Annual Growth Rate (CAGR) of 7.0%. Looking ahead, the market is poised for continued expansion, with a projected size of $11.95 billion in 2028, reflecting a CAGR of 5.8%. Key drivers include increased awareness and screening programs, HPV vaccination, technological advancements, and an aging population.

    Factors Driving Historic Growth

    • Increased awareness and screening programs
    • HPV vaccination
    • Technological advancements
    • Aging population

    Emerging Trends in the Forecast Period

    • HPV testing
    • Liquid-based cytology
    • Automation and digital pathology
    • Screen-and-treat programs

    Addressing the Rising Prevalence of Cervical Cancer

    The prevalence of cervical cancer is on the rise, necessitating a proactive response through advancements in diagnostic tools and technologies. Cervical cancer begins in the cells of the cervix, and early detection is crucial for successful treatment. According to Cancer.net, an estimated 13,960 women in the United States will be diagnosed with invasive cervical cancer, highlighting the urgent need for effective diagnostic solutions.

    Key Players in the Cervical Cancer Diagnostics Market

    Several major companies play a pivotal role in the cervical cancer diagnostics market. Key industry players include Abbott Laboratories, Becton Dickinson and Company (BD), Roche Ltd., Hologic Inc., QIAGEN N.V., Quest Diagnostics Incorporated, Siemens Healthineers AG, and more. The market is characterized by diverse companies contributing to the development and accessibility of cervical cancer diagnostic tools.

    View More On The Cervical Cancer Diagnostics Market Report 2024 – https://www.thebusinessresearchcompany.com/report/cervical-cancer-diagnostics-global-market-report

    Innovations In Cervical Cancer Diagnostics, The Introduction Of Genius Digital Diagnostics System

    Technological Innovations Driving Progress

    Innovation in cervical cancer diagnostics is a key focus for major companies in the market. The introduction of cutting-edge products, such as the Genius Digital Diagnostics System, showcases the commitment of companies to enhance diagnostic capabilities and increase profitability.

    Genius Digital Diagnostics System

    • Healthcare technology system
    • Designed for diagnostic and clinical applications
    • Utilizes advanced volumetric imaging technology
    • Incorporates deep learning-based artificial intelligence (AI)
    • Detects pre-cancerous lesions and cervical cancer cells

    Hologic’s Strategic Launch

    In November 2021, Hologic, Inc., a prominent US-based health technology company, launched the Genius Digital Diagnostics System in Europe. This system represents the next generation of cervical cancer screening, leveraging advanced imaging technology and AI to improve the accuracy of detecting pre-cancerous lesions and cervical cancer cells in females.

    BD’s Acquisition Of Cytognos Advancing Chronic Disease Management Through Immune Diagnostics

    BD’s Strategic Move

    In February 2022, BD (Becton, Dickinson, and Company) executed a significant acquisition by acquiring Cytognos, a Spain-based company specializing in clinical flow cytometry solutions. This undisclosed deal strengthens BD’s commitment to chronic disease management, expanding its diagnostic portfolio, immune assessment tests, and informatics capabilities.

    Advancing Chronic Disease Management

    • Deepening understanding of the immune system
    • Enhancing immune response assessment
    • Focusing on Minimal Residual Disease (MRD)
    • Strengthening immune diagnostics capabilities

    Market Segmentation and Regional Dynamics

    Segmentation Overview

    The cervical cancer diagnostics market is segmented based on diagnostic tests, age groups, and end-users.

    1. Diagnostic Test:
      • Pap Smear Test
      • HPV Test
      • Colposcopy
      • Biopsy and Endocervical Curettage
      • Other Diagnostic Tests
    2. Age Group:
      • Below 21
      • Age between 21 to 29
      • Age between 30 to 65
      • Above 65
    3. End User:
      • Hospitals
      • Specialty Clinics
      • Cancer and Radiation Therapy Centers
      • Diagnostic Centers

    Regional Insights

    • North America emerged as the largest region in the cervical cancer diagnostics market in 2023, reflecting the region’s commitment to advanced healthcare and diagnostics.

    In conclusion, the cervical cancer diagnostics market is experiencing substantial growth, driven by factors such as the rising prevalence of cervical cancer, technological innovations, and strategic acquisitions by major players. As the market continues to evolve, these advancements promise to enhance early detection, accurate diagnosis, and successful treatment, ultimately contributing to better outcomes for individuals affected by cervical cancer.

    Request A Sample Of The Global Cervical Cancer Diagnostics Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3285&type=smp

  • Clinical Oncology Next Generation Sequencing Market Forecast 2024: Forecast Market Size, Drivers And Key Segments

    Clinical Oncology Next Generation Sequencing Market Forecast 2024: Forecast Market Size, Drivers And Key Segments

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    The clinical oncology next-generation sequencing market has experienced rapid expansion in recent years, with a substantial increase from $0.45 billion in 2023 to $0.52 billion in 2024, marking an impressive Compound Annual Growth Rate (CAGR) of 15.5%. This growth in the historic period is attributed to advancements in genomic research, cancer biomarker discovery, technological progress, and regulatory approvals.

    Future Projections

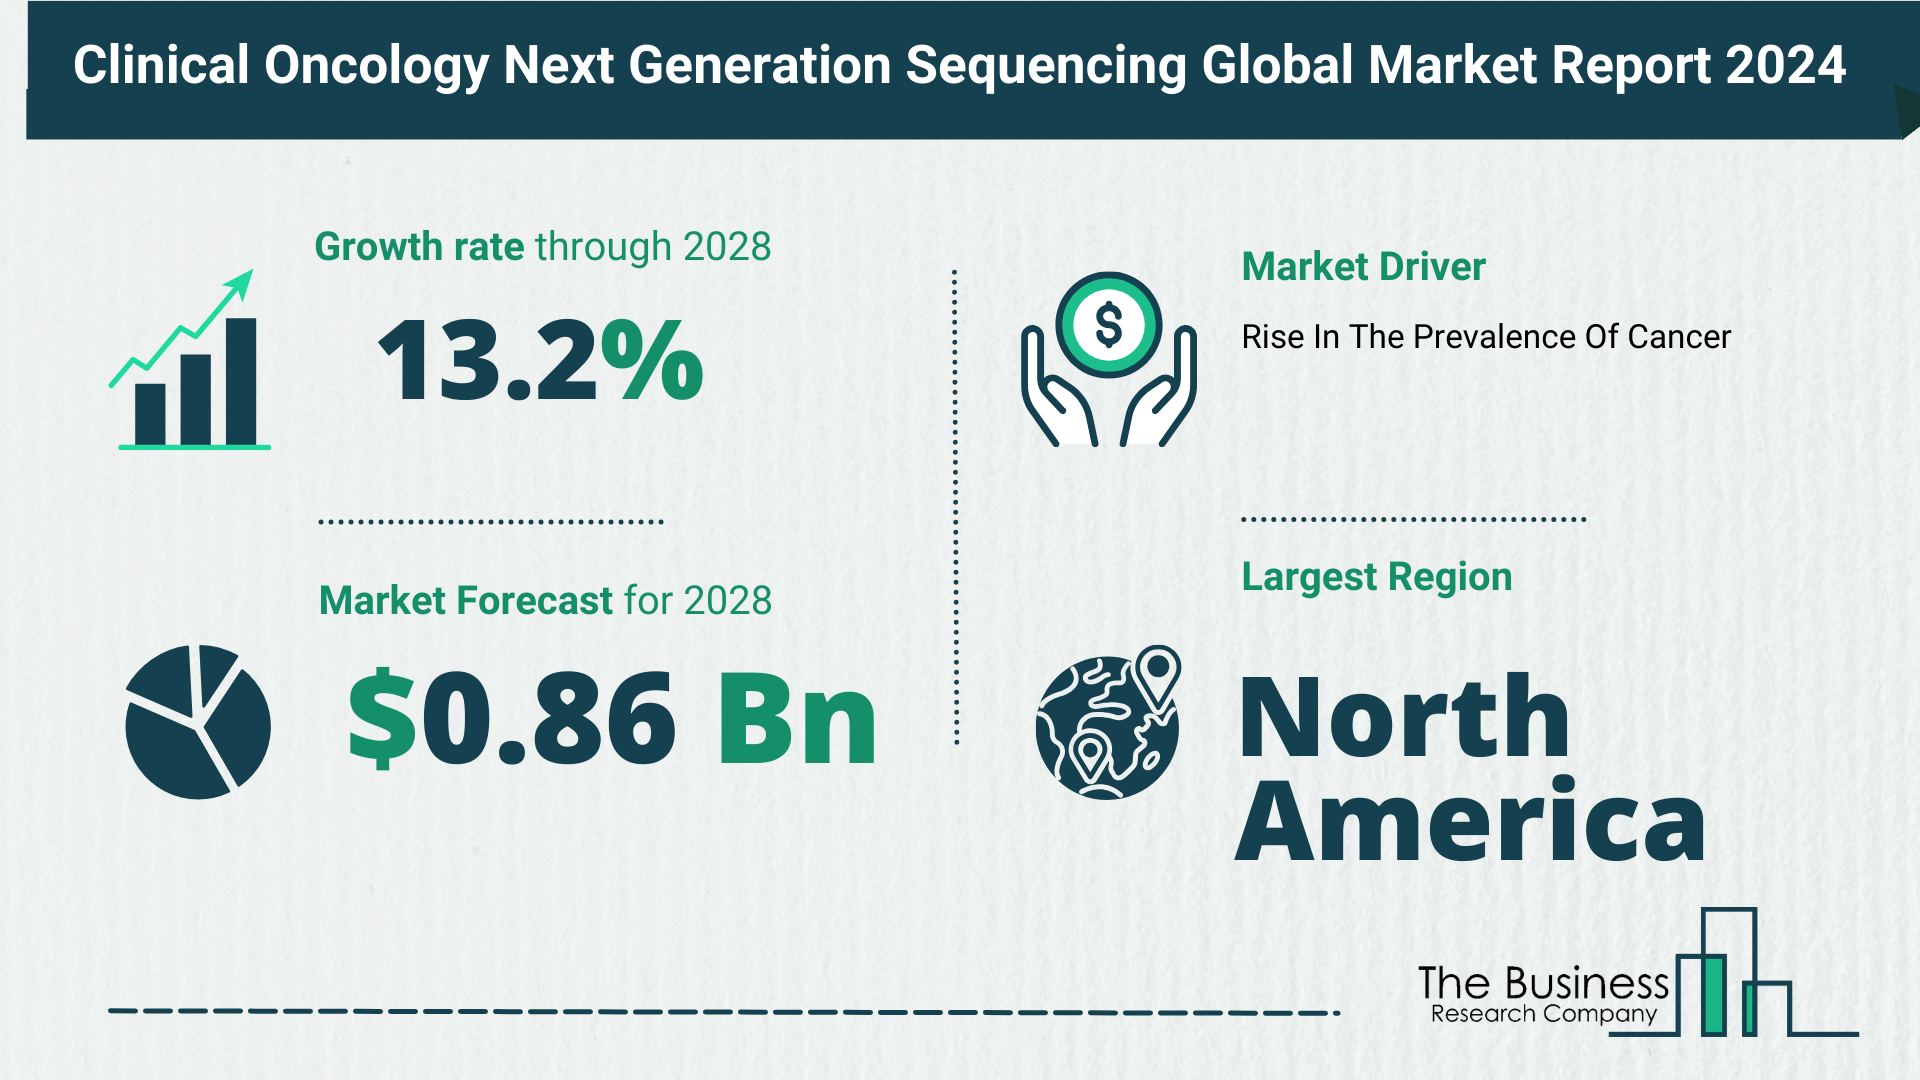
    Anticipated to sustain its momentum, the market is poised for continued growth. Forecasts indicate an expansion to $0.86 billion in 2028, with a CAGR of 13.2%. The projected surge in the clinical oncology next-generation sequencing market in the forecast period can be linked to factors like the growing incidence of cancer, precision medicine, advancements in immuno-oncology, and the rise of liquid biopsies.

    Cancer Prevalence as a Catalyst for Growth

    Rising Cancer Cases

    The escalating prevalence of cancer emerges as a driving force behind the growth of the clinical oncology next-generation sequencing market. Defined by the uncontrolled growth and spread of abnormal cells, cancer necessitates advanced technologies like Next-Generation Sequencing (NGS) to identify new and rare mutations. In 2021, the American Cancer Society estimated 1.9 million new cancer cases and 608,570 deaths in the United States alone, underscoring the urgency for robust diagnostic tools.

    Role of NGS

    NGS plays a pivotal role in understanding the molecular underpinnings of individual tumors, enabling a more targeted and personalized approach to cancer treatment. As the prevalence of cancer continues to rise globally, the demand for clinical oncology next-generation sequencing solutions is expected to surge.

    View More On The Clinical Oncology Next Generation Sequencing Market Report 2024 – https://www.thebusinessresearchcompany.com/report/clinical-oncology-next-generation-sequencing-global-market-report

    Innovative Products Driving Profitability

    Strategic Innovations

    Major players in the market, including Thermo Fisher Scientific, Illumina, and Roche, are actively innovating to introduce cutting-edge products. For example, Roche’s BenchMark ULTRA PLUS system is a testament to the industry’s commitment to innovation. Launched in June 2022, this system enhances the accuracy and efficiency of diagnostic tests, contributing to improved patient care.

    Product Impact on Profitability

    Innovative products not only contribute to scientific advancements but also play a significant role in boosting profitability. The BenchMark ULTRA PLUS System, by streamlining diagnostic tests and delivering rapid and accurate results, exemplifies the synergy between technological innovation and market profitability.

    Strategic Acquisitions for Market Expansion

    Agilent’s Strategic Move

    Agilent Technologies, a key player in life sciences technology, made a strategic move in April 2021 by acquiring Resolution Bioscience. This undisclosed acquisition aimed to bolster Agilent’s capabilities in next-generation sequencing for cancer diagnostics. Resolution Bioscience, known for its precision oncology solutions, positions Agilent at the forefront of NGS-based cancer diagnostics.

    Market Segmentation and Regional Dominance

    Segmentation Overview

    The clinical oncology next-generation sequencing market is segmented based on technology, application, and end-user. Key segments include Ion Semiconductor Sequencing, Pyro-Sequencing, Synthesis Sequencing, Real Time Sequencing, Ligation Sequencing, Reversible Dye Termination Sequencing, Nano-Pore Sequencing, with applications spanning Screening, Companion Diagnostics, and Other Diagnostics. End-users range from Hospital Laboratories and Clinical Research Organizations to Diagnostic Laboratories.

    Regional Dominance

    North America emerged as the largest region in the clinical oncology next-generation sequencing market in 2023. This regional dominance reflects the concentrated efforts and investments in advanced healthcare technologies and research initiatives.

    Conclusion

    In conclusion, the clinical oncology next-generation sequencing market’s dynamic growth trajectory underscores its pivotal role in advancing cancer diagnostics and treatment. With rising cancer incidence, strategic innovations, and regional dominance in North America, the market is poised for further expansion. As technological breakthroughs continue to shape the landscape, the integration of NGS in precision medicine and immuno-oncology holds the promise of transforming cancer care on a global scale.

    Request A Sample Of The Global Clinical Oncology Next Generation Sequencing Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3344&type=smp

  • Key Trends And Drivers In The Breast Cancer Diagnostics Market 2024

    Key Trends And Drivers In The Breast Cancer Diagnostics Market 2024

    The Business Research Company’s market reports offer an in-depth analysis on the market’s growth potential, major drivers, key trends and more.

    The breast cancer diagnostics market has witnessed robust growth, driven by various factors such as awareness campaigns, technological advancements, and a multidisciplinary approach. As we delve into the details, it’s evident that the market is poised for further expansion, reaching $4.8 billion in 2024 at a CAGR of 8.7% and projecting an even more impressive growth to $6.47 billion in 2028 at a CAGR of 7.7%.

    Factors Fueling Historic Growth

    • Awareness and Screening Campaigns: Public awareness initiatives have played a pivotal role in promoting early detection and screening.
    • Mammography Screening: The prevalence of mammography screening has contributed significantly to the historic growth.
    • Technological Advancements: Continuous advancements in diagnostic technologies have enhanced accuracy and efficiency.
    • Genetic Testing: The integration of genetic testing has provided crucial insights into the genetic basis of breast cancer.
    • Multidisciplinary Approach: A collaborative approach involving multiple disciplines has improved overall diagnostics and treatment strategies.

    The Role of Government Funding
    Government Initiatives and Funding: A Path to Improved Healthcare

    • Financial Support: Governments worldwide allocate substantial funds to support breast cancer research, prevention, and treatment.
    • Program Implementation: Various programs aim to raise awareness, promote early detection, and provide financial assistance to underserved communities.
    • Australian Example: The Australian Government allocated $40.7 million in its 2022-23 budget, focusing on enhancing accessibility and timely referrals, with $9.7 million specifically earmarked for breast cancer screening.

    Market Players Driving Innovation
    Innovations in Breast Cancer Diagnostics Market

    • Key Companies: Major players like Abbott Laboratories, Hologic Inc., and Thermo Fisher Scientific Inc. are driving innovation in breast cancer diagnostics.
    • AI-based Diagnosis: Artificial intelligence is revolutionizing breast cancer diagnosis, offering high accuracy and efficiency.
    • Digistain’s Breakthrough: In December 2022, Digistain, a UK-based biotech company, launched an AI breast cancer diagnostic tool with over 99% accuracy, reducing waiting times and cutting costs significantly.

    Read More On The Breast Cancer Diagnostics Market Report 2024 – https://www.thebusinessresearchcompany.com/report/breast-cancer-diagnostics-global-market-report

    Strategic Moves: Hologic’s Acquisition
    Strategic Acquisition – Hologic Expands Breast Health Solutions With Somatex

    • Acquisition Details: In January 2021, Hologic acquired Somatex Medical for $64 million, reinforcing its commitment to comprehensive breast health solutions.
    • Somatex’s Contribution: Somatex, a German-based provider of breast cancer diagnostic services, adds value to Hologic’s offerings.

    Market Segmentation Overview
    Understanding the Breast Cancer Diagnostics Market

    1. By Type:
      • Imaging
      • Biopsy
      • Genomic Tests
      • Blood Tests
      • Other Types
    2. By Technology:
      • Fluorescent In Situ Hybridization (FISH)
      • Comparative Genomic Hybridization (CGH)
      • Immunohistochemical (IHC)
      • Other Technologies
    3. By Cancer Type:
      • BRCA Breast Cancer
      • ER & PR Breast Cancer
      • HER 2 Breast Cancer
      • EGFR Mutation Test Breast Cancer
      • Other Cancer Types
    4. By Diagnostic Type:
      • Ionizing Breast Imaging Technologies
      • Non-ionizing Imaging Technologies
    5. By End Users:
      • Hospitals and Clinics
      • Cancer Research Centers
      • Diagnostic Laboratories
      • Ambulatory Surgical Centers

    Regional Dominance: North America Leads the Way

    • Largest Market: In 2023, North America emerged as the largest region in the breast cancer diagnostics market, underscoring the region’s commitment to advancements in healthcare.

    Conclusion
    The breast cancer diagnostics market is not just witnessing growth; it’s evolving through innovations, government support, and strategic acquisitions. As we move forward, the focus on personalized medicine, liquid biopsies, AI, and machine learning promises to reshape the landscape, providing hope for improved diagnostics and outcomes in the fight against breast cancer. With a strong foundation laid in the historic period, the forecasted growth reflects a promising trajectory, marking a significant step towards a future with enhanced breast cancer diagnostics and treatment solutions.

    Request for A Sample Of The Global Breast Cancer Diagnostics Market Report:
    https://www.thebusinessresearchcompany.com/sample_request?id=3284&type=smp

  • Top 5 Insights From The X-Ray Systems Devices And Equipment Market Report 2024

    Top 5 Insights From The X-Ray Systems Devices And Equipment Market Report 2024

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    According to The Business Research Company’s X-Ray Systems Devices And Equipment Global Market Report 2024, the X-ray systems devices and equipment market is expected to show promising growth in the forecast period.

    The x-ray systems devices and equipment market has witnessed robust growth in recent years. In 2023, the market size reached $16.98 billion, experiencing a significant surge from which it is projected to grow to $18.38 billion in 2024 at a compound annual growth rate (CAGR) of 8.2%. This growth is primarily attributed to factors such as medical diagnostics, population growth, an aging population, and the emphasis on preventive and routine healthcare.

    Projected Growth and Key Drivers in the Coming Years

    1. The market is expected to continue its upward trajectory, reaching $24.44 billion in 2028, showcasing a CAGR of 7.4%.
    2. The forecasted growth is fueled by digital transformation, specialized applications, population health management, and advancements in radiation safety.
    3. Emerging trends include 3D and cone-beam CT imaging, point-of-care x-ray, AI-enhanced imaging, and remote/mobile imaging. 

    View More On The X-Ray Systems Devices And Equipment Market Report 2024 – https://www.thebusinessresearchcompany.com/report/x-ray-systems-devices-and-equipment-global-market-report

    Growth In X-Ray Systems Market Driven By Increasing Demand For Diagnostic Imaging Procedures

    1. Diagnostic Imaging Procedures and Market Demand
      • Diagnostic imaging procedures play a pivotal role in diagnosing diseases, monitoring treatment effectiveness, and planning surgeries.
      • In England alone, 40.3 million imaging procedures were reported between September 2020 and August 2021.
      • X-ray systems are crucial in identifying anomalies and aiding accurate diagnoses.
    2. Key Players in the Market
      • Major companies dominating the market include Siemens Healthcare, Carestream Health, Philips Healthcare, GE Healthcare, and others.
      • Their expertise contributes significantly to the growth and innovation within the x-ray systems market.

    NCRP’s Radiation Vital Sign And Innovations In Reducing Medical Radiation Exposure

    1. NCRP’s Initiative for Reducing Radiation Exposure
      • In response to the FDA’s initiative, the National Council on Radiation Protection and Measurements (NCRP) recommends minimizing medical radiation exposure.
      • The introduction of a radiation vital sign risk score enhances patient safety and quality of care.
    2. Innovations in Reducing Radiation Exposure
      • ControlRad, a medical technology company, observed a 57% reduction in radiation exposure to the thyroid of the first cardiologist and a 49% reduction for the secondary cardiologist using controlled procedures.
      • FDA clearance for ControlRad Select, available through Boston Scientific, facilitates retrofits on existing Siemens imaging systems.

    Canon Medical Systems Expands European Presence With Acquisition Of Nordisk Røntgen Teknik (NRT)

    1. Strategic Acquisition by Canon Medical Systems
      • In March 2022, Canon Medical Systems acquired Nordisk Røntgen Teknik (NRT), a Danish medical equipment manufacturer, strengthening its position in the European market.
      • The acquisition provides access to advanced radiographic solutions developed by NRT.

    Segmentation and Market Dynamics

    1. Market Segmentation
      • The x-ray systems market is segmented by type (portable, stationary), product type (CT, mobile x-ray, C-arm, dental x-ray, mammography, and others), image type (2D, 3D, 4D), technology (analog, digital), and application (cardiovascular, respiratory, mammography, dental, orthopedics, and others).
    2. Regional Dominance
      • Western Europe emerged as the largest region in the global x-ray devices and equipment market in 2023, showcasing the region’s significance in driving market growth.

    Conclusion: A Radiant Future for X-Ray Systems Market
    The x-ray systems devices and equipment market’s remarkable growth, driven by increasing demand for diagnostic imaging procedures, technological innovations, and strategic acquisitions, presents a promising outlook. As the market continues to evolve, embracing digital transformation, specialized applications, and advancements in radiation safety, it is poised for sustained growth and innovation in the coming years. The key players and market dynamics outlined signify a vibrant and dynamic landscape, shaping the future of diagnostic imaging technologies.

    Request A Sample Of The Global X-Ray Systems Devices And Equipment Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3810&type=smp