Category: Utilities

  • Grid Cybersecurity Market Size Growth: From $10.43 Billion In 2026 To $18.02 Billion By 2030

    Grid Cybersecurity Market Size Growth: From $10.43 Billion In 2026 To $18.02 Billion By 2030

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Grid Cybersecurity Market Growth Analysis: How Will Revenue Trend Over The Forecast Period?

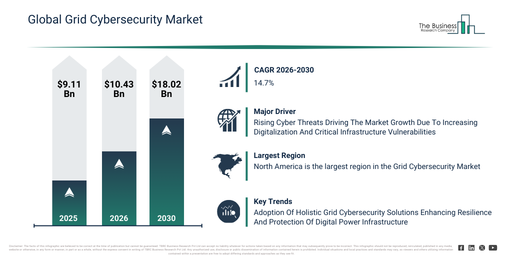
    The grid cybersecurity market has observed rapid expansion in recent years. This market is forecast to increase from $9.11 billion in 2025 to $10.43 billion in 2026, achieving a compound annual growth rate (CAGR) of 14.4%. Throughout the past, this growth has been driven by the increasing digitization of power grids, the early adoption of smart grid technologies, a rise in cyberattack incidents on critical infrastructure, the expansion of network-connected grid assets, and the development of cybersecurity standards.

    The grid cybersecurity market is anticipated to experience substantial expansion over the coming years. Its valuation is projected to reach $18.02 billion by 2030, demonstrating a compound annual growth rate (CAGR) of 14.7%. This growth during the forecast period is attributable to several factors, including escalating investments in grid resilience, the increasing adoption of cloud-based grid operational strategies, heightened regulatory demands concerning infrastructure security, the expanding number of connected energy assets, and a greater emphasis on zero-trust security frameworks. Key trends anticipated within this period involve the heightened deployment of sophisticated grid threat detection systems, a surge in the adoption of AI-driven cybersecurity analytics, the expanding integration of real-time grid security monitoring, the proliferation of cloud-based security platforms, and an intensified focus on both regulatory adherence and overall resilience.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33134&type=smp&name=Grid%20Cybersecurity%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Grid Cybersecurity Market Expansion Drivers: What’s Shaping Future Growth?

    The expanding occurrence of cyber threats is projected to stimulate the future growth of the grid cybersecurity market. Cyber threats are defined as risks stemming from attacks or exploits that jeopardize the security, integrity, or accessibility of digital systems and information. These threats are escalating due to the rapid proliferation of digital technologies and online connectivity, which, in turn, create more potential attack surfaces for malicious actors. Grid cybersecurity is instrumental in mitigating cyber threats by shielding power grids from unauthorized access, detecting malicious activities in real time, and ensuring the integrity, availability, and resilience of crucial energy infrastructure. A pertinent illustration of this trend is observed in October 2025, when, as per the Australian Signals Directorate, an Australia-based government agency, its Australian Cyber Security Centre (ACSC) received over 42,500 calls to the Australian Cyber Security Hotline in FY2024–25, representing a 16% rise from the previous year. Therefore, the rise in cyber threats is a key factor propelling the expansion of the grid cybersecurity market.

    Grid Cybersecurity Market Segment Analysis Spotlighting Growth Areas

    The grid cybersecurity market covered in this report is segmented –

    1) By Component: Solutions; Services

    2) By Security Type: Network Security; Endpoint Security; Application Security; Cloud Security; Other Security Types

    3) By Deployment Mode: On-Premises; Cloud

    4) By Application: Smart Grid; Power Generation; Transmission; Distribution; Other Applications

    5) By End User: Utilities; Energy And Power; Industrial; Commercial; Other End Users

    Subsegments:

    1) By Solutions: Network Security Solutions; Endpoint Security Solutions; Application Security Solutions; Data Protection And Encryption Solutions; Identity And Access Management Solutions

    2) By Services: Consulting And Risk Assessment Services; System Integration And Deployment Services; Managed Security Services; Monitoring And Incident Response Services; Support And Maintenance Services

    Grid Cybersecurity Market Strategic Trends: What Defines The Next Growth Phase?

    Leading companies operating within the grid cybersecurity market are concentrating on developing advanced solutions, such as comprehensive cybersecurity approaches, to protect digital grids, prevent cyberattacks, and ensure continuous, reliable energy delivery. A comprehensive cybersecurity solution is an all-encompassing strategy that safeguards the power grid’s IT, OT, and communication networks from cyberattacks while ensuring continuous, resilient operations. For instance, in October 2024, Parsons Corporation, a US-based technology company, introduced a cyberzcape tracker, specifically designed for critical infrastructure like power grids. This agentless operation avoids disrupting always-on grid systems, employs modular cloud-based SaaS architecture to reduce tool sprawl, and possesses proactive features including automated patching, vulnerability scoring, and compliance support for OT/BES assets. Utilities gain enhanced resilience against sophisticated attacks, streamlined security processes, cost savings, and seamless integration with modernization tools such as DERMS and NMS, contributing to reliable energy delivery and national security alignment.

    Grid Cybersecurity Market Key Players Shaping Industry Direction

    Major companies operating in the grid cybersecurity market are Siemens AG, Hitachi Ltd., Lockheed Martin Corporation, Accenture plc, IBM Corporation, Cisco Systems Inc., Intel Corporation, General Electric, Schneider Electric SE, Mitsubishi Electric Corporation, Honeywell International Inc., ABB Ltd., toshiba corporation, Eaton Corporation, Leidos Holdings Inc., Palo Alto Networks, Fortinet Inc., Landis+Gyr Group AG, Schweitzer Engineering Laboratories Inc., Darktrace plc, Dragos Inc., AlertEnterprise Inc.

    View The Full Grid Cybersecurity Market Report:

    https://thebusinessresearchcompany.com/report/grid-cybersecurity-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Grid Cybersecurity Market Regional Analysis: Which Region Leads By Revenue?

    North America was the largest region in the grid cybersecurity market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the grid cybersecurity market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Grid Capacity Map Platform Market Size In 2026 And Beyond: Understanding Future Growth Potential

    Grid Capacity Map Platform Market Size In 2026 And Beyond: Understanding Future Growth Potential

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Grid Capacity Map Platform Market Size, Value And Growth Trajectory Through 2030

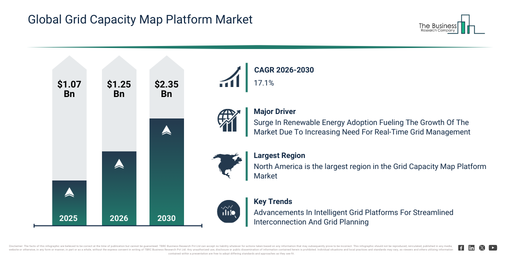
    Recent years have seen substantial growth in the grid capacity map platform market size. It will grow from $1.07 billion in 2025 to $1.25 billion in 2026 at a compound annual growth rate (CAGR) of 16.9%. Several factors contributed to this historical growth, including the expansion of transmission and distribution networks, intensifying grid congestion challenges, the early adoption of digital tools for grid planning, the rise of renewable energy connections, and an increasing need for grid transparency.

    The grid capacity map platform market is projected for significant expansion in the coming years. It is anticipated to reach $2.35 billion by 2030, exhibiting a compound annual growth rate (CAGR) of 17.1%. This growth during the forecast period is fueled by factors such as enhanced renewable energy integration, expanded deployment of electric vehicle charging infrastructure, increased investments in grid modernization, the proliferation of data-driven infrastructure planning, and the escalating demand for expedited connection approvals. Key trends anticipated for this period encompass the wider adoption of real-time grid capacity visualization, greater utilization of data-driven grid planning instruments, the increasing incorporation of load forecasting features, the broadening of cloud-based capacity mapping solutions, and a heightened emphasis on identifying network bottlenecks.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33131&type=smp&name=Grid%20Capacity%20Map%20Platform%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Grid Capacity Map Platform Market Growth Factors: What’s Supporting Expansion?

    The expanding use of renewable energy sources is anticipated to fuel the expansion of the grid capacity map platform market in the future. These sources, such as sunlight, wind, water, and biomass, are natural energy supplies that are continuously replenished. Their increase is driven by worldwide initiatives to lower carbon emissions, as governments and corporations invest in clean power to address climate change and transition away from fossil fuels. This growth in renewables necessitates a grid capacity map platform because handling fluctuating inputs such as solar and wind power demands precise, real-time understanding of the grid’s ability to distribute electricity effectively and prevent overloads. As an illustration, in October 2024, the International Energy Agency, an intergovernmental body based in France, reported that globally, more than 5,500 gigawatts (GW) of new renewable energy capacity are projected to be installed between 2024 and 2030, with China expected to account for almost 60% of these worldwide installations during this timeframe. Consequently, the greater adoption of renewable energy sources is propelling the growth of the grid capacity map platform market. The increasing prevalence of electric vehicles is projected to boost the expansion of the grid capacity map platform market in the coming years. These automobiles operate, either fully or in part, on electric motors drawing power from rechargeable batteries, rather than solely on conventional internal combustion engines. The increase in electric vehicles stems from heightened environmental concerns, leading both consumers and governments to favor cleaner transport options to lower greenhouse gas emissions and air pollution. The growing number of electric vehicles escalates the demand for grid capacity map platforms, given that the substantial and variable electricity requirements for EV charging necessitate real-time oversight to guarantee effective power distribution and prevent grid overloads. For instance, in May 2025, the International Energy Agency, a France-based intergovernmental organization, reported that global electric car sales surpassed 17 million in 2024, representing a growth of over 25% and an increase of 3.5 million vehicles sold compared to 2023. Thus, the growing adoption of electric vehicles is propelling the expansion of the grid capacity map platform market.

    Grid Capacity Map Platform Market Breakdown By Product Type And Application

    The grid capacity map platform market covered in this report is segmented –

    1) By Component: Software; Services

    2) By Deployment Mode: Cloud Based; On Premises

    3) By Application: Utility Management; Renewable Integration; Grid Planning; Real-Time Monitoring; Other Applications

    4) By End User: Utilities; Government Agencies; Independent Power Producers; Industrial; Commercial; Other End Users

    Subsegments:

    1) By Software: Mapping Platforms; Data Analytics Tools; Visualization Software; Reporting Software

    2) By Services: Consulting Services; Implementation Services; Maintenance Services; Training Services

    Grid Capacity Map Platform Market Industry Trends: What’s Reshaping Demand?

    Leading entities within the grid capacity map platform market are concentrating on creating advanced solutions, such as intelligent grid platforms, aimed at simplifying interconnection procedures and decreasing expenses for both utilities and project developers. An intelligent grid platform constitutes a digital framework designed to consolidate real-time data, analytical tools, and automation capabilities, thereby enhancing the effective and dependable planning, operation, and administration of electrical grids. As an illustration, envelio, a grid management software provider based in Germany, introduced its Grid Connection Navigator (GCN) application to the North American market in December 2025. This application streamlines the preliminary phase of the interconnection process, enabling users to independently evaluate existing grid capacity, identify appropriate locations, and calculate connection expenditures. Fundamentally, the tool incorporates an interactive grid-capacity map, which utilities can integrate directly onto their websites for immediate, self-service public access. In contrast to conventional hosting capacity maps, GCN offers continuous data updates, encompassing power-flow-based assessments, which delivers nearly real-time and exceptionally precise understanding of grid conditions. Furthermore, it integrates seasonal and time-series hosting capacities, providing essential detailed clarity for ventures such as battery storage and flexible interconnections, where the precise timing and variability are significant factors.

    Grid Capacity Map Platform Market Industry Leaders And Competitive Landscape

    Major companies operating in the grid capacity map platform market are Siemens AG, Oracle Corporation, Schneider Electric SE, GE Vernova Inc., ABB Ltd., Eaton Corporation plc, Hitachi Energy Ltd., Autodesk Inc., Itron Inc., Esri Ltd., Bentley Systems Inc., GridBeyond Limited, Smarter Grid Solutions Inc., Spatineo Inc., Envelio GmbH, Kiwi Power Ltd., DNV GL, ETAP, Flexitricity Ltd., and PowerWorld Corporation.

    View The Full Grid Capacity Map Platform Market Report:

    https://thebusinessresearchcompany.com/report/grid-capacity-map-platform-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Grid Capacity Map Platform Market Regional Analysis And Leading Geography

    North America was the largest region in the grid capacity map platform market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the grid capacity map platform market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Grid Analytics Software Market Reaches $8.68 Billion In 2026: Key Developments Shaping Expansion

    Grid Analytics Software Market Reaches $8.68 Billion In 2026: Key Developments Shaping Expansion

    Backed by market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, wider supply chain intelligence, emerging startup coverage, and detailed product-level insights, The Business Research Company’s 2026 market reports are designed to offer research that is more actionable and strategically valuable than ever.

    Grid Analytics Software Market CAGR Outlook And Future Development

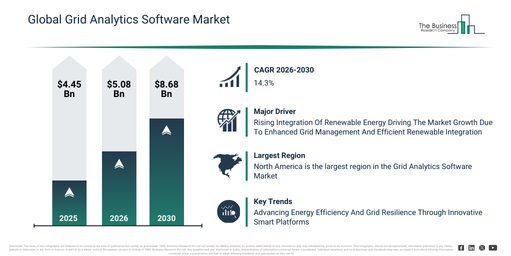
    The grid analytics software market has experienced rapid growth recently. It is set to expand from $4.45 billion in 2025 to $5.08 billion in 2026, achieving a compound annual growth rate (CAGR) of 14.1%. In the historical period, this growth was driven by factors such as the expansion of smart grid infrastructure, increasing deployment of smart meters, the rising complexity of power distribution networks, the growth of renewable energy integration, and the early adoption of grid monitoring software.

    The grid analytics software market is anticipated to experience substantial expansion over the next few years. This market is projected to reach $8.68 billion by 2030, demonstrating a compound annual growth rate (CAGR) of 14.3%. The growth anticipated during this forecast period stems from factors such as the increasing electrification of transportation, rising investments in grid digitalization, the growing need for real-time grid intelligence, the expansion of distributed energy resources, and an increased focus on predictive maintenance. Significant trends for the forecast period encompass a greater adoption of real-time grid monitoring platforms, the rising utilization of predictive analytics for grid reliability, the expanding integration of demand response analytics, the proliferation of cloud-based grid analytics solutions, and an enhanced emphasis on grid resilience and reliability.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33130&type=smp&name=Grid%20Analytics%20Software%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Grid Analytics Software Market Demand Drivers: What’s Powering Industry Growth?

    The expanding integration of renewable energy sources is projected to drive the growth of the grid analytics software market moving ahead. These sources encompass energies derived from natural processes that are continuously replenished, including solar, wind, hydro, geothermal, and biomass. The adoption of renewable energy sources is escalating to lessen dependence on fossil fuels and decrease greenhouse gas emissions, thereby contributing to climate change mitigation. Grid analytics software supports renewable energy by offering real-time insights into grid performance, optimizing energy flow, and facilitating the efficient integration of variable renewable sources. For example, in January 2024, the International Energy Agency, a France-based intergovernmental organization, reported that in 2023, worldwide renewable energy capacity additions significantly increased by 50%, reaching almost 510 gigawatts (GW), with solar PV making up approximately three-quarters of all new installations globally. Consequently, the expanding integration of renewable energy sources is fueling the growth of the grid analytics software market.

    Grid Analytics Software Market Segment Analysis And Revenue Potential

    The grid analytics software market covered in this report is segmented –

    1) By Component: Software; Services

    2) By Deployment Mode: Cloud-Based; On-Premises; Hybrid

    3) By Application: Asset Management; Demand Response; Energy Forecasting; Grid Optimization; Load Research; Other Applications

    4) By End User: Utilities; Energy Providers; Industrial; Commercial; Other End Users

    Subsegments:

    1) By Software: Advanced Distribution Management System; Outage Management System; Predictive Analytics Platform; Energy Management System; Asset Performance Management System

    2) By Services: System Integration; Consulting; Support And Maintenance; Implementation And Deployment; Training And Education

    Grid Analytics Software Market Innovation Trends: What Developments Are Reshaping The Industry?

    Leading companies within the grid analytics software market are concentrating on developing advanced solutions, such as the smart grid management platform, to enhance energy distribution, boost grid reliability, enable continuous monitoring, and support proactive maintenance for more effective and robust power systems. A smart grid management platform refers to a digital tool that empowers utilities to oversee and analyze electricity flow across the network, identify issues, predict usage, and integrate renewable energy sources for improved operational effectiveness and grid stability. For instance, in March 2025, Schneider Electric SE, a France-based energy technology firm, introduced a One Digital Grid Platform to consolidate grid operations, facilitate real-time monitoring, and elevate energy efficiency. This is a unified, AI-powered solution built on Microsoft Azure that modernizes utility grids by combining planning, operations, asset management, and customer engagement to address increasing electricity demand from AI data centers, EVs, renewables, and extreme weather difficulties. Its primary goal is to provide real-time insights, predictive analytics, and automation, leading to reductions in outages by up to 40%, DER interconnection times by 25%, and application deployment by 60%, while enabling effortless scalability without requiring extensive overhauls of existing systems. Utilities achieve a verified ROI, a 184% return, $62M in benefits, and a 16-month payback, with advantages including 65% operator time savings, 35% faster field resolutions, and increased resilience for decarbonization, directly corresponding with grid innovation needs in your energy tech expertise.

    Grid Analytics Software Market Key Participants And Competitive Landscape

    Major companies operating in the grid analytics software market are Siemens AG, Hitachi Ltd., Lockheed Martin Corporation, Accenture plc, IBM Corporation, Cisco Systems Inc., General Electric Company, Oracle Corporation, Schneider Electric SE, SAP SE, ABB Ltd., Eaton Corporation, Leidos Holdings Inc., Wipro Limited, Landis+Gyr Group AG., itron inc., Holley Technology Ltd., Willdan Group, C3 AI Inc., AutoGrid Systems Inc., Amperon Holdings Inc., Grid4C Ltd.

    View The Full Grid Analytics Software Market Report:

    https://thebusinessresearchcompany.com/report/grid-analytics-software-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Grid Analytics Software Market Geographic Analysis: Where Is Demand Accelerating Fastest?

    North America was the largest region in the grid analytics software market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the grid analytics software market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Green Ammonia Peaker Front End Engineering Design (FEED) Market Size Forecast From 2026 To 2030: Key Industry Trends

    Green Ammonia Peaker Front End Engineering Design (FEED) Market Size Forecast From 2026 To 2030: Key Industry Trends

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Green Ammonia Peaker Front End Engineering Design (FEED) Market Forecast: Value Set To Climb From $1.38 Billion To $3.55 Billion

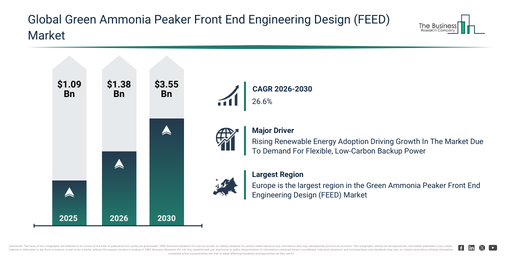
    The market size for green ammonia peaker front end engineering design (feed) has experienced substantial growth in recent years. This market is projected to expand from $1.09 billion in 2025 to $1.38 billion in 2026, achieving a compound annual growth rate (CAGR) of 26.3%. Historically, this expansion has been driven by factors such as increasing renewable energy penetration, grid stability issues arising from intermittent power sources, the early adoption of ammonia-based fuels, the expansion of power infrastructure planning, and the availability of specialized engineering expertise.

    The green ammonia peaker front end engineering design (feed) market is projected to experience rapid expansion in the coming years. Its size is forecast to reach $3.55 billion by 2030, with a compound annual growth rate (CAGR) of 26.6%. This growth during the projection period is attributed to escalating investments in green hydrogen and ammonia initiatives, a heightened need for carbon-neutral peaking power facilities, the proliferation of adaptable power generation resources, increasing governmental backing for low-carbon energy sources, and improvements in ammonia combustion techniques. Key trends anticipated over the forecast timeframe encompass the intensified creation of low-carbon peaking power designs, an escalating requirement for deployable green energy options, a concentrated effort on modular power plant engineering, the broadening of power infrastructure integrated with renewables, and a greater emphasis on safety and ecological evaluations.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33128&type=smp&name=Green%20Ammonia%20Peaker%20Front%20End%20Engineering%20Design%20%28FEED%29%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Green Ammonia Peaker Front End Engineering Design (FEED) Market Growth Factors Behind Sustained Expansion

    The expanding adoption of renewable energy sources is anticipated to drive the advancement of the green ammonia peaker front-end engineering design market in the coming years. Renewable energy, derived from naturally replenishing resources like solar, wind, and hydropower, is seeing increased usage. This surge is primarily driven by the imperative to lower carbon emissions, as these sources generate minimal greenhouse gases compared to fossil fuels, thus aiding in the fight against climate change. Green ammonia peaker FEED supports renewable energy by offering an adaptable, low-carbon backup power supply capable of rapidly delivering electricity when renewable inputs such as solar or wind are insufficient, thereby ensuring grid stability and facilitating greater renewable integration. For instance, Eurostat, a Luxembourg-based government agency, reported in December 2024 that renewable energy constituted 24.5% of the total energy consumed in the EU in 2023, an increase from 23.0% in 2022. Consequently, the growth in renewable energy is a significant factor boosting the green ammonia peaker front-end engineering design market. The escalating investment in research and development initiatives is anticipated to stimulate the expansion of the green ammonia peaker front-end engineering design market in the coming years. This funding represents financial support allocated to R&D efforts focused on developing or enhancing products, technologies, or processes. An upswing in R&D funding is observed due to robust investments from both governmental and private sectors, geared towards fostering innovation and technological progress. Such funding aids green ammonia peaker front-end engineering design by facilitating technical validation, optimizing processes, and mitigating risks, all crucial steps for advancing ammonia-based peaking power projects toward commercial viability. For example, the Office for National Statistics, a UK-based government agency, reported that in 2023, the UK government’s net expenditure on research and development (R&D) rose to £17.4 billion ($22.1 billion), an increase from £16.1 billion ($20.45 billion) in 2022, signifying an 8.2% surge. Thus, the growing funding for research and development projects is a key factor driving the green ammonia peaker front-end engineering design market.

    Green Ammonia Peaker Front End Engineering Design (FEED) Market Segment Outlook: Which Categories Are Growing Fastest?

    The green ammonia peaker front end engineering design (feed) market covered in this report is segmented –

    1) By Service Type: Engineering Services; Front-End Design Services; Consulting Services; Feasibility Analysis Services

    2) By Technology: Electrolysis; Haber-Bosch Process; Other Technologies

    3) By Plant Capacity: Small-Scale Or Modular; Mid-Scale; Large-Scale

    4) By Application: Power Generation; Energy Storage; Grid Stabilization; Other Applications

    5) By End User: Utilities; Independent Power Producers; Industrial; Other End Users

    Subsegments:

    1) By Engineering Services: Process Engineering; Mechanical Engineering; Electrical Engineering; Instrumentation And Control Engineering; Plant Layout And Infrastructure Engineering

    2) By Front-End Design Services: Conceptual Plant Design; Process Flow Diagram Development; Equipment Specification Design; Capital Cost Estimation; Project Scope Definition

    3) By Consulting Services: Technology Selection Advisory; Regulatory And Compliance Advisory; Project Management Consulting; Sustainability And Environmental Advisory; Risk Assessment Consulting

    4) By Feasibility Analysis Services: Technical Feasibility Assessment; Economic Feasibility Evaluation; Operational Feasibility Study; Environmental Impact Assessment; Market And Demand Feasibility Analysis

    Green Ammonia Peaker Front End Engineering Design (FEED) Market Leading Players And Competitive Positioning

    Major companies operating in the green ammonia peaker front end engineering design (feed) market are ENGIE S.A., Sumitomo Corporation, Siemens Energy AG, Linde plc., Mitsubishi Heavy Industries Ltd., HyundAI Engineering Co. Ltd., Air Products and Chemicals Inc., Worley Limited, KBR Inc., Technip Energies N.V., Maire Tecnimont S.p.A., Técnicas Reunidas S.A., Haldor Topsoe A/S, Nel ASA, Pan Gulf Technologies Pvt. Ltd., Proton Ventures, Casale S.A., ACME Group, Nuberg Green Energy, Thyssenkrupp Uhde GmbH

    View The Full Green Ammonia Peaker Front End Engineering Design (FEED) Market Report:

    https://thebusinessresearchcompany.com/report/green-ammonia-peaker-front-end-engineering-design-feed-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Green Ammonia Peaker Front End Engineering Design (FEED) Market Regional Distribution: Which Areas Power Market Growth?

    Europe was the largest region in the green ammonia peaker front-end engineering design market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the green ammonia peaker front end engineering design (feed) market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Gas Distribution Analytics Market Outlook Through 2030: Understanding The Growth Opportunity

    Gas Distribution Analytics Market Outlook Through 2030: Understanding The Growth Opportunity

    Featuring market attractiveness scoring, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, deeper supply chain intelligence, emerging startup tracking, and granular product-level insights, The Business Research Company’s 2026 market reports are built to deliver research that is both more actionable and more strategically valuable.

    Gas Distribution Analytics Market Growth Analysis: How Will Revenue Trend Over The Forecast Period?

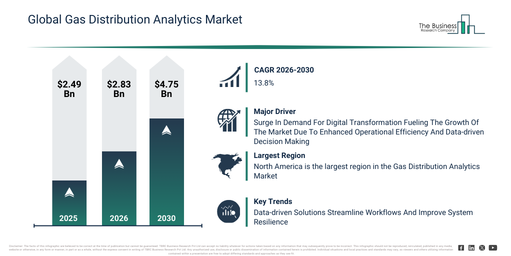
    The gas distribution analytics market size has expanded considerably in recent years. It is anticipated to rise from $2.49 billion in 2025 to $2.83 billion in 2026, achieving a compound annual growth rate (CAGR) of 13.6%. The historical growth of this market can be attributed to several factors, including the expansion of urban gas distribution networks, increasing regulatory safety requirements, the deployment of digital metering infrastructure, a rise in pipeline leakage incidents, and the adoption of data-driven utility management systems.

    The gas distribution analytics market is poised for substantial expansion in the coming years. It is projected to reach $4.75 billion in 2030, at a compound annual growth rate (CAGR) of 13.8%. This growth during the forecast period is fueled by increasing investments in smart utility infrastructure, a rising demand for advanced demand forecasting tools, the expansion of AI-enabled network optimization, a growing focus on decarbonized gas distribution, and the increasing integration of cybersecurity solutions. Significant trends anticipated for this period include a greater adoption of real-time leak detection analytics, an increased reliance on predictive maintenance models, the wider deployment of smart gas metering systems, the expansion of cloud-based distribution analytics platforms, and an enhanced focus on network safety monitoring.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33117&type=smp&name=Gas%20Distribution%20Analytics%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Gas Distribution Analytics Market Growth Drivers: What’s Behind The Acceleration?

    The increasing need for digital transformation is anticipated to fuel the expansion of the gas distribution analytics market in the future. Digital transformation involves integrating digital technologies across all business functions and operations to boost efficiency, improve customer satisfaction, and foster innovation. This rising need for digital transformation stems from the requirement for better operational efficiency, allowing businesses to automate processes, streamline workflows, and base decisions on data. Gas distribution analytics contributes to the demand for digital transformation by offering real-time insights into consumption trends, identifying leaks, and optimizing networks, which empowers utilities to make data-driven choices and boost their operational effectiveness. For example, in November 2023, the Central Digital and Data Office (CDDO), a UK-based government agency, reported that the Government Digital and Data profession grew by 19% between April 2022 and April 2023, enhancing crucial digital competencies throughout the civil service. Currently, 32 organisations have adopted the standardized Government Digital and Data pay framework, which aids in reducing reliance on contractors and creating savings for taxpayers. Consequently, the increasing requirement for digital transformation is propelling the demand within the gas distribution analytics market.

    Gas Distribution Analytics Market Segment Analysis And Revenue Potential

    The gas distribution analytics market covered in this report is segmented –

    1) By Component: Software; Hardware; Services

    2) By Deployment Mode: On Premises; Cloud

    3) By Application: Leak Detection; Asset Management; Demand Forecasting; Network Optimization; Safety Monitoring; Other Applications

    4) By End User: Residential; Commercial; Industrial; Utilities

    Subsegments:

    1) By Software: Pipeline Monitoring Software; Demand Forecasting Software; Leak Detection Software; Network Optimization Software; Asset Performance Management Software

    2) By Hardware: Smart Gas Meters; Flow Measurement Devices; Pressure Sensors; Communication Gateways; Data Acquisition Devices

    3) By Services: Consulting And Advisory Services; System Integration Services; Installation And Deployment Services; Maintenance And Support Services; Data Analytics And Reporting Services

    Gas Distribution Analytics Market Trends: What’s Defining The Industry’s Next Phase?

    Leading companies operating in the gas distribution analytics market are primarily focused on developing advanced solutions, such as predictive monitoring and real-time analytics, to improve network efficiency, lower operational risks, and enhance service reliability. Predictive monitoring and real-time analytics denote technological features that employ sensors, IoT, and AI algorithms to track pipeline performance, detect abnormalities, and anticipate maintenance needs before any failures occur. For instance, in March 2025, Honeywell, a US-based technology company, introduced innovative automation and remote operability solutions for utilities, specifically designed to enhance gas distribution network management. This technology aims to deliver real-time insights into system performance, enabling predictive maintenance and optimizing operational workflows to minimize downtime and increase safety. It also integrates AI-driven analytics with connected devices, supporting data-driven decision-making, faster incident response, and more efficient resource allocation. The system is engineered to function across large-scale gas distribution networks, ensuring reliable, scalable, and secure operations even under demanding conditions.

    Gas Distribution Analytics Market Leading Players And Competitive Positioning

    Major companies operating in the gas distribution analytics market are Siemens AG, Accenture plc, International Business Machines Corporation, General Electric Company, Oracle Corporation, Schneider Electric SE, Honeywell International Inc., SAP SE, ABB Ltd., Tata Consultancy Services Limited, Capgemini SE, Infosys Limited, Emerson Electric Co., Wipro Limited, CGI Inc., Rockwell Automation, Inc., Yokogawa Electric Corporation, SAS Institute Inc., Itron Inc., and Landis+Gyr Group AG.

    View The Full Gas Distribution Analytics Market Report:

    https://thebusinessresearchcompany.com/report/gas-distribution-analytics-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Gas Distribution Analytics Market Regional Split: Which Areas Are Fueling Growth?

    North America was the largest region in the gas distribution analytics market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the gas distribution analytics market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Front-Of-The-Meter Battery Market Explained: What Is Fueling Growth To $25.21 Billion By 2030?

    Front-Of-The-Meter Battery Market Explained: What Is Fueling Growth To $25.21 Billion By 2030?

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Front-Of-The-Meter Battery Market CAGR Outlook And Future Development

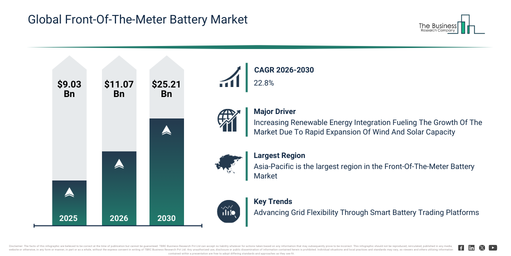
    The front-of-the-meter battery market has experienced rapid expansion in its size over recent years. It is projected to expand from $9.03 billion in 2025 to $11.07 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 22.6%. Historically, this growth has been driven by factors such as the expansion of renewable energy generation capacity, mounting grid congestion challenges, the initial adoption of frequency regulation storage systems, a reduction in lithium-ion battery costs, and energy storage pilot projects supported by governments.

    The front-of-the-meter battery market is anticipated to experience significant expansion over the coming years, reaching $25.21 billion in 2030, exhibiting a compound annual growth rate (CAGR) of 22.8%. This projected growth during the forecast period is primarily driven by escalating investments in grid-scale energy storage, a heightened need for long-duration storage solutions, the broadening of power grids heavily reliant on renewables, the increasing embrace of AI-powered energy management systems, and enhanced regulatory backing for grid flexibility. Key developments expected within this period involve a rise in the deployment of utility-scale battery storage systems, greater uptake of lithium-ion grid batteries, closer integration of batteries with renewable energy sources, the proliferation of advanced battery management systems, and a strengthened emphasis on the reliability and resilience of the grid.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33113&type=smp&name=Front-Of-The-Meter%20Battery%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Front-Of-The-Meter Battery Market Growth Catalysts And Demand Drivers

    The expanding integration of renewable energy sources is anticipated to drive the growth of the front-of-the-meter battery market. This integration signifies the increasing proportion of electricity generated from renewables like wind and solar within the total power generation mix. The rise in renewable energy integration is due to governments and utilities continuing to expand wind and solar capacity to meet climate targets, reduce reliance on fossil fuels, and leverage decreasing renewable generation costs. Front-of-the-meter battery technology facilitates this integration by enabling utilities to store surplus renewable power during abundant generation and release it during peak demand, thereby stabilizing the grid and enhancing renewable penetration. For example, in November 2024, according to the Ember-Energy Organization, a UK-based think tank, solar installations are expected to reach 593 GW in 2024, representing a 29% year-on-year increase following strong 87% growth in 2023. Consequently, the increasing integration of renewable energy sources is fueling the growth of the front-of-the-meter battery market.

    Front-Of-The-Meter Battery Market Segments: Where Is Growth Concentrated?

    The front-of-the-meter battery market covered in this report is segmented –

    1) By Battery Type: Lithium-Ion; Lead-Acid; Flow Batteries; Nickel-Based; Other Batteries

    2) By Ownership Model: Utility Owned; Third Party Owned; Customer Owned

    3) By Application: Grid Services; Renewable Integration; Peak Shaving; Frequency Regulation; Other Applications

    4) By End User: Utilities; Independent Power Producers; Commercial And Industrial; Other End Users

    Subsegments:

    1) By Lithium-Ion: Lithium Iron Phosphate; Nickel Manganese Cobalt; Lithium Titanate; Lithium Nickel Cobalt Aluminum Oxide

    2) By Lead-Acid: Flooded Lead Acid; Valve Regulated Lead Acid; Absorbent Glass Mat; Gel Lead Acid

    3) By Flow Batteries: Vanadium Redox Flow; Zinc Bromine Flow; Iron Flow; All Vanadium Flow

    4) By Nickel-Based: Nickel Cadmium; Nickel Metal Hydride; Nickel Zinc; Nickel Iron

    5) By Other Batteries: Sodium Sulfur; Solid State Battery; Advanced Lithium Sulfur; Zinc Air

    Front-Of-The-Meter Battery Market Trends Shaping Long-Term Demand

    Major companies operating in the front-of-the-meter battery market are focusing on developing advanced energy storage solutions, such as grid-scale battery trading platforms, to enhance electricity reliability, optimize energy dispatch, and support renewable integration. Grid-scale battery trading platforms refer to digital marketplaces or systems that enable the buying, selling, and optimization of large-scale battery storage capacity for electricity grid balancing and energy trading. For instance, in June 2025, GridBeyond, an Ireland-based energy technology company, launched its first battery trading operation in Japan. The platform integrates high-capacity FTM batteries with real-time market analytics, allowing operators to participate in energy markets, optimize revenue streams, and enhance grid flexibility. This solution leverages predictive algorithms and automated dispatch systems to maximize performance, reduce energy waste, and accelerate the adoption of clean energy.

    Front-Of-The-Meter Battery Market Company Landscape And Competitive Strategy

    Major companies operating in the front-of-the-meter battery market are Tesla Inc., BYD Company Limited, Siemens AG, Panasonic Corporation, Contemporary Amperex Technology Co. Limited (CATL), General Electric (GE) Renewable Energy, ABB Ltd., Mitsubishi Power (Mitsubishi Heavy Industries Group), LG Energy Solution, Toshiba Corporation, Leclanché SA, Samsung SDI, Nidec Corporation, Sungrow Power Supply Co. Ltd., EVE Energy Co. Ltd., Wartsila Corporation, GS Yuasa International, EnerSys, Fluence Energy, ENGIE SA, Exide Technologies, NEC Energy Solutions, Hitachi Energy, Powin Energy, and Kokam Co. Ltd.

    View The Full Front-Of-The-Meter Battery Market Report:

    https://thebusinessresearchcompany.com/report/front-of-the-meter-battery-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Front-Of-The-Meter Battery Market Largest Region: Which Geography Holds The Highest Market Share?

    Asia-Pacific was the largest region in the front-of-the-meter battery market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the front-of-the-meter battery market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Forecast To Reach $21.91 Billion By 2030: Key Growth Drivers And Industry Trends

    Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Forecast To Reach $21.91 Billion By 2030: Key Growth Drivers And Industry Trends

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Poised To Hit $21.91 Billion By 2030 With A 21.5% CAGR

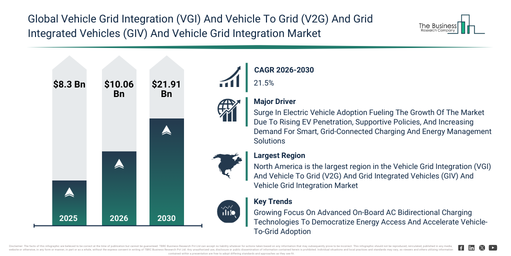
    The vehicle grid integration (vgi) and vehicle to grid (v2g) and grid integrated vehicles (giv) and vehicle grid integration market has experienced significant expansion in recent years. It is anticipated to increase from $8.3 billion in 2025 to $10.06 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 21.2%. This historical growth can be linked to the rising adoption of electric vehicles, the launch of smart charging pilot projects, the fluctuating nature of renewable energy, the implementation of grid demand response programs, and early V2G demonstrations.

    The market encompassing vehicle grid integration (VGI), vehicle to grid (V2G), and grid integrated vehicles (GIV) is projected to experience substantial expansion in the coming years. This market is anticipated to reach a valuation of $21.91 billion by 2030, exhibiting a compound annual growth rate (CAGR) of 21.5%. Key drivers for this growth during the projected period include the widespread electrification of EV fleets, the implementation of bidirectional chargers, increasing grid flexibility demands, the broader adoption of time-of-use pricing, and expanded participation from distributed storage. Significant trends anticipated for this forecast period encompass bidirectional EV charging platforms, utility-integrated EV energy programs, V2G aggregation models focused on fleets, intelligent charging and load shifting solutions, and marketplaces for EV grid services.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33346&type=smp&name=Vehicle%20Grid%20Integration%20%28VGI%29%20And%20Vehicle%20To%20Grid%20%28V2G%29%20And%20Grid%20Integrated%20Vehicles%20%28GIV%29%20And%20Vehicle%20Grid%20Integration%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Demand Drivers: What’s Powering Industry Growth?

    The increasing adoption of electric vehicles is expected to propel the growth of the vehicle grid integration (VGI), vehicle-to-grid (V2G), grid-integrated vehicles (GIV), and vehicle grid integration market going forward. An electric vehicle is a vehicle powered wholly or partially by electricity, utilizing one or more electric motors supplied by energy stored in rechargeable batteries. This surge in EV adoption is occurring because governments and consumers are prioritizing lower emissions, reduced operating costs, and sustainability, which generates stronger demand for electrified transportation solutions. Vehicle Grid Integration solutions support the increasing adoption of electric vehicles by enabling smart energy exchange, demand management, and integration of EV charging with the electricity grid, thereby making EV charging more efficient, reliable, and cost-effective. For instance, in October 2025, according to data published by the International Energy Agency (IEA), a France-based intergovernmental organization, global electric car sales surpassed 17 million units in 2024, accounting for over 20 percent of total car sales, marking an increase of 3.5 million from the previous year, and are projected to exceed 20 million units in 2025, representing more than one-quarter of worldwide car sales. Therefore, the increasing adoption of electric vehicles is driving the growth of the vehicle grid integration (VGI), vehicle-to-grid (V2G), grid-integrated vehicles (GIV), and vehicle grid integration market.

    Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Segment Analysis: What Are The Core Market Categories?

    The vehicle grid integration (vgi) and vehicle to grid (v2g) and grid integrated vehicles (giv) and vehicle grid integration market covered in this report is segmented –

    1) By Component: Electric Vehicle Supply Equipment; Software and Power Management Systems; Smart Meters and Communication Modules; Home Energy Management

    2) By Technology or Product Type: Vehicle-To-Grid Systems; Grid-Integrated Vehicles; Vehicle Grid Integration Platforms; Smart Charging Infrastructure; Bi-Directional Charging Systems

    3) By Vehicle Type: Electric Vehicles; Hybrid Vehicles; Plug-In Hybrid Vehicles

    4) By Application or Use Case: Grid Services and Wholesale Market Applications; Demand Response and Utility Program Management; Renewable Energy Integration and Time-Of-Use Optimization; Resilience and Backup Power; Fleet Energy Cost and Carbon Footprint Management

    5) By End-User: Individual Consumers; Commercial Users; Government Organizations; Utility Companies; Fleet Operators

    Subsegments:

    1) By Electric Vehicle Supply Equipment: Level One Charging Equipment; Level Two Charging Equipment; Direct Current Fast Charging Equipment; Bidirectional Charging Equipment; Wireless Charging Equipment

    2) By Software and Power Management Systems: Charging Management Software; Energy Management Software; Grid Balancing and Load Management Software; Demand Response Management Software; Billing and Payment Management Software; Analytics and Optimization Software

    3) By Smart Meters and Communication Modules: Advanced Metering Devices; Bidirectional Energy Meters; Communication Gateways; Data Concentrator Units; Wireless Communication Modules; Wired Communication Modules

    4) By Home Energy Management: Home Energy Management Controllers; Smart Home Energy Monitoring Systems; Residential Load Management Systems; Renewable Energy Integration Systems; Energy Storage Management Systems

    Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Innovation Trends: What Developments Are Reshaping The Industry?

    Major companies engaged in the Vehicle Grid Integration (VGI), Vehicle-to-Grid (V2G), and Grid-Integrated Vehicles (GIV) market are primarily focused on advancing bidirectional charging technologies, specifically on-board AC bidirectional charging, to broaden energy accessibility and reduce the financial burden for consumers entering sustainable energy ecosystems. On-board AC bidirectional charging is a system where power-conversion electronics are integrated directly into the vehicle, enabling electric vehicles to return energy to the grid through standard alternating current charging infrastructure, thus bypassing the expense of external bidirectional chargers. As an example, in October 2024, Nissan Motor Co., Ltd., a Japan-based automotive manufacturer, declared its plans to introduce affordable on-board bidirectional charging capabilities in select electric vehicle models starting in 2026. This move supports the company’s The Arc business strategy by offering distinctive electrification features, creating new revenue streams, and accelerating the adoption of electric vehicles. Initially, the vehicle-to-grid functionality will be launched in the United Kingdom, followed by a phased rollout across various European markets.

    Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Competitive Landscape: Which Companies Lead The Industry?

    Major companies operating in the vehicle grid integration (vgi) and vehicle to grid (v2g) and grid integrated vehicles (giv) and vehicle grid integration market are Volkswagen Group, Ford Motor Company, General Motors Company, BMW AG, Honda Motor Co. Ltd., Tesla Inc., Nissan Motor Corporation, BYD Auto Co. Ltd., Siemens AG, Hitachi Ltd., Stellantis N.V., Iberdrola, Renault, Denso Corporation, Tokyo Electric Power (TEPCO), LG Chem, Schneider Electric SE, ABB Ltd., Mitsubishi Motors Corporation, OVO Energy Ltd, Enel X, Nuvve Holding Corp.

    View The Full Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Report:

    https://thebusinessresearchcompany.com/report/vehicle-grid-integration-vgi-and-vehicle-to-grid-v2g-and-grid-integrated-vehicles-giv-and-vehicle-grid-integration-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Vehicle Grid Integration (VGI) And Vehicle To Grid (V2G) And Grid Integrated Vehicles (GIV) And Vehicle Grid Integration Market Regional Outlook: Where Is Opportunity Concentrated?

    North America was the largest region in the vehicle grid integration (vgi) and vehicle to grid (v2g) and grid integrated vehicles (giv) and vehicle grid integration market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the vehicle grid integration (vgi) and vehicle to grid (v2g) and grid integrated vehicles (giv) and vehicle grid integration market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Synchrophasor Data Service Market Size Growth: From $1.38 Billion In 2026 To $2.28 Billion By 2030

    Synchrophasor Data Service Market Size Growth: From $1.38 Billion In 2026 To $2.28 Billion By 2030

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Synchrophasor Data Service Market CAGR Outlook And Future Development

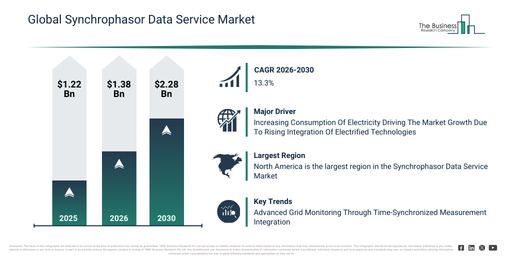
    The synchrophasor data service market has experienced swift expansion recently. This market is projected to expand from $1.22 billion in 2025 to reach $1.38 billion by 2026, demonstrating a compound annual growth rate (CAGR) of 13.1%. Historically, this expansion was driven by factors such as grid blackout incidents, an increase in phasor measurement unit deployments, past grid modernization initiatives, regulatory requirements for reliability, and the increasing complexity of transmission networks.

    The synchrophasor data service market size is expected to undergo rapid expansion in the coming years. It is projected to reach $2.28 billion in 2030, demonstrating a compound annual growth rate (CAGR) of 13.3%. This growth during the forecast period can be attributed to several factors, including the increasing penetration of renewable energy into grids, a rising need for real-time grid visibility, the expansion of digital substations, higher investments in grid analytics platforms, and growing cross-border grid interconnections. Significant trends anticipated in the forecast period include wide-area grid situational awareness platforms, real-time phasor data analytics services, cloud-hosted phasor data management, high-resolution grid event detection, and interoperable phasor data integration frameworks.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33334&type=smp&name=Synchrophasor%20Data%20Service%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Synchrophasor Data Service Market Demand Drivers: What’s Powering Industry Growth?

    The anticipated rise in electricity usage is projected to fuel the expansion of the synchrophasor data service market in the future. Electricity consumption encompasses the overall electrical energy utilized by residential, commercial, industrial, and transport sectors for powering devices, machinery, heating, cooling, and various other activities. This consumption is growing due to rapid urbanization and industrial development, which places a greater burden on power grids and necessitates advanced monitoring, analytics, and grid-stability solutions, including synchrophasor data services. These services assist electricity systems by providing real-time, time-synchronized grid measurements, thereby improving the visibility, stability, and control of power networks. This empowers utilities to effectively handle increasing demand, incorporate renewable energy sources, avert power interruptions, and guarantee a dependable, secure, and resilient electricity supply. As an illustration, in April 2024, data from the Department of Climate Change, Energy, the Environment and Water, an Australia-based government administration, indicated that Australia’s total electricity generation reached approximately 273,106 gigawatt hours (GWh) in 2023. Of this, renewable energy sources contributed about 95,963 GWh, representing 35% of the total generation, which highlights both continuous high electricity usage and increasing grid complexity due to the integration of variable renewables. Consequently, the rising consumption of electricity is propelling the growth of the synchrophasor data service market.

    Synchrophasor Data Service Market Segments: Where Is Growth Concentrated?

    The synchrophasor data service market covered in this report is segmented –

    1) By Component: Software; Hardware; Services

    2) By Deployment Mode: On-Premises; Cloud

    3) By Application: Grid Monitoring; Fault Analysis; State Estimation; Power System Control; Other Applications

    4) By End-User: Utilities; Independent System Operators; Industrial; Other End-Users

    Subsegments:

    1) By Software: Phasor Data Management Software; Real Time Grid Analytics Software; Visualization and Reporting Software; State Estimation Software

    2) By Hardware: Phasor Measurement Units; Phasor Data Concentrators; Time Synchronization Devices; Communication Interface Hardware

    3) By Services: System Integration Services; Data Hosting and Management Services; Monitoring and Analytics Services; Maintenance and Support Services

    Synchrophasor Data Service Market Innovation Trends: What Developments Are Reshaping The Industry?

    Leading companies in the synchrophasor data service market are prioritizing the implementation of advanced solutions for synchrophasor data acquisition and concentration. This strategic focus aims to enhance grid visibility, improve fault detection, facilitate load forecasting, and enable more efficient distribution network planning, especially with increasing renewable energy integration and battery storage adoption. Synchrophasor data services are defined as systems that capture GPS time-synchronized measurements from Phasor Measurement Units (PMUs) and stream them into Phasor Data Concentrators (PDCs), where this information is aligned and made available for real-time analysis and interpretation across the power grid. For example, in June 2023, NOJA Power, an Australia-based electricity distribution equipment provider, unveiled a distribution-level synchrophasor acquisition capability as part of an ARENA-supported trial. This involved using the openPDC platform to aggregate synchrophasor data from around 100 RC-20 recloser controls. This specific implementation allowed engineers to analyze synchronized grid measurements across the distribution network, resulting in improvements to network impedance calculations, equipment failure detection, and operational planning.

    Synchrophasor Data Service Market Competitive Landscape: Who Leads The Industry?

    Major companies operating in the synchrophasor data service market are Siemens AG, Hitachi Energy Ltd., General Electric Company, ABB Ltd., Quanta Technology Inc., XJ Electric Co. Ltd., Schweitzer Engineering Laboratories Inc., CG Power and Industrial Solutions Limited, Qualitrol Company LLC, Electro Industries/GaugeTech, Vizimax Inc., Kalkitech Pvt. Ltd., Power System Engineering Inc., SATEC Global Ltd., Electric Power Group LLC, ERLPhase Power Technologies, NR Electric Co. Ltd., Arcteq Relays Ltd., Arbiter Systems Inc., LogicLab GmbH,

    View The Full Synchrophasor Data Service Market Report:

    https://thebusinessresearchcompany.com/report/synchrophasor-data-service-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Synchrophasor Data Service Market Geographic Landscape: Which Region Dominates Industry Growth?

    North America was the largest region in the synchrophasor data service market in 2025. Asia-Pacific` is expected to be the fastest-growing region in the forecast period. The regions covered in the synchrophasor data service market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Substation Wide Area Monitoring System Market Reaches $2.22 Billion In 2026: Key Developments Shaping Expansion

    Substation Wide Area Monitoring System Market Reaches $2.22 Billion In 2026: Key Developments Shaping Expansion

    Backed by market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, wider supply chain intelligence, emerging startup coverage, and detailed product-level insights, The Business Research Company’s 2026 market reports are designed to offer research that is more actionable and strategically valuable than ever.

    Substation Wide Area Monitoring System Market Value Growth And Long-Term Outlook

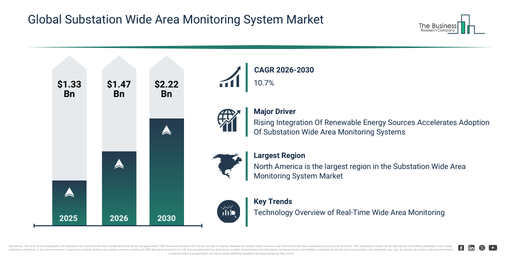
    The substation wide area monitoring system market has seen rapid growth in recent years. It is anticipated to expand from $1.33 billion in 2025 to $1.47 billion in 2026, exhibiting a compound annual growth rate (CAGR) of 10.5%. The historical rise in this market can be attributed to an increase in grid instability events, the expansion of high voltage networks, a surge in substation automation, a heightened focus on blackout prevention, and the development of synchrophasor technology.

    The substation wide area monitoring system market size is projected to experience substantial growth over the next few years. This market is expected to expand to $2.22 billion in 2030, exhibiting a compound annual growth rate (CAGR) of 10.7%. This projected growth can be linked to smart grid modernization programs, increasing renewable energy grid integration, the expansion of cross-border grid links, elevated investment in grid visibility tools, and a growing demand for predictive grid monitoring. Significant trends anticipated during the forecast period include the implementation of phasor measurement networks, the rise of real-time grid analytics platforms, the broadening deployment of high-speed substation sensors, the increasing utilization of event detection software, and the integration of wide area grid visualization tools.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33330&type=smp&name=Substation%20Wide%20Area%20Monitoring%20System%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Substation Wide Area Monitoring System Market Growth Backed By Core Demand Fundamentals

    The incorporation of renewable energy sources is anticipated to drive expansion in the substation wide area monitoring system market in the future. These energy sources are naturally restored within a human timeframe and are capable of repeated use without depletion. The impetus for integrating renewable energy comes from the imperative to decrease greenhouse gas emissions and address climate change. A substation wide area monitoring system (WAMS) facilitates this integration by offering real-time visibility, synchronized operations, and stability surveillance across the electrical grid, thereby allowing operators to handle the fluctuating and intermittent nature of renewable power generation while upholding grid reliability. As an illustration, in January 2024, data from the International Energy Agency (IEA) revealed that worldwide renewable power capacity additions hit an unprecedented 510 GW in 2023, representing the quickest growth in over more than two decades, which substantially increases the demand for sophisticated grid monitoring and automation technologies. Consequently, the integration of renewable energy sources is fueling the expansion of the substation wide area monitoring system market.

    Substation Wide Area Monitoring System Market Segment Trends And Revenue Contributors

    The substation wide area monitoring system market covered in this report is segmented –

    1) By Component: Hardware; Software; Services

    2) By Deployment Type: On-Premises; Cloud-Based

    3) By Technology: Phasor Measurement Units; Wide Area Monitoring Protection and Control; Communication Systems; Other Technologies

    4) By Application: Voltage Monitoring; Current Monitoring

    5) By End-User: Utilities; Industrial Sector; Renewable Energy Sector; Other End-Users

    Subsegments:

    1) By Hardware: Phasor Measurement Units; Global Positioning System Receivers; Data Concentrators; Intelligent Electronic Devices; Communication Equipment

    2) By Software: Wide Area Monitoring Software; Data Analytics and Visualization Software; Event Detection and Alarm Software; System Management and Control Software; Performance Monitoring Software

    3) By Services: System Integration and Deployment Services; Consulting and Advisory Services; Support and Maintenance Services; Training and Education Services; Monitoring and Diagnostic Services

    Substation Wide Area Monitoring System Market Growth Trends Reshaping The Competitive Landscape

    Leading companies within the substation wide area monitoring systems market are increasingly concentrating on developing advanced real-time grid observability solutions to enhance situational awareness and operational reliability. Real-time grid observability utilizes high-frequency data from phasor measurement units (PMUs) to capture the dynamic behavior of power systems across wide areas, thereby enabling proactive decision-making and the early detection of system disturbances. For instance, in August 2024, Hitachi Energy, a Switzerland-based company, introduced a modernized iteration of its Network Manager WAMS, integrating PMU data directly into control room operations alongside traditional energy management system (EMS) measurements. This integration provides operators with detailed visualizations concerning sub-synchronous oscillations, system interactions, and voltage angle stability. The solution integrates seamlessly with Network Manager SCADA/EMS to deliver a unified operational view, allowing high-frequency WAMS analytics to be employed within existing applications for state estimation and voltage stability analysis, consequently offering early warnings of unsafe grid conditions. Additionally, Hitachi Energy launched an intuitive single user interface that unifies SCADA/EMS and WAMS views, while cloud-enabled capabilities facilitate scalable data processing to meet future grid monitoring requirements.

    Substation Wide Area Monitoring System Market Leading Companies And Competitive Benchmarking

    Major companies operating in the substation wide area monitoring system market are Mitsubishi Electric Corporation, Honeywell International Inc., Siemens AG, Hitachi Ltd., Cisco Systems Inc., General Electric Company, Schneider Electric SE, Siemens Energy AG, ABB Ltd, Toshiba Corporation, Eaton Eaton Corporation plc, Emerson Electric Co., Alstom SA, Rockwell Automation Inc, Nexans SA, Schweitzer Engineering Laboratories LLC, Open Systems International Inc., Kalkitech LLC, Quanta Technology LLC, Electric Power Group LLC, Vizimax Inc., Wasion Group Holdings Limited

    View The Full Substation Wide Area Monitoring System Market Report:

    https://thebusinessresearchcompany.com/report/substation-wide-area-monitoring-system-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Substation Wide Area Monitoring System Market Largest Region By Revenue And Market Share

    North America was the largest region in the substation wide area monitoring system market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the substation wide area monitoring system market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Smart Grid Synchronization Market Size In 2026: Growth Outlook And Forecast Through 2030

    Smart Grid Synchronization Market Size In 2026: Growth Outlook And Forecast Through 2030

    Backed by market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, wider supply chain intelligence, emerging startup coverage, and detailed product-level insights, The Business Research Company’s 2026 market reports are designed to offer research that is more actionable and strategically valuable than ever.

    Smart Grid Synchronization Market Growth Analysis: How Will Revenue Trend Over The Forecast Period?

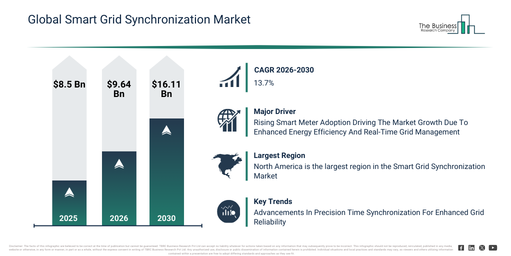
    The smart grid synchronization market has experienced significant expansion in recent times. Projections indicate its expansion from $8.5 billion in 2025 to $9.64 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 13.4%. Historically, this growth stemmed from factors such as phasor measurement unit adoption, wide area monitoring systems, grid stability programs, transmission modernization, and initiatives focused on blackout prevention.

    The smart grid synchronization market is anticipated to experience substantial expansion in the forthcoming years. It is predicted to attain a size of $16.11 billion in 2030, driven by a compound annual growth rate (CAGR) of 13.7%. This projected growth stems from factors such as the management of renewable variability, increasing demand for microgrid synchronization, high penetration of distributed energy resources (DER), the necessity for real-time grid control, and the advancement of grid analytics. Prominent trends throughout this period encompass synchrophasor based grid coordination, the deployment of high precision time synchronization devices, dense PMU deployment networks, real-time phase angle monitoring, and automated grid frequency alignment.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33321&type=smp&name=Smart%20Grid%20Synchronization%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Smart Grid Synchronization Market Growth Drivers: What’s Behind The Acceleration?

    The increasing integration of smart meters is anticipated to fuel expansion within the smart grid synchronization market. These electronic devices are designed to automatically measure and transmit real-time data on electricity, gas, or water consumption directly to utility providers, facilitating precise billing and effective energy management. Their growing prevalence stems from initiatives promoting energy efficiency, given that smart meters offer immediate usage insights, empowering consumers to cut down on consumption and enabling utilities to refine grid operations, thereby reducing expenses and ecological footprint. Crucially, Smart Grid Synchronization facilitates this by ensuring seamless communication between smart meters and the grid infrastructure, which in turn supports automated energy management systems, minimizes power interruptions, and enhances the efficiency of power distribution. As an illustration, figures from Gov.uk, a UK-based government body, indicate that in Q3 2025, major energy suppliers throughout Great Britain deployed a combined total of 680,000 smart and advanced meters, as reported in November 2025. Consequently, the expanding deployment of smart meters is a significant factor propelling the smart grid synchronization market’s growth.

    Smart Grid Synchronization Market Segments: Where Is Growth Concentrated?

    The smart grid synchronization market covered in this report is segmented –

    1) By Component: Hardware; Software; Services

    2) By Deployment: On-Premises; Cloud; Hybrid

    3) By Technology: Phasor Measurement Units; Synchrophasors; Digital Fault Recorders; Smart Meters; Other Technologies

    4) By Application: Transmission; Distribution; Generation; Other Applications

    5) By End-User: Utilities; Industrial; Commercial; Residential; Other End-Users

    Subsegments:

    1) By Hardware: Smart Meters; Sensors; Controllers; Communication Devices; Energy Storage Systems

    2) By Software: Grid Management Software; Data Analytics Platforms; Monitoring and Control Software; Predictive Maintenance Software; Energy Optimization Software

    3) By Services: Installation Services; Integration Services; Consulting Services; Maintenance Services; Training and Support Services

    Smart Grid Synchronization Market Trends: What’s Defining The Industry’s Next Phase?

    Leading companies in the smart grid synchronization market are prioritizing the development of inventive solutions, such as precision time synchronization technologies, to address the escalating need for improved grid reliability, interoperability, and resilient digital power infrastructure. Precision Time Synchronization technologies are defined as methods that accurately align clocks across devices or systems with microsecond or nanosecond precision, enabling coordinated operations within networks, industrial systems, and critical applications. For example, in December 2025, Siemens AG, a Germany-based industrial automation and power systems technology company, introduced the siprotec 5 precision time protocol (PTP) grandmaster clock (GMC), specifically designed to reinforce digital substations and critical grid infrastructure. The Siprotec 5 PTP GMC incorporates Precision Time Protocol (IEEE 1588v2) grandmaster capabilities alongside enhanced cybersecurity features, including strict separation of process bus and station bus networks and patent-pending seamless grandmaster changeover technology to maintain continuous synchronization without disruptive time jumps during clock transitions. This particular innovation facilitates resilient, fail-safe time coordination, which is vital for modern smart grids, enhances protection functions against disturbances, and strengthens overall grid reliability.

    Smart Grid Synchronization Market Key Players Shaping Industry Direction

    Major companies operating in the smart grid synchronization market are Siemens AG., Hitachi Energy Ltd., Cisco Systems Inc., Oracle Corporation, Schneider Electric SE, Honeywell International Inc., ABB Ltd., Eaton Corporation plc., Quanta Technology LLC, Prysmian Group, Emerson Electric Co., Fluence Energy Inc., Itron Inc., Schweitzer Engineering Laboratories Inc., Landis+Gyr Group AG., Bentley Systems Incorporated, Crompton Greaves, S&C Electric Company, Kamstrup A/S, ETAP, Toshiba Corporation, and General Electric Company.

    View The Full Smart Grid Synchronization Market Report:

    https://thebusinessresearchcompany.com/report/smart-grid-synchronization-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Smart Grid Synchronization Market Regional Analysis: Which Geography Leads On Revenue?

    North America was the largest region in the smart grid synchronization market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the smart grid synchronization market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model