Blog

  • Power Quality as a Service Market Forecast Highlights A $3.36 Billion Opportunity For Industry Participants

    Power Quality as a Service Market Forecast Highlights A $3.36 Billion Opportunity For Industry Participants

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Power Quality as a Service Market Forecast: What Value Will The Market Reach By 2030?

    The power quality as a service market has experienced substantial growth in recent years. It is projected to increase in value from $1.91 billion in 2025 to $2.14 billion in 2026, exhibiting a compound annual growth rate (CAGR) of 11.7%. Historically, this market expansion has been driven by factors such as a rise in grid disturbances, the proliferation of sensitive electronic equipment, the broadening scope of industrial automation, the implementation of stricter power quality standards, and a heightened awareness of downtime costs.

    The power quality as a service market size is anticipated to undergo rapid expansion in the upcoming years. It is forecast to grow to $3.36 billion in 2030, achieving a compound annual growth rate (CAGR) of 12.0%. This projected growth can be linked to the broadening of smart grids, the increasing presence of distributed energy resources, a heightened demand for uptime guarantees, the integration of predictive maintenance analytics, and service-based electrical infrastructure models. Significant trends for the forecast period encompass subscription-based power quality agreements, remote oversight of electrical assets, outcome-based service level contracts, platforms for predictive fault detection, and unified compliance reporting tools.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=28114054&type=smp&name=Power%20Quality%20as%20a%20Service%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Power Quality as a Service Market Growth Catalysts And Demand Drivers

    The Power Quality as a Service market is projected to expand throughout the forecast period due to the increasing integration of electric vehicles (EVs). The growing adoption of EVs primarily stems from the imperative to decrease greenhouse gas emissions and move towards more sustainable options for transportation, away from fossil fuels. As EV uptake rises, the proliferation of fast-charging and high-capacity charging facilities intensifies the strain on electrical grids, leading to problems like voltage instability, harmonic distortions, and other power quality disturbances. Power Quality as a Service effectively tackles these issues by guaranteeing consistent and dependable power supply for EV charging networks, thereby reducing operational interruptions, safeguarding delicate charging equipment, and enhancing overall system performance. This dependable power delivery is crucial for the extensive implementation and functioning of public and commercial EV charging infrastructure. For example, Bloomberg L.P. revealed in January 2026 that global EV passenger vehicle sales reached approximately 22 million units in 2025, marking a 23% year-over-year increase. Consequently, the increasing adoption of electric vehicles (EVs) is a key factor propelling the growth of the power quality as a service market.

    Power Quality as a Service Market Segments: Where Is Growth Concentrated?

    The power quality as a service market covered in this report is segmented –

    1) By Solution Type: Voltage Control; Harmonic Filtering; Power Monitoring; Power Conditioning; Other Solution Types

    2) By Service Model: Consulting; Implementation And Integration; Support And Maintenance; Managed Services

    3) By End-User: Industrial; Commercial; Utilities; Other End-Users

    Subsegments:

    1) By Voltage Control: Automatic Voltage Regulators; Tap Changers; Voltage Stabilizers; Load Shedding Devices

    2) By Harmonic Filtering: Active Harmonic Filters; Passive Harmonic Filters; Hybrid Harmonic Filters; Tuned Harmonic Filters

    3) By Power Monitoring: Real Time Monitoring Systems; Energy Meters; Power Quality Analyzers; Remote Monitoring Solutions

    4) By Power Conditioning: Uninterruptible Power Supplies; Static Transfer Switches; Surge Protection Devices; Voltage Conditioners

    5) By Other Solution Types: Reactive Power Compensation; Frequency Regulation Devices; Energy Storage Systems; Custom Power Solutions

    Power Quality as a Service Market Trends Shaping Long-Term Demand

    Major companies operating in the power quality as a service market are concentrating on developing innovative solutions, such as AI-driven power monitoring services, to facilitate real-time identification of power disturbances, enhance energy performance, and avert expensive equipment failures. These AI-driven power monitoring services employ artificial intelligence and sophisticated analytics for continuous real-time tracking, analysis, and management of electrical power quality. As an example, in February 2026, Ubicquia, Inc., a US-based technology company, introduced AI-driven power monitoring services tailored for commercial and industrial clients, offered as a service without any initial capital investment. Powered by its UbiVu analytics platform, this offering delivers 24/7 real-time monitoring, visibility, and predictive insights to pinpoint and prevent power quality problems that could result in outages, equipment damage, and operational downtime. Created for critical environments like manufacturing facilities, data centers, logistics hubs, and telecommunications infrastructure, the service aids businesses in mitigating operational and financial risks linked to inadequate power quality.

    Power Quality as a Service Market Competitive Landscape: Which Companies Lead The Industry?

    Major companies operating in the power quality as a service market are Siemens AG, Honeywell International Inc., Schneider Electric SE, ABB Ltd, GE Vernova, Hitachi Energy, Eaton Corporation plc, Mitsubishi Electric Corporation, Enel X, Rockwell Automation, Emerson Electric Co., Vertiv Holdings Co., Delta Electronics Inc., Huawei Technologies Co. Ltd, S&C Electric Company, Schweitzer Engineering Laboratories (SEL), Fluke Corporation (Fortive), Cummins Inc.

    View The Full Power Quality as a Service Market Report:

    https://thebusinessresearchcompany.com/report/power-quality-as-a-service-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Power Quality as a Service Market Regional Breakdown: Where Is Demand Concentrated?

    North America was the largest region in the power quality as a service market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the power quality as a service market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Porcelain Market Outlook Through 2030: Understanding The Growth Opportunity

    Porcelain Market Outlook Through 2030: Understanding The Growth Opportunity

    Featuring market attractiveness scoring, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, deeper supply chain intelligence, emerging startup tracking, and granular product-level insights, The Business Research Company’s 2026 market reports are built to deliver research that is both more actionable and more strategically valuable.

    Porcelain Market Size, Value And Growth Trajectory Through 2030

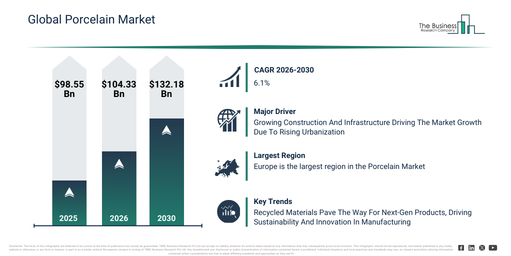
    The porcelain market has experienced robust expansion over recent years. It is anticipated to grow from $98.55 billion in 2025 to $104.33 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 5.9%. This past growth can be attributed to factors such as rapid urbanization and infrastructure development, an increase in residential and commercial construction, the expansion of the hospitality and food service industry, a rising demand for household ceramic products, and the growth in power transmission networks.

    The porcelain market is projected to experience substantial expansion in the coming years. This market is anticipated to reach a valuation of $132.18 billion by 2030, demonstrating a compound annual growth rate (CAGR) of 6.1%. This growth during the forecast period is primarily driven by factors such as the integration of smart manufacturing within ceramic production, an increasing need for environmentally friendly materials, the expansion of high-performance industrial ceramics, the enlargement of healthcare and laboratory infrastructure, and a rise in expenditure on premium home renovations. Key trends expected within this period encompass the use of premium porcelain for interior designs, the widespread uptake of highly durable sanitaryware, the broadening application of technical and laboratory porcelain, advancements in decorative and artistic porcelain, and the ongoing development of sophisticated surface finishes and coatings.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=97117093&type=smp&name=Porcelain%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Porcelain Market Growth Momentum: What Factors Are Shaping Demand?

    Increased activity in construction and infrastructure is anticipated to drive the expansion of the porcelain market in the foreseeable future. This sector encompasses the development of residential, commercial, and industrial buildings, as well as public works such as transportation networks and utilities. The expansion of construction activity is fueled by rapid urbanization, as growing cities require new housing, commercial spaces, and infrastructure to support increasing populations. Consequently, this directly boosts the demand for porcelain tiles and fixtures, extensively utilized for flooring, wall cladding, countertops, and bathroom installations across residential, commercial, and various infrastructure projects. As an illustration, according to data published by the UK Office for National Statistics (ONS), total general government investment in infrastructure in the UK increased by 2.2% in 2024 to $38.54 billion (£28.9 billion), compared with 2023. Therefore, expanding construction and infrastructure activity stands as a key factor fostering the growth of the porcelain market.

    Porcelain Market Segment Breakdown: Which Categories Lead On Revenue?

    The porcelain market covered in this report is segmented –

    1) By Primary Product: Porcelain Tiles; Porcelain Sanitaryware; Porcelain Tableware And Kitchenware; Electrical Porcelain; Technical Or Industrial Porcelain; Decorative And Artistic Porcelain

    2) By Insulator Shape: Pin Insulators; Round Insulators; Disc Insulators; Other Insulator Shapes

    3) By Material Grade Or Type: Glazed Porcelain; Un-Glazed Or Full-Body Porcelain; Fine Bone China; Technical Or High-Alumina Porcelain

    4) By Distribution Channel: Direct Sales Or Business To Business (B2B); Distributors And Wholesalers; Retail; E-commerce And Direct-To-Consumer (D2C)

    5) By End-User: Building And Construction; Food Service And Hospitality (HORECA); Consumer And Retail; Utilities And Energy; Industrial And Manufacturing; Healthcare And Laboratories

    Subsegments:

    1) By Porcelain Tiles: Floor Tiles; Wall Tiles; Mosaic Tiles

    2) By Porcelain Sanitaryware: Toilets; Basins; Urinals; Bidets

    3) By Porcelain Tableware And Kitchenware: Plates; Bowls; Cups And Mugs; Cookware Sets; Serving Dishes

    4) By Electrical Porcelain: Pin Insulators; Disc Insulators; Post Insulators; Bushings; Connectors

    5) By Technical Or Industrial Porcelain: Laboratory Ware; Chemical Ware; Medical Components; High-Alumina Porcelain Components

    6) By Decorative And Artistic Porcelain: Figurines; Vases; Sculptures; Decorative Plates; Art Pieces

    Porcelain Market Trends Redefining Industry Growth

    Leading firms within the porcelain sector are prioritizing the creation of novel offerings, including environmentally friendly recycled porcelain tiles, to address sustainability requirements and appeal to consumers concerned about the environment. These eco-conscious tiles are produced by repurposing broken or surplus porcelain and various other substances, thereby contributing to waste reduction, natural resource preservation, and a diminished environmental footprint. A notable illustration is RAK Ceramics, a ceramics manufacturing company based in the UAE, which in June 2025 introduced the globe’s inaugural RE-USE tiles, crafted entirely from 100% pre-consumer recycled content. These specific tiles integrate the durability and aesthetic appeal of traditional porcelain with a completely sustainable makeup, providing excellent resistance to scratches and stains, minimal porosity, and flexible design choices suitable for both home and business settings. By utilizing recycled materials, the product substantially decreases the carbon emissions linked to tile manufacturing, all while maintaining its high quality and effectiveness. The tiles are perfectly suited for flooring, wall coverings, and diverse interior and exterior architectural purposes, thereby fostering circular economy principles within the ceramics industry.

    Porcelain Market Company Landscape And Competitive Strategy

    Major companies operating in the porcelain market are Mohawk Industries Inc., Porcelanosa Grupo, Noritake Co. Ltd., Villeroy & Boch AG, RAK Ceramics PJSC, H&R Johnson (India) Pvt. Ltd., Duravit AG, LLADRÓ S.A., Churchill China plc, Meissen Porcelain Manufactory, Imperial Porcelain Factory, Dankotuwa Porcelain PLC, Herend Porcelain Manufactory Ltd., Bernardaud, Richard Ginori S.p.A., NARUMI CORPORATION, SCG Ceramics Public Company Limited, Ceramiche Atlas Concorde S.p.A., Haviland & Co., Manufacture Nationale de Sèvres

    View The Full Porcelain Market Report:

    https://thebusinessresearchcompany.com/report/porcelain-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Porcelain Market Largest Region: Which Geography Holds The Highest Market Share?

    Europe was the largest region in the porcelain market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the porcelain market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Pole Attachment Management Market Growth Outlook: Why Analysts Expect Continued Expansion

    Pole Attachment Management Market Growth Outlook: Why Analysts Expect Continued Expansion

    Backed by market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, wider supply chain intelligence, emerging startup coverage, and detailed product-level insights, The Business Research Company’s 2026 market reports are designed to offer research that is more actionable and strategically valuable than ever.

    Pole Attachment Management Market Set To Climb From $3.7 Billion In 2026 To $5.59 Billion By 2030

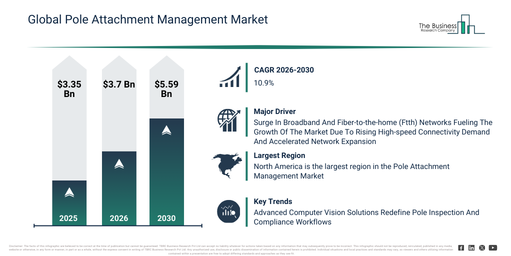
    The pole attachment management market has experienced significant growth in recent years. It is projected to increase from $3.35 billion in 2025 to $3.7 billion in 2026, reflecting a compound annual growth rate (CAGR) of 10.6%. This historical expansion can be attributed to several factors including telecom network expansion, a rise in pole sharing agreements, the swift deployment of cable and broadband services, challenges associated with manual record management, and regulatory documentation requirements.

    The pole attachment management market is projected to experience substantial expansion in the coming years. Its valuation is anticipated to reach $5.59 billion by 2030, exhibiting a compound annual growth rate (CAGR) of 10.9%. This projected growth over the forecast period can be linked to factors such as 5G and fiber optic network densification, the proliferation of smart grid initiatives, an escalating demand for compliance automation tools, greater adoption of cloud platforms, and the necessity for predictive infrastructure analysis. Key developments expected during this period involve AI-powered pole inspection analytics, automated inventory mapping for attachments, cloud-based platforms for pole assets, predictive maintenance strategies for pole networks, and GIS-integrated attachment tracking.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33265&type=smp&name=Pole%20Attachment%20Management%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Pole Attachment Management Market Development Factors: What’s Supporting Demand?

    The expansion of broadband and fiber-to-the-home (FTTH) networks is projected to drive the future growth of the pole attachment management market. Broadband and fiber-to-the-home (FTTH) are high-speed internet services that utilize fiber-optic cables to provide direct and reliable data transmission to homes. This surge in broadband and FTTH rollout stems from increasing consumer demand for rapid connectivity and government initiatives that fund network expansion. Pole attachment management facilitates broadband deployment by allowing utility and communications firms to effectively coordinate and oversee the increasing volume of attachments on utility poles, thus minimizing delays, ensuring regulatory adherence, and streamlining maintenance as networks grow. As an illustration, in January 2025, the Fiber Broadband Association, a US-based fiber broadband advocacy organization, reported that fiber broadband deployments reached an unprecedented 10.3 million homes in 2024, a notable increase from approximately 9 million in 2023, demonstrating robust annual expansion in network implementation. Consequently, the expanding deployment of broadband and fiber-to-the-home (FTTH) networks is fueling the expansion of the pole attachment management market.

    Pole Attachment Management Market Segment Trends And Revenue Contributors

    The pole attachment management market covered in this report is segmented –

    1) By Component: Software; Hardware; Services

    2) By Deployment Mode: On Premises; Cloud

    3) By Enterprise Size: Small And Medium Enterprises; Large Enterprises

    4) By Application: Utility Management; Telecommunications; Broadband; Cable Television; Other Applications

    5) By End User: Electric Utilities; Telecom Operators; Internet Service Providers; Cable Companies; Other End Users

    Subsegments:

    1) By Software: Operating System Software; Communication Management Software; Application Software; Security And Encryption Software; Cloud-Based Push-To-Talk Platforms

    2) By Hardware: Handheld Devices; Vehicle-Mounted Devices; Wearable Devices; Network Infrastructure; Accessories And Peripherals

    3) By Services: Installation Services; Maintenance Services; Training Services; Consulting Services; Support And Troubleshooting Services

    Pole Attachment Management Market Transformation Trends: What Innovations Are Driving Change?

    Leading companies operating in the pole attachment management market are focusing on advancing artificial intelligence (AI)-driven automation capabilities to improve pole inspection accuracy, minimize manual errors, and accelerate asset management workflows. Automated pole intelligence refers to the use of artificial intelligence to identify pole-mounted equipment, measure attachment heights, and streamline annotation processes, enabling utilities and engineering teams to prioritize inspections and strengthen regulatory compliance. For instance, in October 2025, ikeGPS, a US-based infrastructure data solutions company, introduced PolePilot, a next-generation AI-driven pole management solution designed to streamline utility pole analysis. The platform leverages advanced computer vision and machine learning algorithms to automatically identify pole-mounted equipment and precisely measure attachment heights from field imagery. By eliminating manual interpretation, PolePilot significantly reduces analysis time and human error. It also features integrated annotation and validation workflows, enabling faster data review and standardization across projects. As a result, the solution enhances operational efficiency, data accuracy, and scalability in utility pole and pole attachment management processes.

    Pole Attachment Management Market Competitive Analysis Of Leading Industry Participants

    Major companies operating in the pole attachment management market are AT&T Inc., MasTec Inc., Crown Castle International Corp., Black & Veatch Corporation, Millennium Geospatial, Trimble Inc., Osmose Utilities Services Inc., SBA Communications Corporation, Esri Ltd, Bentley Systems Incorporated, OFS Fitel LLC, Aclara Technologies LLC, Utility Data Contractors Inc., National Information Solutions Cooperative (NISC), Katapult Engineering, IQGeo Group plc, VETRO FiberMap, EN Engineering, GeoSpatial Innovations Inc. (GSI), and Aerial Data Service Inc.

    View The Full Pole Attachment Management Market Report:

    https://thebusinessresearchcompany.com/report/pole-attachment-management-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Pole Attachment Management Market Geographic Distribution And Regional Opportunities

    North America was the largest region in the pole attachment management market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the pole attachment management market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Physical Security Information Management (PSIM) Playbook Orchestration Market Explained: What Is Fueling Growth To $4.05 Billion By 2030?

    Physical Security Information Management (PSIM) Playbook Orchestration Market Explained: What Is Fueling Growth To $4.05 Billion By 2030?

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Physical Security Information Management (PSIM) Playbook Orchestration Market Revenue Growth On Track For A 12.3% CAGR Through 2030

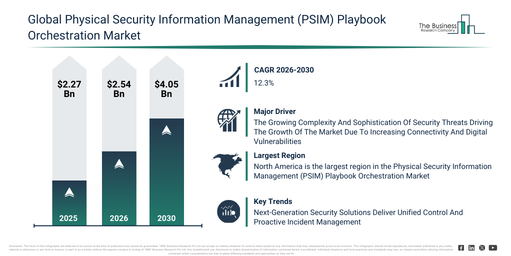
    The market size for physical security information management (psim) playbook orchestration has seen rapid expansion in recent years. It is anticipated to increase from $2.27 billion in 2025 to $2.54 billion in 2026, exhibiting a compound annual growth rate (CAGR) of 12.1%. Factors contributing to its growth in past periods include the rise in integrated security systems, the growth of surveillance networks, the expansion of security operation centers, an increase in critical infrastructure threats, and the adoption of PSIM platforms.

    The physical security information management (psim) playbook orchestration market size is projected for significant expansion in the coming years. This market is anticipated to reach $4.05 billion by 2030, exhibiting a compound annual growth rate (CAGR) of 12.3%. Factors contributing to this growth during the forecast period include the rise in smart city security initiatives, an increase in multi-sensor deployments, a greater need for quicker incident response, the expansion of automated security workflows, and heightened demands for protecting critical assets. Key trends expected throughout this period encompass automated incident response playbooks, cross-system security orchestration, real-time event correlation engines, AI-driven threat workflows, and unified security command platforms.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33263&type=smp&name=Physical%20Security%20Information%20Management%20%28PSIM%29%20Playbook%20Orchestration%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Physical Security Information Management (PSIM) Playbook Orchestration Market Growth Factors: What’s Supporting Expansion?

    The increasing intricacy and advanced nature of security threats are anticipated to fuel expansion within the physical security information management (PSIM) playbook orchestration market in the future. Security threats refer to possible incidents or deeds, whether deliberate or unintentional, capable of harming individuals, assets, systems, or data, thereby jeopardizing safety, operational continuity, or data integrity. This rise in complexity and sophistication stems from heightened connectivity and ongoing digital transformation, as an increasing number of devices, systems, and data points become interconnected, enlarging potential attack vectors and generating novel weaknesses for cybercriminals to leverage. Physical security information management playbook orchestration addresses these threats by automating responses to incidents, integrating data from diverse systems, and directing teams through consistent operational procedures, thus ensuring quicker, harmonized, and more impactful mitigation efforts. As an illustration, during October 2025, data from the Australian Signals Directorate, a government body based in Australia, indicated that in FY2024–25, its Australian Cyber Security Centre (ACSC) processed more than 42,500 calls to the Australian Cyber Security Hotline, which represented a 16% increase compared to the prior year. Consequently, the increasing intricacy and advanced nature of security threats are propelling the expansion of the physical security information management (PSIM) playbook orchestration market.

    Physical Security Information Management (PSIM) Playbook Orchestration Market Segment Performance And Emerging Opportunities

    The physical security information management (psim) playbook orchestration market covered in this report is segmented –

    1) By Component: Software; Hardware; Services

    2) By Deployment Mode: On-Premises; Cloud-Based

    3) By Application: Incident Management; Security Operations; Compliance Management; Workflow Automation; Other Applications

    4) By End-User: Banking Financial Services And Insurance; Government And Defense; Transportation; Healthcare; Energy And Utilities; Commercial; Other End-Users

    Subsegments:

    1) By Software: Incident Workflow Orchestration Software; Playbook Automation Platforms; Event Correlation Software; Decision Support Software; Integration And Interface Software

    2) By Hardware: Command Center Servers; Video Wall Controllers; Network Processing Units; Edge Computing Devices

    3) By Services: System Integration Services; Playbook Configuration Services; Training And Enablement Services; Managed Orchestration Services; Support And Maintenance Services

    Physical Security Information Management (PSIM) Playbook Orchestration Market Industry Trends: What’s Reshaping Demand?

    Leading companies in the physical security information management (PSIM) playbook orchestration market are prioritizing the development of AI-enhanced 3D LiDAR surveillance. This effort aims to elevate real-time situational awareness, streamline incident response, and facilitate proactive, data-driven security management across intricate environments. AI-enhanced 3D LiDAR surveillance functions as a security technology, utilizing 3D LiDAR sensors for real-time object detection and tracking. Its integrated AI algorithms analyze this data to ensure accurate intrusion detection, object classification, and comprehensive situational awareness, even in low-light or complex settings. For instance, in March 2025, Hexagon AB, a Sweden-based digital reality technology company, unveiled HxGN dC3 Orchestrator, expanding its HxGN dC3 portfolio with an advanced PSIM and incident management platform. This solution consolidates and correlates data from various security sensors and third-party systems into a singular operational view, simultaneously enabling automated workflows, guidance based on standard operating procedures (SOPs), and cross-functional collaboration throughout an incident’s entire lifecycle. It incorporates GIS-based visualization, real-time data fusion, automated escalation, compliance reporting, and mobile access, thereby extending orchestration capabilities beyond the control room. Designed specifically for corporate campuses, airports, critical infrastructure, and financial institutions, the platform distinguishes itself from traditional PSIM tools by embedding digitized standard operating procedures and automated escalation policies, which ensures process consistency and delivers a faster, more efficient incident response.

    Physical Security Information Management (PSIM) Playbook Orchestration Market Industry Leaders And Competitive Landscape

    Major companies operating in the physical security information management (psim) playbook orchestration market are Siemens AG, International Business Machines Corporation, Cisco Systems Inc., Honeywell International Inc., Johnson Controls International plc, Motorola Solutions Inc., Hexagon AB, Bosch Sicherheitssysteme GmbH, Verint Systems Inc., Everbridge Inc, Genetec Inc., AxxonSoft Co Ltd., Eagle Eye Networks Inc, Primion Technology GmbH, Advancis Software & Services GmbH, Nice Ltd., Nanodems Corporation, Prysm Software Inc, SureView Systems Inc., and octopus system Pvt. Ltd.

    View The Full Physical Security Information Management (PSIM) Playbook Orchestration Market Report:

    https://thebusinessresearchcompany.com/report/physical-security-information-management-psim-playbook-orchestration-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Physical Security Information Management (PSIM) Playbook Orchestration Market Regional Analysis And Leading Geography

    North America was the largest region in the physical security information management (PSIM) playbook orchestration market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the physical security information management (psim) playbook orchestration market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Phone Local Large Language Model Market Forecast To Reach $13.98 Billion By 2030: Key Trends Explained

    Phone Local Large Language Model Market Forecast To Reach $13.98 Billion By 2030: Key Trends Explained

    Backed by market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, wider supply chain intelligence, emerging startup coverage, and detailed product-level insights, The Business Research Company’s 2026 market reports are designed to offer research that is more actionable and strategically valuable than ever.

    Phone Local Large Language Model Market Value Growth And Long-Term Outlook

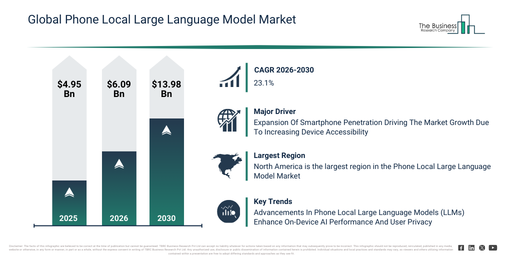
    The market size for phone local large language models has expanded exponentially in recent years. It is projected to increase from $4.95 billion in 2025 to $6.09 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 22.9%. The growth observed in the historical period stems from factors such as the development of smartphone AI chips, increasing privacy concerns, the proliferation of mobile AI applications, enhancements in model compression, and the demand for offline features.

    The phone local large language model market is projected to experience substantial expansion over the upcoming years. It will grow to $13.98 billion in 2030 at a compound annual growth rate (CAGR) of 23.1%. This expansion during the projected period stems from several factors, including the rising adoption of edge AI, an increase in mobile AI workloads, stricter data privacy regulations, the proliferation of on-device copilots, and innovations in lightweight transformer models. Key developments anticipated during this timeframe encompass on-device language inference, more compact mobile LLM architectures, AI assistant models that function offline, language engines optimized for edge devices, and secure environments for running local models.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=77561098&type=smp&name=Phone%20Local%20Large%20Language%20Model%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Phone Local Large Language Model Market Demand Drivers: What’s Powering Industry Growth?

    The advancement in smartphone penetration is anticipated to stimulate the expansion of the phone local large language model market in the future. Smartphone penetration signifies the proportion of the population that possesses and actively utilizes smartphones with internet connectivity. The upward trend in smartphone penetration is largely fueled by the growing affordability of devices and mobile data plans, as technological progress and competition among manufacturers have led to cost reductions while simultaneously enhancing smartphone capabilities and accessibility worldwide. This surge in smartphone penetration consequently generates demand for phone local large language models, as an increasing number of users gain access to devices capable of performing on-device AI processing for functionalities such as personalized assistance, privacy-enhanced computing, and intelligent offline features. As a specific illustration, in November 2023, the International Telecommunication Union, a Switzerland-based UN specialized agency for information and communication technologies, indicated that global smartphone subscriptions grew from 8.6 billion in 2022 to 8.9 billion in 2023, representing an increase of 300 million subscriptions. Consequently, the increasing reach of smartphone penetration is a key driver for the growth of the phone local large language model market.

    Phone Local Large Language Model Market Segment Landscape And Growth Outlook

    The phone local large language model market covered in this report is segmented –

    1) By Type: Software; Hardware

    2) By Technology: Deep Learning; Natural Language Processing; Machine Learning

    3) By Deployment Model: On-Premises; Cloud-Based; Hybrid

    4) By Application: Virtual Assistants; Content Generation; Other Applications

    5) By End User: Individuals; Small And Medium Enterprises; Large Enterprises

    Subsegments:

    1) By Software: Mobile Applications; Application Programming Interface Services; Model Optimization Tools; On-Device Inference Frameworks; Software Development Kits

    2) By Hardware: Smartphone Processors; Neural Processing Units; Artificial Intelligence Accelerators; Memory And Storage Modules; Edge Computing Devices

    Phone Local Large Language Model Market Innovation Trends: What Developments Are Reshaping The Industry?

    Leading companies active in the phone local large language model (LLM) market are concentrating on developing advanced large-scale language models to facilitate real-time, on-device AI functionalities. A large-scale language model is an intricate AI system, trained on vast quantities of data to effectively understand, produce, and interpret human language with considerable accuracy and contextual insight. For instance, in December 2023, Google, a US-based technology company, launched Gemini Nano, a compact, on-device, large-scale language model specifically designed to operate locally on supported smartphones, including the Pixel 8 Pro with Android AI Core integration. It is developed to enhance mobile AI experiences, enabling features such as instant Smart Reply generation in Gboard, direct-device speech transcription and summarization in the Recorder app, and local inference without network connectivity, thereby boosting user privacy and decreasing service costs in comparison to cloud-based AI models.

    Phone Local Large Language Model Market Key Participants And Competitive Landscape

    Major companies operating in the phone local large language model market are Microsoft Corporation, Samsung Electronics Co. Ltd., ByteDance Ltd., Meta Platforms Inc, Qualcomm Incorporated, Nvidia Corporation, Baidu Inc., OpenAI Inc., Cohere Inc., AI21 Labs Ltd., Hugging Face Inc., Liquid AI Inc., Sensory Inc., deepset GmbH, Picovoice Inc., Sarvam AI Private Limited, Adaptive ML Inc., WebAI Inc., MLC AI Inc., and Nexa AI Inc.

    View The Full Phone Local Large Language Model Market Report:

    https://thebusinessresearchcompany.com/report/phone-local-large-language-model-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Phone Local Large Language Model Market Geographic Analysis: Where Is Demand Accelerating Fastest?

    North America was the largest region in the phone local large language model market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the phone local large language model market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Pharmaceutical Validation Services Market Analysis: Understanding The Drivers Behind 7.2% CAGR Through 2030 Growth

    Pharmaceutical Validation Services Market Analysis: Understanding The Drivers Behind 7.2% CAGR Through 2030 Growth

    Featuring market attractiveness scoring, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, deeper supply chain intelligence, emerging startup tracking, and granular product-level insights, The Business Research Company’s 2026 market reports are built to deliver research that is both more actionable and more strategically valuable.

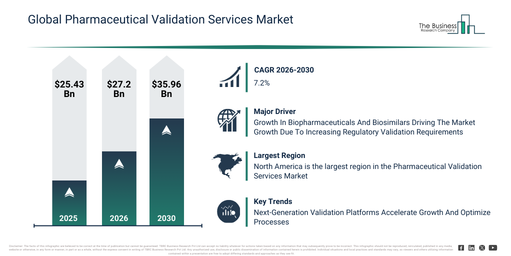
    Pharmaceutical Validation Services Market Poised To Hit $35.96 Billion By 2030 With A 7.2% CAGR

    The pharmaceutical validation services market has shown significant expansion in recent years. This market is projected to expand from $25.43 billion in 2025 to $27.2 billion in 2026, achieving a compound annual growth rate (CAGR) of 7.0%. The upward trend observed historically is due to more rigorous regulatory compliance norms, an increase in gmp facilities, advancements in pharma automation, a rise in audit observations, and a greater need for validation documentation.

    The pharmaceutical validation services market is projected to undergo significant expansion in the coming years. Its valuation is set to reach $35.96 billion in 2030, exhibiting a compound annual growth rate (CAGR) of 7.2%. This growth during the forecast period is driven by factors such as the increase in advanced therapy manufacturing, the broadening of continuous manufacturing, more stringent data integrity enforcement, a rise in biologics facility construction, and the need for lifecycle validation programs. Noteworthy trends anticipated in this period include digital validation documentation, automated equipment qualification, remote validation audits, integrated process validation suites, and data integrity validation platforms.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33261&type=smp&name=Pharmaceutical%20Validation%20Services%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Pharmaceutical Validation Services Market Growth Drivers: What’s Behind The Acceleration?

    The anticipated expansion in biopharmaceuticals and biosimilars is projected to fuel the advancement of the pharmaceutical validation services market moving ahead. These therapeutic products, sourced from biological materials, necessitate extensive testing and validation procedures to guarantee their safety and effectiveness. The proliferation of biopharmaceuticals and biosimilars stems from the rising occurrence of chronic and intricate diseases, which demand sophisticated, targeted treatments beyond the scope of conventional small-molecule medications. Pharmaceutical validation services play a crucial role in assuring the quality, safety, and effectiveness of biopharmaceuticals and biosimilars by systematically confirming that production processes, equipment, and analytical techniques consistently yield products adhering to strict regulatory benchmarks, thus facilitating dependable scaling, regulatory endorsement, and patient confidence in these intricate biological treatments. For example, data from Cardinal Health Inc., a US-based healthcare firm, reported in January 2023, indicated that as of January 2022, the FDA had cleared 33 biosimilar products in the US, with 21 already commercialized. By 2023, the count of FDA-approved biosimilars climbed to 40, with 25 accessible in the market. Consequently, the expansion in biopharmaceuticals and biosimilars is propelling the growth of the pharmaceutical validation services market.

    Pharmaceutical Validation Services Market Breakdown By Product Type And Application

    The pharmaceutical validation services market covered in this report is segmented –

    1) By Service Type: Installation Qualification; Operational Qualification; Performance Qualification; Revalidation

    2) By Product Type: Active Pharmaceutical Ingredient Validation; Finished Pharmaceutical Product Validation; Biologics and Biosimilars Validation; Medical Device Validation

    3) By Delivery Mode: Onsite Validation Services; Remote Validation Services

    4) By End-User: Pharmaceutical Manufacturers; Biopharmaceutical Companies; Contract Development and Manufacturing Organizations; Contract Research Organizations

    Subsegments:

    1) By Installation Qualification: Equipment Installation Verification; Utility Connection Verification; Component Identification and Documentation; Calibration Verification; Safety Compliance Verification

    2) By Operational Qualification: Operational Parameter Testing; Alarm and Control Verification; Standard Operating Procedure Verification; Process Control Testing; Worst Case Condition Testing

    3) By Performance Qualification: Process Consistency Verification; Product Quality Performance Testing; Long Term Process Monitoring; Batch Reproducibility Assessment; End Use Performance Validation

    4) By Revalidation: Periodic Revalidation; Change Control Based Revalidation; Equipment Modification Revalidation; Process Change Revalidation; Regulatory Compliance Revalidation

    Pharmaceutical Validation Services Market Trends: What’s Defining The Industry’s Next Phase?

    Leading companies within the pharmaceutical validation services market are concentrating on developing advanced solutions, such as artificial intelligence (AI)-powered digital validation platforms, to optimize compliance, minimize human errors, and speed up product approval processes. These AI-enabled digital validation platforms are software systems that utilize artificial intelligence to automate and integrate validation workflows, thereby helping to reduce manual inaccuracies, guarantee regulatory adherence, and accelerate documentation and approval cycles. For instance, in June 2025, ValGenesis Inc., a US–based digital validation lifecycle management company, launched ValGenesis Smart GxP. This innovative AI-enabled platform is designed to unify validation and process development across the entire product lifecycle, integrating multiple applications like iVal, iClean, and iOps to automate commissioning, qualification, cleaning validation, and real-time operational data capture. Its AI assistant achieves up to 80% faster document generation and reduces review cycles from weeks to hours, while consistently ensuring compliance with global regulatory standards. ValGenesis Smart GxP supports seamless data flow from research and development through commercial manufacturing, enhances visibility and traceability, and accelerates time to market, signifying a major improvement over older systems in terms of efficiency, compliance, and digital integration.

    Pharmaceutical Validation Services Market Top Companies Driving Competitive Growth

    Major companies operating in the pharmaceutical validation services market are Jacobs Engineering Group Inc., Parexel International Corporation, Sartorius AG, ECS Group Ltd., Computer Aid Inc., ZenQ Ltd., PQE Group S.p.A., SQA Services Ltd., PharmEng Technology Inc., Lachman Consultants Pvt. Ltd., Quality by Design Group Ltd., BioPharma Services Inc., ValSource Inc., Körber AG, PharmOut Consulting Ltd., VMP Consulting Pvt. Ltd., GxP Compliance Ltd., Pharmaligent LLC, Farbridge Pharma Consulting Ltd., and Adris Pharma Validation & Compliance Pvt. Ltd.

    View The Full Pharmaceutical Validation Services Market Report:

    https://thebusinessresearchcompany.com/report/pharmaceutical-validation-services-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Pharmaceutical Validation Services Market Global Footprint: Which Region Leads The Industry?

    North America was the largest region in the pharmaceutical validation services market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the pharmaceutical validation services market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Pharmaceutical Analytical Testing Outsourcing Market Trends Reshaping Industry Growth Through 2030

    Pharmaceutical Analytical Testing Outsourcing Market Trends Reshaping Industry Growth Through 2030

    Backed by market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, wider supply chain intelligence, emerging startup coverage, and detailed product-level insights, The Business Research Company’s 2026 market reports are designed to offer research that is more actionable and strategically valuable than ever.

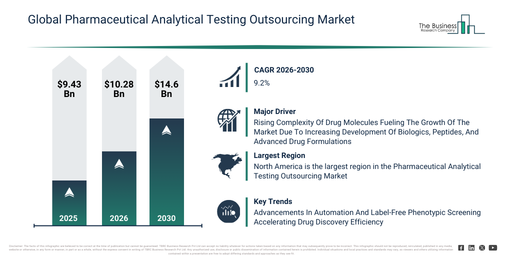
    Pharmaceutical Analytical Testing Outsourcing Market Growth From $10.28 Billion In 2026 To $14.6 Billion By 2030 At A CAGR Of 9.2%

    The pharmaceutical analytical testing outsourcing market has experienced significant expansion in recent years. This market is projected to expand from $9.43 billion in 2025 to $10.28 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 8.9%. The expansion observed in the past can be linked to several key factors, including the increasing complexity of drug development, substantial in-house laboratory expenses, the proliferation of contract research organizations, more stringent regulatory requirements for testing, and the broadening of generic drug pipelines.

    The pharmaceutical analytical testing outsourcing market size is projected to experience substantial expansion over the upcoming years. This market is anticipated to reach $14.6 billion by 2030, exhibiting a compound annual growth rate (CAGR) of 9.2%. The anticipated growth during this period stems from factors such as an increase in biologics and cell therapies, enhanced regulatory oversight, the broadening of virtual pharmaceutical models, a rise in outsourcing by small biotech firms, and the demand for quicker batch release. Key developments expected within this forecast timeframe encompass the emergence of specialized third-party analytical laboratories, the provision of integrated method validation services, advancements in high-throughput bioanalytical testing, the availability of regulatory-ready testing packages, and the widespread adoption of end-to-end quality control outsourcing.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=33259&type=smp&name=Pharmaceutical%20Analytical%20Testing%20Outsourcing%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Pharmaceutical Analytical Testing Outsourcing Market Demand Drivers Opening New Revenue Streams

    The growing intricacy of drug molecules is anticipated to fuel the expansion of the pharmaceutical analytical testing outsourcing market. Drug molecule complexity pertains to the escalating structural, chemical, and functional refinement of contemporary therapeutics, such as biologics, peptides, oligonucleotides, and targeted therapies, necessitating extremely precise characterization and validation. This intricacy stems from progress in specialty and precision medicine, which call for sophisticated analytical methods to guarantee product quality, safety, and adherence to regulations. Given that internal analytical resources frequently find it challenging to satisfy the technical and regulatory requirements of intricate molecules, pharmaceutical firms are progressively depending on specialized external analytical testing providers. Outsourcing offers entry to advanced instrumentation, expert knowledge, and adaptable capacity, which are often unfeasible or excessively expensive to sustain in-house. For instance, data from MedChem Australia, an Australia-based national drug discovery initiative, indicates that approximately 55 new drugs received approval in 2023, with 17 being biologics and 9 categorized as peptide- or oligonucleotide-based therapies (TIDES). These types of treatments demand complex analytical techniques like mass spectrometry, bioassays, and advanced stability testing, thereby boosting the dependence on outsourced analytical services. Consequently, the increasing complexity of drug molecules is propelling the growth of the pharmaceutical analytical testing outsourcing market.

    Pharmaceutical Analytical Testing Outsourcing Market Segmentation And Category Overview

    The pharmaceutical analytical testing outsourcing market covered in this report is segmented –

    1) By Service Type: Method Development and Validation; Stability Testing; Microbial Testing; Raw Material Testing; Other Service Types

    2) By Product Type: Small Molecules and Generics; Biologics and Biosimilars; Cell and Gene Therapies; Vaccines; Medical Devices

    3) By Application: Clinical; Preclinical; Other Applications

    4) By End-User: Pharmaceutical Companies; Biotechnology Companies; Contract Research Organizations; Other End-Users

    Subsegments:

    1) By Method Development and Validation: Analytical Method Development; Analytical Method Validation; Method Transfer Studies; Assay Optimization; Robustness Testing

    2) By Stability Testing: Accelerated Stability Testing; Long Term Stability Testing; Intermediate Stability Testing; Photostability Testing; Stress Stability Testing

    3) By Microbial Testing: Bioburden Testing; Sterility Testing; Endotoxin Testing; Microbial Limits Testing; Environmental Monitoring

    4) By Raw Material Testing: Identity Testing; Purity Testing; Physicochemical Characterization; Impurity Profiling; Supplier Qualification Testing

    5) By Other Service Types: Process Development Support; Regulatory Documentation Support; Quality Control Testing; Batch Release Testing; Technical Consulting

    Pharmaceutical Analytical Testing Outsourcing Market Trends Powering Strategic Industry Growth

    Leading companies in the pharmaceutical analytical testing outsourcing sector are concentrating on advancing automated and digital analytical testing platforms. This focus aims to enhance the accuracy, efficiency, and regulatory compliance of quality control (QC) testing throughout the entire drug development and manufacturing lifecycle. These advancements are intended to improve method robustness, increase throughput, and ensure reliable impurity profiling, identity confirmation, and batch release testing, all in accordance with regulatory requirements. For example, in March 2023, Eurofins Discovery, a US-based contract research organization (CRO), expanded its analytical testing services by introducing automated, label-free mass spectrometry–based analytical platforms. These platforms are designed to support regulated pharmaceutical quality control applications, allowing for high-throughput, reproducible analysis of drug substances and drug products without using fluorescent or radioactive labels, thereby preserving sample integrity and boosting data reliability. These enhanced capabilities support critical QC activities such as impurity detection, identity testing, and method validation, helping pharmaceutical manufacturers meet stringent regulatory standards while also accelerating testing timelines.

    Pharmaceutical Analytical Testing Outsourcing Market Competitive Overview And Top Companies

    Major companies operating in the pharmaceutical analytical testing outsourcing market are Thermo Fisher Scientific Inc., IQVIA Holdings Inc., Laboratory Corporation of America Holdings, ICON plc, SGS Société Générale de Surveillance SA, Eurofins Scientific SE, WuXi AppTec Co. Ltd., Intertek Group plc, Charles River Laboratories International Inc., West Pharmaceutical Services Inc., Element Materials Technology Group Limited, Recipharm AB, Almac Group Limited, Pace Analytical Services LLC, Cotecna Inspection S.A., BioAgilytix Labs LLC, BA Sciences Inc., Toxikon Corporation, Frontage Laboratories Inc., Syngene International Limited

    View The Full Pharmaceutical Analytical Testing Outsourcing Market Report:

    https://thebusinessresearchcompany.com/report/pharmaceutical-analytical-testing-outsourcing-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Pharmaceutical Analytical Testing Outsourcing Market Leading Geography: Which Region Contributes The Most Revenue?

    North America was the largest region in the pharmaceutical analytical testing outsourcing market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the pharmaceutical analytical testing outsourcing market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Personal Computer (PC) Power Policy Management Market Forecast: Breaking Down The Numbers Behind Future Expansion

    Personal Computer (PC) Power Policy Management Market Forecast: Breaking Down The Numbers Behind Future Expansion

    Built to provide research that’s more actionable and strategically valuable, The Business Research Company’s 2026 market reports include market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, broader supply chain intelligence, emerging startup tracking, and in-depth product insights.

    Personal Computer (PC) Power Policy Management Market Growth Potential: How Will Market Size Shift Through 2030?

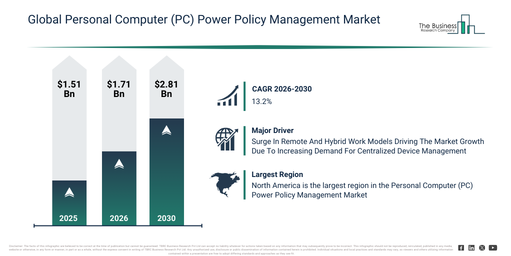
    The personal computer (pc) power policy management market has experienced rapid growth in its size during recent years. It is forecast to increase from $1.51 billion in 2025 to $1.71 billion in 2026, achieving a compound annual growth rate (CAGR) of 12.9%. The market’s historical expansion can be linked to enterprise energy saving initiatives, the proliferation of endpoint management tools, escalating electricity costs, the implementation of green IT programs, and the enlargement of corporate device fleets.

    The personal computer (pc) power policy management market is expected to experience significant growth in the coming years. By 2030, its valuation is projected to reach $2.81 billion, growing at a compound annual growth rate (CAGR) of 13.2%. This growth during the forecast period is driven by factors such as net zero it targets, stricter enterprise energy audits, an increase in remote device management, the expansion of smart workplace programs, and rising carbon reporting requirements. Prominent trends anticipated in this period include automated endpoint power scheduling, AI based energy optimization policies, centralized device power dashboards, remote pc power governance tools, and user behavior based power rules.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=28942281&type=smp&name=Personal%20Computer%20%28PC%29%20Power%20Policy%20Management%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Personal Computer (PC) Power Policy Management Market Growth Catalysts And Demand Drivers

    The increasing prevalence of remote and hybrid work models is anticipated to fuel the expansion of the PC power policy management market. These models denote flexible employment structures where employees fulfill their job duties from locations outside traditional office settings, either entirely or on a part-time basis. Their rise is attributed to advancements in digital collaboration tools, growing employee demand for flexible work arrangements, and organizations’ objectives to reduce office costs while sustaining productivity. PC power policy management supports these remote and hybrid work models by enabling IT administrators to centrally monitor, control, and optimize the power usage of distributed endpoints. This ensures energy efficiency, reduces operational costs, and maintains consistent device performance for employees working from any location. For instance, in March 2025, the U.S. Bureau of Labor Statistics, a US-based federal government agency, reported that in the first quarter of 2024, 35.5 million people worked from home or teleworked for pay, an an increase of 5.1 million compared with the previous year. These workers constituted 22.9% of all employed individuals during the period, up from 19.6% in the same quarter of the prior year. Consequently, the surge in remote and hybrid work models is driving the growth of the PC power policy management market.

    Personal Computer (PC) Power Policy Management Market Segment Landscape: Which Areas Lead Development?

    The personal computer (pc) power policy management market covered in this report is segmented –

    1) By Component: Software; Hardware; Services

    2) By Deployment Mode: On Premises; Cloud

    3) By Enterprise Size: Small And Medium Enterprises; Large Enterprises

    4) By Application: Energy Management; Security And Compliance; System Optimization; Other Applications

    5) By End User: Banking, Financial Services, And Insurance; Healthcare; Information Technology And Telecommunications; Government; Education; Manufacturing; Other End Users

    Subsegments:

    1) By Software: Energy Management Software; Power Monitoring Software; Policy Automation Software; Analytics Software; Optimization Software

    2) By Hardware: Power Controllers; Energy Meters; Smart Plugs; Sensors; Power Distribution Units

    3) By Services: Consulting Services; Implementation Services; Maintenance Services; Training Services; Support Services

    Personal Computer (PC) Power Policy Management Market Competitive Landscape: Who Leads The Industry?

    Major companies operating in the personal computer (pc) power policy management market are Microsoft Corporation, Dell Technologies Inc., Siemens AG, Lenovo Group Limited, IBM Corporation, Cisco Systems Inc., Intel Corporation, Schneider Electric SE, ABB Ltd., Hewlett Packard Enterprise, Fujitsu Limited, Toshiba Corporation, Eaton Corporation plc, ASUSTeK Computer Inc., Delta Electronics Inc., Acer Inc., Panasonic Inc., Sunbird Software Inc., CyberPower Systems Inc., Verismic Software Inc.

    View The Full Personal Computer (PC) Power Policy Management Market Report:

    https://thebusinessresearchcompany.com/report/personal-computer-pc-power-policy-management-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Personal Computer (PC) Power Policy Management Market Geographic Landscape: Which Region Leads Industry Growth?

    North America was the largest region in the pc power policy management market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the personal computer (pc) power policy management market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Paid Language Model Market Analysis Through 2030: Market Size, Growth Trends And Industry Outlook

    Paid Language Model Market Analysis Through 2030: Market Size, Growth Trends And Industry Outlook

    Backed by market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, wider supply chain intelligence, emerging startup coverage, and detailed product-level insights, The Business Research Company’s 2026 market reports are designed to offer research that is more actionable and strategically valuable than ever.

    Paid Language Model Market Revenue Outlook: What CAGR Lies Ahead Through 2030?

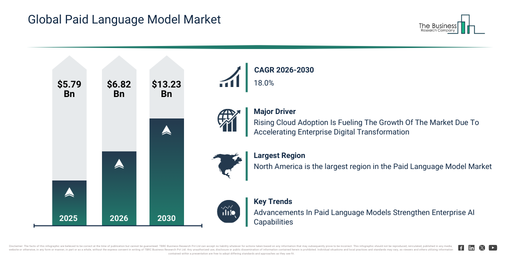
    The paid language model market size has experienced rapid expansion in recent years. Projections indicate a substantial increase, from $5.79 billion in 2025 to $6.82 billion in 2026, demonstrating a compound annual growth rate (CAGR) of 17.8%. This historical growth is primarily driven by advancements in transformer models, the proliferation of cloud AI platforms, an increase in natural language processing (NLP) applications, wider adoption of chatbots, and greater enterprise spending on AI initiatives.

    The paid language model market is projected to experience significant expansion in the coming years. This market is anticipated to reach $13.23 billion by 2030, exhibiting a compound annual growth rate (CAGR) of 18.0%. This growth during the projection period is primarily driven by the expansion of enterprise AI copilots, an increasing need for domain-specific models, the broadening of AI-powered workflows, the development of AI developer ecosystems, and more stringent enterprise AI support requirements. Key trends identified for this period encompass subscription-based LLM access, enterprise-grade language APIs, domain-tuned language models, AI pricing models based on usage, and integrated LLM developer platforms.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=87689594&type=smp&name=Paid%20Language%20Model%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Paid Language Model Market Expansion Drivers: What’s Shaping Future Growth?

    The increasing integration of cloud services is projected to drive the expansion of the paid language model market in the future. Cloud adoption refers to organizations and public bodies utilizing internet-delivered computing services, such as software applications, data storage, and processing capabilities, provided by remotely hosted servers and accessible online. This increase in cloud uptake stems from organizations accelerating their digital transformation efforts to enhance scalability, streamline operations, and manage costs more effectively. By leveraging cloud adoption, paid language models can flexibly adjust their computing and storage resources, ensuring quicker responses, high availability, and efficient costs. It also facilitates secure worldwide deployment and smooth updates, significantly improving overall performance and the user experience. As an illustration, figures from March 2025 by the Office for National Statistics, a UK government department, revealed that in 2023, 9% of UK firms had adopted artificial intelligence (AI), whereas 69% had implemented cloud-based computing systems and applications. Consequently, the expanding adoption of cloud technologies is fueling the growth within the paid language model market.

    Paid Language Model Market Segment Breakdown: Which Categories Lead On Revenue?

    The paid language model market covered in this report is segmented –

    1) By Component: Software; Platform; Application Programming Interface Services

    2) By Model Type: Generative Models; Discriminative Models; Transformer Models; Recurrent Neural Networks

    3) By Deployment Type: Cloud Based; On Premises; Hybrid

    4) By Application: Natural Language Processing; Text Generation; Sentiment Analysis; Machine Translation; Chatbots And Virtual Assistants

    5) By End User: Banking Financial Services And Insurance (BFSI); Healthcare; Retail; Education; Telecommunications

    Subsegments:

    1) By Software: Language Model Development Tools; Model Training And Fine Tuning Software; Natural Language Processing Engines; Content Generation Software; Language Analytics And Insights Software

    2) By Platform: Cloud Based Language Model Platforms; Enterprise Artificial Intelligence Platforms; Conversational Artificial Intelligence Platforms; Data Integration And Management Platforms; Model Deployment And Management Platforms

    3) By Application Programming Interface Services: Text Generation Services; Conversational Interface Services; Language Translation Services; Sentiment Analysis Services; Language Understanding Services

    Paid Language Model Market Strategic Trends: What Defines The Next Growth Phase?

    Companies operating within the paid language model market are prioritizing the development of advanced solutions, such as AI-driven business and knowledge work models, to boost productivity, automate intricate workflows, and support decisions informed by data. These AI-based business and knowledge work models utilize paid language models to automate content creation, analysis, and decision-making, which significantly enhances enterprise productivity by enabling faster insights and scalable knowledge processes. For instance, in February 2026, Anthropic, a US-based artificial intelligence company, unveiled Claude Opus 4.6, an enhanced AI model designed for coding, reasoning, and knowledge-intensive tasks. This launch occurred as growing anxieties concerning AI risks have unsettled global markets, emphasizing the crucial role of secure, transparent, and high-performance paid language models for widespread enterprise adoption across industries including finance, legal services, and customer support.

    Paid Language Model Market Competitive Analysis Of Leading Industry Participants

    Major companies operating in the paid language model market are Microsoft Corporation, Meta Platforms Inc, Huawei Technologies Co Ltd, Tencent Holdings Limited, International Business Machines Corporation, Oracle Corporation, Salesforce Inc, SAP SE, Baidu Inc, OpenAI LLC, Naver Corporation, Perplexity AI Inc, Anthropic PBC, AI21 Labs Ltd, Mistral AI SAS, Stability AI Ltd, Webkul Software Pvt. Ltd., Aleph Alpha GmbH, Cohere Inc, and DeepSeek AI.

    View The Full Paid Language Model Market Report:

    https://thebusinessresearchcompany.com/report/paid-language-model-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Paid Language Model Market Geographic Spread And Regional Opportunities

    North America was the largest region in the paid language model market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the paid language model market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model
  • Open Source Audit Market CAGR Forecast Through 2030: Key Trends Shaping Industry Expansion

    Open Source Audit Market CAGR Forecast Through 2030: Key Trends Shaping Industry Expansion

    Backed by market attractiveness analysis, total addressable market sizing, company benchmarking matrices, interactive Excel dashboards, wider supply chain intelligence, emerging startup coverage, and detailed product-level insights, The Business Research Company’s 2026 market reports are designed to offer research that is more actionable and strategically valuable than ever.

    Open-source cloud management platforms Market Size Outlook: How Quickly Will Revenue Expand Through 2030?

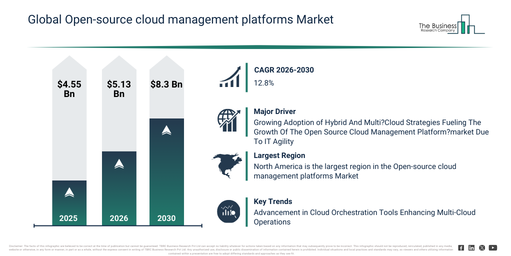
    The open-source cloud management platforms market size has experienced rapid growth in recent years. It is projected to increase from $4.55 billion in 2025 to $5.13 billion in 2026, exhibiting a compound annual growth rate (CAGR) of 12.6%. This historical expansion can be attributed to the proliferation of open source cloud stacks, the rise in hybrid cloud adoption, the demand for vendor-neutral platforms, the expansion of virtualization, and the increase in DevOps practices.

    The open-source cloud management platforms market is projected for significant expansion in the coming years. Its value is anticipated to reach $8.3 billion by 2030, demonstrating a compound annual growth rate (CAGR) of 12.8%. This projected increase is fueled by factors such as the broader adoption of multi-cloud strategies, a growing necessity for cloud cost optimization, the expansion of container orchestration, increased integration of platform engineering, and a push to avoid vendor lock-in. Key developments expected during this period include community-driven cloud orchestration platforms, multi-cloud open-source control planes, open-source tools for cost governance, cloud-native automation frameworks, and adaptable plugin-based cloud managers.

    Get A Free Sample Report With In-Depth Market Insights:

    https://thebusinessresearchcompany.com/sample_request?id=36673441&type=smp&name=Open-source%20cloud%20management%20platforms%20Market%20Report%202026&utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Open-source cloud management platforms Market Growth Factors: What’s Supporting Expansion?

    The increasing implementation of hybrid and multi-cloud strategies is projected to drive the expansion of the open source cloud management platform market moving forward. Hybrid and multi-cloud strategies involve utilizing multiple cloud environments, integrating private, public, and various cloud services into a unified IT ecosystem to enhance flexibility, optimize workloads, and reduce dependence on a single provider. The rising adoption of these strategies primarily stems from the demand for greater IT agility and operational efficiency across organizations. Open-source cloud management platforms facilitate the uptake of hybrid and multi-cloud strategies by offering vendor-neutral integration, centralized management, and cost flexibility. They enable seamless workload portability, ensure interoperability across cloud environments, and prevent vendor lock-in, thereby simplifying the management and scaling of multi-cloud operations. For instance, in march 2024, according to the Flexera, a US-based enterprise software company, approximately 89 % of organizations worldwide reported having implemented a multi-cloud strategy (up from 87 % in 2023), compared with 73 % of organizations reporting adoption of hybrid cloud environments combining public and private clouds. Thus, the growing adoption of hybrid & multi-cloud strategies is propelling the growth of the open source cloud management platform market.

    Open-source cloud management platforms Market Segment Analysis Spotlighting Growth Areas

    The open-source cloud management platforms market covered in this report is segmented –

    1) By Component: Software Platforms; Services

    2) By Deployment Model: Public Cloud; Private Cloud; Hybrid Cloud; Multi-Cloud Environment

    3) By Organization Size: Small And Medium Enterprises (SMEs); Large Enterprises

    4) By Application Type: Cloud Storage; Server Management; Database Management; Big Data And Analytics; Application Development And Testing

    5) By End-User Industry: Information Technology And Telecommunications; Banking Financial Services And Insurance; Healthcare; Government And Public Sector; Manufacturing; Retail And E Commerce

    Subsegments:

    1) By Software Platforms: Cloud Orchestration Platforms; Resource Monitoring And Management Tools; Configuration And Provisioning Software; Security And Access Management Systems; Performance And Cost Optimization Tools

    2) By Services: Implementation And Deployment Services; Consulting And Advisory Services; Managed Cloud Services; Training And Support Services; Customization And Integration Services

    Open-source cloud management platforms Market Industry Trends: What’s Reshaping Demand?

    Major companies operating in the open source cloud management platform market are prioritizing advancements in cloud orchestration tools, such as Kubernetes-based multi-cluster orchestration platforms, to boost workload mobility, centralize control, and enhance automation across hybrid and multi-cloud environments. These Kubernetes-based cloud orchestration tools are open-source technologies that allow organizations to consistently deploy, manage, scale, and monitor containerized applications across various cloud infrastructures from a single control plane. For instance, in 2023, SUSE, a Germany-based enterprise open-source software company, unveiled Rancher Prime, an advanced open-source cloud orchestration platform specifically designed for large-scale enterprise Kubernetes management. This platform delivers centralized multi-cluster management, strengthened security and policy enforcement, and automated lifecycle management of Kubernetes environments, empowering enterprises to efficiently operate complex hybrid and multi-cloud infrastructures.

    Open-source cloud management platforms Market Key Participants And Competitive Landscape

    Major companies operating in the open-source cloud management platforms market are Amazon Web Services Inc. (AWS), Google Cloud (Google LLC), Microsoft Corporation, IBM Corporation, Cisco Systems Inc., Oracle Corporation, SAP SE, Hewlett Packard Enterprise Company (HPE), ServiceNow Inc., Splunk Inc., VMware Inc., BMC Software Inc., Argo CD, Synnefo, ManageIQ, OpenNebula, VirtEngine, OpenQRM, Apache CloudStack, OpenStack, Cloudify, Mist.io (Greece), Kubernetes, Crossplane, Eucalyptus, BOSH

    View The Full Open-source cloud management platforms Market Report:

    https://thebusinessresearchcompany.com/report/open-source-cloud-management-platforms-market-report?utm_source=Blogs&utm_medium=Paid&utm_campaign=Oct_PR

    Open-source cloud management platforms Market Geographic Analysis: Where Is Demand Rising Fastest?

    North America was the largest region in the open-source cloud management platforms market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in the open-source cloud management platforms market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa.

    Reach Out To Our Team:

    The Business Research Company: https://www.thebusinessresearchcompany.com/

    Americas: +1 310-496-7795

    Asia: +44 7882 955267 & +91 8897263534

    Europe: +44 7882 955267

    Email us at: marketing@tbrc.info

    Follow us on:

    LinkedIn: https://in.linkedin.com/company/the-business-research-company

    YouTube: https://www.youtube.com/channel/UC24_fI0rV8cR5DxlCpgmyFQ

    Global Market Model: https://www.thebusinessresearchcompany.com/global-market-model