Blog

  • How Is The Bladder Cancer Drugs Market Expected To Grow Through 2024-2033

    How Is The Bladder Cancer Drugs Market Expected To Grow Through 2024-2033

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    According to The Business Research Company’s Bladder Cancer Drugs Global Market Report 2024, the bladder cancer drugs market is expected to show promising growth in the forecast period.

    The bladder cancer drugs market has witnessed significant expansion in recent years, with the market size reaching $3.65 billion in 2023 and projected to grow to $4.23 billion in 2024, representing a Compound Annual Growth Rate (CAGR) of 15.8%. Looking ahead, the market is expected to experience even more substantial growth, reaching $7.28 billion in 2028 at a CAGR of 14.5%. Key factors contributing to this growth include ongoing research and development, emerging markets, healthcare infrastructure development, strategic alliances, and collaborations.

    Factors Driving Historic Growth

    • Increasing incidence of bladder cancer
    • Advancements in drug development
    • Improved diagnostic techniques
    • Aging population
    • Regulatory approvals
    • Patient advocacy and awareness

    Trends Shaping Future Growth

    • Precision medicine
    • Immunotherapy and targeted therapies
    • Personalized medicine
    • Clinical trials and drug pipeline
    • Combination therapies
    • Biomarker-driven treatments
    • Telemedicine and remote monitoring
    • Patient-centric care

    Role of the Pharmaceutical Industry
    The burgeoning pharmaceutical industry plays a pivotal role in propelling the growth of the bladder cancer drugs market. This sector, involving the discovery, development, and production of drugs and medicines, encourages research, development, and investment in innovative treatments. The anticipated total expenditure on pharmaceuticals in the US, projected to range between $380 to $400 billion by 2025, reflects a compound annual growth rate of 0-3%. This growth is a testament to the industry’s commitment to advancing healthcare outcomes and providing a broader range of effective and targeted therapeutic options for bladder cancer patients.

    Major Players in the Bladder Cancer Drugs Market
    Several prominent companies operate in the bladder cancer drugs market, contributing to its growth and development. Some of these key players include Eli Lilly and Company, Bristol-Myers Squibb Company, Pfizer Inc., AstraZeneca PLC, Novartis International AG, Johnson & Johnson, Merck & Co. Inc., and many others. The market’s competitive landscape is characterized by a diverse range of pharmaceutical companies working towards addressing the challenges associated with bladder cancer.

    View More On The Bladder Cancer Drugs Market Report 2024 – https://www.thebusinessresearchcompany.com/report/bladder-cancer-drugs-global-market-report

    Advancements In Gene-Based Treatments For Non-Muscle-Invasive Bladder Cancer
    Rising Importance of Gene Therapy
    Gene therapy has emerged as a significant trend in the bladder cancer drug market, offering a novel approach to treating or preventing diseases by correcting underlying genetic problems. A notable example is the US Food and Drug Administration’s (FDA) approval of Adstiladrin in December 2022. This non-replicating adenoviral vector-based gene therapy is indicated for the treatment of high-risk Bacillus Calmette-Guérin (BCG)-unresponsive non-muscle-invasive bladder cancer (NMIBC) with carcinoma in situ (CIS) with or without papillary tumors.

    Merck & Co.’s Strategic Acquisition
    In August 2022, Merck & Co., a prominent US-based pharmaceutical company, acquired Seagen for a substantial deal amount of $40 billion. This strategic move expands Merck & Co.’s presence in the oncology sector, including the development and distribution of bladder cancer drugs. SeagenInc., a bio-technology company, is known for its contributions to cancer drug development, aligning with Merck & Co.’s commitment to advancing oncology treatments.

    Market Segmentation and Regional Dynamics
    Segmentation Overview
    The bladder cancer drugs market is segmented based on type, application, and distribution channel. Key segments include:

    1. Type:
      • Non-Muscle-Invasive Bladder Cancer
      • Muscle-Invasive Bladder Cancer
    2. Application:
      • Low-Grade Tumors
      • High-Grade Tumors
    3. Distribution Channel:
      • Hospital Pharmacy
      • Retail Pharmacy
      • Other Distribution Channels

    Regional Insights

    • North America emerged as the largest region in the bladder cancer drugs market in 2023.
    • The Middle East is anticipated to be the fastest-growing region during the forecast period, signaling the global nature of the bladder cancer drugs market’s expansion.

    In conclusion, the bladder cancer drugs market is poised for remarkable growth, fueled by factors such as advancements in drug development, strategic acquisitions, and the evolving landscape of gene-based treatments. As the pharmaceutical industry continues to thrive, the market is set to provide enhanced treatment options for bladder cancer patients, ultimately contributing to improved outcomes and a better quality of life.

    Request A Sample Of The Global Bladder Cancer Drugs Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=2586&type=smp

  • Biophotonics Global Market Outlook 2024-2033: Size And Growth Rate Analysis

    Biophotonics Global Market Outlook 2024-2033: Size And Growth Rate Analysis

    The Business Research Company’s global market reports provide comprehensive analysis on the various markets in 27 industries across 60 geographies.

    The biophotonics market has witnessed remarkable growth in recent years, driven by advancements in medical imaging, disease diagnosis, and life sciences research. In 2023, the market size reached an impressive $74.36 billion and is set to surge to $82.74 billion in 2024, boasting a compound annual growth rate (CAGR) of 11.3%.

    The Prodigy of Growth

    1. Short-term Projections (2023-2024):
      • Projected market size: $82.74 billion.
      • CAGR: 11.3%.
      • Key drivers: Medical imaging advancements, disease diagnosis, life sciences research, optical sensing, spectroscopy, laser and light source innovations.
    2. Long-term Forecasts (2024-2028):
      • Anticipated market size: $130.07 billion.
      • CAGR: 12.0%.
      • Emerging factors: Personalized medicine, precision agriculture, global health initiatives, wearable and mobile health devices, environmental monitoring, and safety.
      • Noteworthy trends: Miniaturization, point-of-care devices, multimodal imaging, optogenetics, machine learning, data analytics, smart imaging probes.

    Chronic Conditions Fueling The Biophotonics Market
    The escalating prevalence of chronic conditions serves as a powerful catalyst for the biophotonics market’s continued expansion. Chronic diseases, persisting for three months or more, account for a significant portion of global fatalities. Biophotonics contributes to early detection, monitoring, and treatment through non-invasive imaging and diagnostics, improving patient outcomes and curbing healthcare costs.

    1. Global Health Challenge:
      • WHO reports 41 million deaths annually due to chronic diseases.
      • Breakdown: 17.9 million cardiovascular deaths, 9.3 million cancer deaths, 4.1 million chronic respiratory deaths, 2.0 million diabetes deaths.
      • Biophotonics’ role: Driving growth by aiding in the battle against chronic conditions.

    View More On The Biophotonics Market Report 2024 – https://www.thebusinessresearchcompany.com/report/biophotonics-global-market-report

    Innovations In The Biophotonics Market
    Major players in the biophotonics market are actively engaged in pioneering advancements, especially in the medical field. Innovative products, such as advanced bronchoscopes, demonstrate the industry’s commitment to pushing boundaries.

    1. Bronchoscopes Redefined:
      • Olympus Corporation introduces H-SteriScope, a line of single-use bronchoscopes.
      • Purpose: Advanced diagnostic and therapeutic procedures.
      • Features: Disposable, premium features for precise targeting, diagnosis, and treatment.
      • Specifications: Outer diameters from 2.2 mm to 6.2 mm, working channel range of 1.2 mm to 3.2 mm.

    CellaVision’s Strategic Acquisition
    In a significant move, CellaVision, a Swedish company specializing in digital Morphology Solutions, acquired exclusive rights to the Fourier Ptychographic Microscopy patent portfolio from Clearbridge BioPhotonics for $3.28 million (SEK 28.7 million). This strategic acquisition positions CellaVision at the forefront of future technology development, particularly in automated microscopes for hematology and related fields.

    1. Acquisition Highlights:
      • CellaVision’s acquisition of Fourier Ptychographic Microscopy patent portfolio.
      • Transaction value: $3.28 million (SEK 28.7 million).
      • Potential applications: Future automated microscopes for hematology and related fields.

    Segmentation Insight

    1. Product Technology:
      • In-Vitro.
      • In-Vivo.
    2. Application:
      • See-Through Imaging.
      • Inside Imaging.
      • Spectromolecular.
      • Surface Imaging.
      • Microscopy.
      • Light Therapy.
      • Biosensors.
      • Other Applications.
    3. End Use:
      • Diagnostics.
      • Therapeutic.
      • Tests.
      • Other End Uses.

    Regional Dominance
    In 2023, North America emerged as the epicenter of the biophotonics market, establishing itself as the largest region. The region’s dominance underscores the robust growth and strategic significance of biophotonics technologies in the continent.

    In conclusion, the biophotonics market’s trajectory is on a spectacular ascent, fueled by technological innovations, strategic acquisitions, and a steadfast focus on addressing global health challenges. As the market continues to evolve, stakeholders should stay attuned to emerging trends and transformative breakthroughs shaping the radiant future of biophotonics.

    Request A Sample Of The Global Biophotonics Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3270&type=smp

  • Top 5 Insights From The X-Ray Systems Devices And Equipment Market Report 2024

    Top 5 Insights From The X-Ray Systems Devices And Equipment Market Report 2024

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    According to The Business Research Company’s X-Ray Systems Devices And Equipment Global Market Report 2024, the X-ray systems devices and equipment market is expected to show promising growth in the forecast period.

    The x-ray systems devices and equipment market has witnessed robust growth in recent years. In 2023, the market size reached $16.98 billion, experiencing a significant surge from which it is projected to grow to $18.38 billion in 2024 at a compound annual growth rate (CAGR) of 8.2%. This growth is primarily attributed to factors such as medical diagnostics, population growth, an aging population, and the emphasis on preventive and routine healthcare.

    Projected Growth and Key Drivers in the Coming Years

    1. The market is expected to continue its upward trajectory, reaching $24.44 billion in 2028, showcasing a CAGR of 7.4%.
    2. The forecasted growth is fueled by digital transformation, specialized applications, population health management, and advancements in radiation safety.
    3. Emerging trends include 3D and cone-beam CT imaging, point-of-care x-ray, AI-enhanced imaging, and remote/mobile imaging. 

    View More On The X-Ray Systems Devices And Equipment Market Report 2024 – https://www.thebusinessresearchcompany.com/report/x-ray-systems-devices-and-equipment-global-market-report

    Growth In X-Ray Systems Market Driven By Increasing Demand For Diagnostic Imaging Procedures

    1. Diagnostic Imaging Procedures and Market Demand
      • Diagnostic imaging procedures play a pivotal role in diagnosing diseases, monitoring treatment effectiveness, and planning surgeries.
      • In England alone, 40.3 million imaging procedures were reported between September 2020 and August 2021.
      • X-ray systems are crucial in identifying anomalies and aiding accurate diagnoses.
    2. Key Players in the Market
      • Major companies dominating the market include Siemens Healthcare, Carestream Health, Philips Healthcare, GE Healthcare, and others.
      • Their expertise contributes significantly to the growth and innovation within the x-ray systems market.

    NCRP’s Radiation Vital Sign And Innovations In Reducing Medical Radiation Exposure

    1. NCRP’s Initiative for Reducing Radiation Exposure
      • In response to the FDA’s initiative, the National Council on Radiation Protection and Measurements (NCRP) recommends minimizing medical radiation exposure.
      • The introduction of a radiation vital sign risk score enhances patient safety and quality of care.
    2. Innovations in Reducing Radiation Exposure
      • ControlRad, a medical technology company, observed a 57% reduction in radiation exposure to the thyroid of the first cardiologist and a 49% reduction for the secondary cardiologist using controlled procedures.
      • FDA clearance for ControlRad Select, available through Boston Scientific, facilitates retrofits on existing Siemens imaging systems.

    Canon Medical Systems Expands European Presence With Acquisition Of Nordisk Røntgen Teknik (NRT)

    1. Strategic Acquisition by Canon Medical Systems
      • In March 2022, Canon Medical Systems acquired Nordisk Røntgen Teknik (NRT), a Danish medical equipment manufacturer, strengthening its position in the European market.
      • The acquisition provides access to advanced radiographic solutions developed by NRT.

    Segmentation and Market Dynamics

    1. Market Segmentation
      • The x-ray systems market is segmented by type (portable, stationary), product type (CT, mobile x-ray, C-arm, dental x-ray, mammography, and others), image type (2D, 3D, 4D), technology (analog, digital), and application (cardiovascular, respiratory, mammography, dental, orthopedics, and others).
    2. Regional Dominance
      • Western Europe emerged as the largest region in the global x-ray devices and equipment market in 2023, showcasing the region’s significance in driving market growth.

    Conclusion: A Radiant Future for X-Ray Systems Market
    The x-ray systems devices and equipment market’s remarkable growth, driven by increasing demand for diagnostic imaging procedures, technological innovations, and strategic acquisitions, presents a promising outlook. As the market continues to evolve, embracing digital transformation, specialized applications, and advancements in radiation safety, it is poised for sustained growth and innovation in the coming years. The key players and market dynamics outlined signify a vibrant and dynamic landscape, shaping the future of diagnostic imaging technologies.

    Request A Sample Of The Global X-Ray Systems Devices And Equipment Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3810&type=smp

  • Key Trends And Drivers In The Influenza Diagnostic Market 2024

    Key Trends And Drivers In The Influenza Diagnostic Market 2024

    The Business Research Company’s market reports offer an in-depth analysis on the market’s growth potential, major drivers, key trends and more.

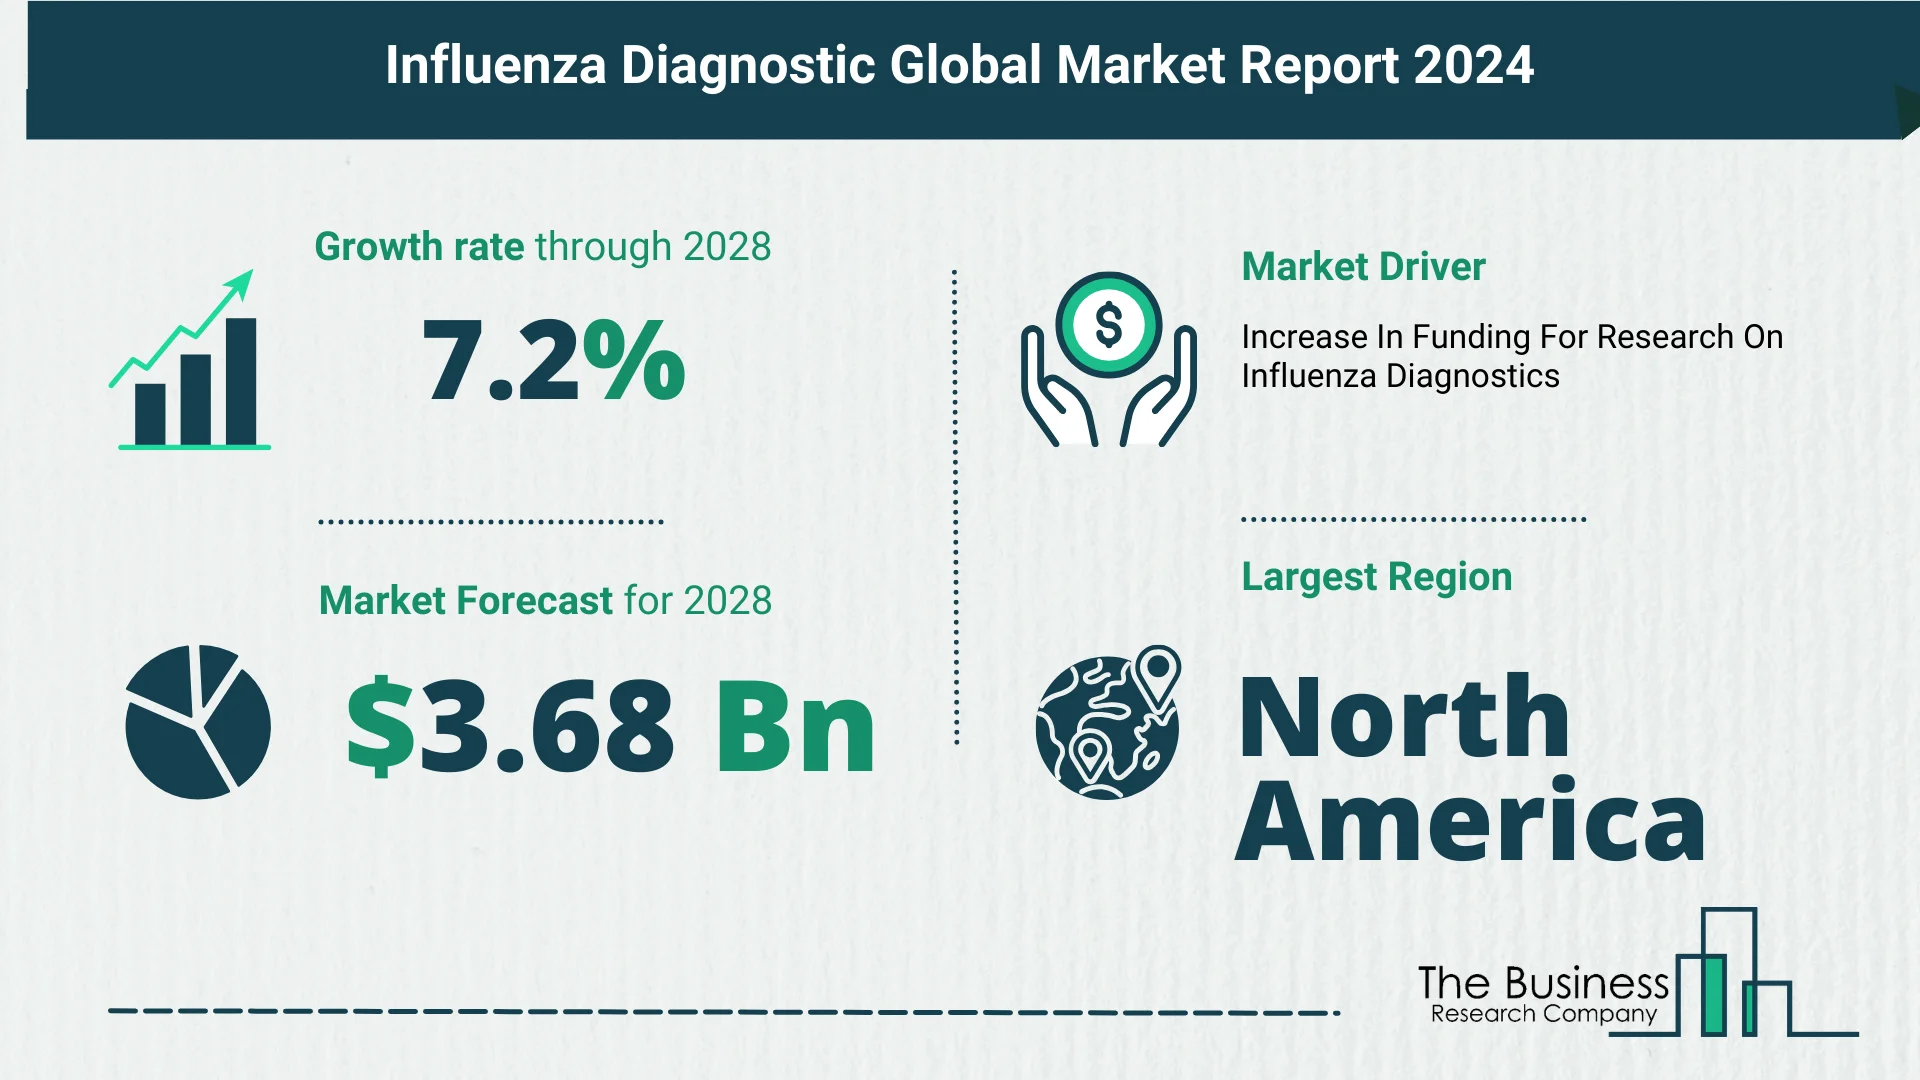
    The influenza diagnostic market is poised for substantial growth in the coming years, with an expected surge to $3.68 billion in 2028, boasting a Compound Annual Growth Rate (CAGR) of 7.2%. This growth is attributed to factors such as the prevalence of seasonal influenza, the rise of point-of-care testing, the adoption of remote and home testing, and the integration of digital health solutions.

    Rapid Diagnostic Tests: Propelling Market Growth

    Understanding Diagnostic Tests
    Diagnostic tests play a crucial role in confirming or ruling out various conditions and diseases. Rapid influenza diagnostic tests (RIDTs) are set to be a significant driver in the influenza diagnostic market. These tests can swiftly detect influenza viral antigens within 10-15 minutes, offering moderate sensitivity (50-70%). According to the Centers for Disease Control and Prevention (CDC), during September 2020 to May 2021 in the United States, 0.2% of respiratory specimens tested were positive for an influenza virus, highlighting the importance of rapid diagnostic tests.

    Key Market Players
    Major players in the influenza diagnostic market include F. Hoffmann-La Roche Ltd., Quidel Corporation, Thermo Fisher Scientific Inc., Abbott Laboratories, and Hologic Inc., among others. These companies are at the forefront of developing and providing innovative diagnostic solutions to meet the growing demand for influenza testing.

    Simultaneous Detection: A Breakthrough in Diagnosis
    Innovative Products Leading the Way
    Major companies in the influenza diagnostic market are focusing on innovation, introducing breakthrough products like the Lucira COVID-19 & Flu Home Test. This at-home test kit allows simultaneous qualitative detection of influenza A and B (commonly known as the flu) and SARS-CoV-2 (the virus causing COVID-19). Pfizer Inc. received approval for this test in February 2023, highlighting the industry’s commitment to providing convenient and comprehensive diagnostic solutions.

    Read More On The Influenza Diagnostic Market Report 2024 – https://www.thebusinessresearchcompany.com/report/influenza-diagnostic-global-market-report

    Strength in Integration
    The Lucira COVID-19 & Flu Home Test exemplifies the integration of diagnostic capabilities. With results available in approximately 30 minutes from self-collected nasal swab samples, this test showcases the industry’s dedication to offering rapid and reliable diagnostic solutions for both influenza and COVID-19.

    Thermo Fisher’s Strategic Move: Mesa Biotech Acquisition
    Strengthening Diagnostic Capabilities
    In February 2021, Thermo Fisher Scientific Inc. made a strategic move by acquiring Mesa Biotech, Inc., an infectious disease diagnostic company. This acquisition aims to enhance Thermo Fisher’s manufacturing volume, achieve cost efficiencies, and expedite the delivery of diagnostics to the market on a larger scale. Such strategic partnerships and acquisitions contribute to the overall advancement and growth of the influenza diagnostic market.

    Market Segmentation: Navigating the Landscape
    Understanding Diagnostic Tests
    The influenza diagnostic market is intricately segmented based on traditional diagnostic tests and molecular diagnostic tests. Traditional diagnostic tests include Rapid Influenza Diagnostic Tests (RIDT), Viral Culture, DFA, Serological assays, and other traditional diagnostic tests. On the other hand, molecular diagnostic tests encompass Reverse Transcription Polymerase Chain Reaction (RT-PCR), Isothermal Nucleic Acid Amplification Tests (INAAT), Loop-Mediated Isothermal Based Amplification Assays, and other molecular diagnostic tests.

    End User Perspectives
    End-user segments in the influenza diagnostic market include Hospitals and Clinical Laboratories, Diagnostic Reference Laboratories, Academic/Research Institutes, and Other End Users. Understanding these segments is crucial for comprehending the diverse applications and demands within the influenza diagnostic landscape.

    Regional Leadership: North America Takes the Lead
    Dominance in 2023
    In 2023, North America emerged as the largest region in the influenza diagnostic market. This regional dominance can be attributed to a robust healthcare infrastructure, technological advancements, and a proactive approach in adopting diagnostic solutions. As the market continues to evolve, North America remains a key player shaping the trajectory of influenza diagnostics.

    In conclusion, the influenza diagnostic market is on the cusp of significant growth, driven by the rise of rapid diagnostic tests, simultaneous detection solutions, strategic acquisitions, and a comprehensive understanding of market segmentation. With advancements in diagnostic technologies, the industry is poised to play a pivotal role in efficiently managing influenza and other respiratory illnesses in the years to come.

    Request for A Sample Of The Global Influenza Diagnostic Market Report:
    https://www.thebusinessresearchcompany.com/sample_request?id=3237&type=smp

  • 5 Key Insights On The Wearable Medical Devices Market 2024

    5 Key Insights On The Wearable Medical Devices Market 2024

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    As per The Business Research Company’s Wearable Medical Devices Global Market Report 2023, the wearable medical devices market is expected to show significant growth in the forecast period.

    The wearable medical devices market has witnessed exponential growth, with the market size projected to increase from $27.37 billion in 2023 to $33.37 billion in 2024 at an impressive Compound Annual Growth Rate (CAGR) of 21.9%. The surge in the historic period can be attributed to various factors, including the increasing focus on health and fitness tracking, chronic disease management, the aging population, and the adoption of remote patient monitoring technologies.

    Unveiling the Future: Projections and Trends
    The future of wearable medical devices looks even more promising, with the market expected to reach $71.28 billion in 2028, boasting a CAGR of 20.9%. This anticipated growth is fueled by factors such as preventive health and wellness, the expansion of emerging markets, regulatory support, reimbursement policies, and the integration of artificial intelligence (AI) and machine learning. Notable trends in the forecast period include advancements in vital sign monitoring, remote diagnosis and consultation, mental health monitoring, and the development of personalized health ecosystems.

    Chronic Disease Management: A Driving Force
    The Alarming Rise of Chronic Diseases
    The surge in mortality rates attributed to non-communicable diseases has led to a significant increase in chronic diseases and lifestyle-associated conditions, such as hypertension and diabetes. Wearable medical devices play a pivotal role in managing these conditions by offering continuous and remote patient monitoring capabilities. With wearables that can be worn throughout the day, individuals can monitor vital signs, glucose levels, and more, contributing to better disease management.

    Diabetes on the Rise
    The International Diabetes Federation reports a staggering increase in the number of adults living with diabetes, reaching 537 million in 2021. Projections indicate that this number will rise to 643 million by 2030 and a staggering 783 million by 2045. The growing awareness of chronic diseases and the need for continuous monitoring are driving individuals towards wearable medical devices, fostering market growth.

    Key Players: Powering the Wearable Revolution
    Major companies driving the wearable medical devices market include industry giants like Philips, Fitbit Inc., Garmin Ltd., Xiaomi Inc., Medtronic PLC, Samsung, Apple Inc., and Alphabet Inc. These companies are at the forefront of innovation, developing cutting-edge wearable technologies to address the increasing demand for health and wellness solutions.

    View More On The Wearable Medical Devices Market Report 2024
    https://www.thebusinessresearchcompany.com/report/wearable-medical-devices-global-market-report

    Innovation Spotlight: In-Ear Wearables
    Revolutionizing Health Monitoring
    Leading companies in the wearable medical devices market are focusing on innovation, with a particular emphasis on in-ear wearables. These small electronic devices worn in the ear track multiple health metrics simultaneously, providing real-time feedback to users. For instance, STAT Health launched an in-ear wearable blood flow monitor, STAT, equipped with an optical sensor to measure blood flow and automatically detect changes in heart rate, blood pressure trends, and blood flow to the head. This device, compatible with over 90% of ear-fitting devices, showcases the potential to forecast fainting episodes minutes before they occur, enhancing user safety.

    Practical Advantages of In-Ear Wearables
    In-ear wearables offer practical advantages, reducing the risk of users forgetting to reinstall the device. These wearables can be worn during sleep and showering, ensuring continuous monitoring without interruption. This innovation addresses common user concerns and enhances the overall user experience.

    Market Segmentation: Understanding the Landscape
    The wearable medical devices market is segmented based on device type, product type, distribution channels, and applications. Key segments include diagnostic and therapeutic devices, diverse product types like watches, wristbands, clothing, and ear wear, distribution channels spanning pharmacies, online platforms, and hypermarkets, and applications such as sports and fitness, remote patient monitoring, home healthcare, and ear wear.

    Regional Dominance: North America Takes the Lead
    North America emerged as the largest region in the wearable medical devices market in 2023. The region’s leadership is attributed to its robust healthcare infrastructure, technological advancements, and the widespread adoption of wearable technologies. As the market continues to evolve, North America remains a significant player in shaping the trajectory of wearable medical devices.

    In conclusion, the wearable medical devices market is poised for remarkable growth, driven by advancements in technology, increased awareness of chronic diseases, and a shift towards preventive healthcare. Innovations such as in-ear wearables exemplify the industry’s commitment to enhancing user experience and delivering cutting-edge solutions. With substantial projections and ongoing trends, the wearable revolution in healthcare is set to transform the way individuals monitor and manage their health.

    Request A Sample Of The Global Wearable Medical Devices Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3976&type=smp

  • Weight Monitoring And Body Temperature Monitoring Devices And Equipment Global Market Outlook 2024-2033: Size And Growth Rate Analysis

    Weight Monitoring And Body Temperature Monitoring Devices And Equipment Global Market Outlook 2024-2033: Size And Growth Rate Analysis

    The Business Research Company’s global market reports provide comprehensive analysis on the various markets in 27 industries across 60 geographies.

    The weight monitoring and body temperature monitoring devices and equipment market has witnessed a significant surge in recent years. The market size is set to escalate from $9.32 billion in 2023 to $10.57 billion in 2024, boasting a compound annual growth rate (CAGR) of 13.5%. Looking ahead, the market is anticipated to reach $16.97 billion by 2028, exhibiting a CAGR of 12.5%. The roots of this growth can be traced to various factors, both historical and forecasted.

    • Historic Growth Factors: Maternal and neonatal health awareness, enhanced healthcare access, high-risk pregnancies, telemedicine, and remote monitoring played pivotal roles in the historical market growth.
    • Forecasted Growth Factors: Emerging markets, personalized medicine, increased premature birth rates, and the adoption of value-based healthcare are poised to drive future growth.

    Home Healthcare: A Catalyst for Market Expansion
    The burgeoning demand for home healthcare services is expected to act as a key driver for the weight monitoring and body temperature monitoring devices and equipment market. Home healthcare, characterized by medical care provided to patients recovering from illnesses or managing chronic conditions, utilizes these monitoring devices for efficient health tracking.

    • Home Health Workforce Surge: According to the Rockefeller Institute of Government, the US is projected to witness a 25% increase in home health and personal care aide positions, reaching 924,000 between 2021 and 2031. This surge underlines the rising demand for home healthcare, fostering the growth of monitoring devices and equipment.

    Industry Giants: Market Players and Key Competitors
    Major players contributing to the dynamic landscape of weight and body temperature monitoring devices and equipment include industry leaders such as Philips Healthcare, Medtronic PLC, GE HealthCare Technologies Inc., Abbott Laboratories, 3M, Nihon Kohden, and more. The competitive market scenario is marked by the presence of globally recognized names, each striving to carve its niche.

    • Key Market Players: Philips Healthcare, Medtronic PLC, GE HealthCare Technologies Inc., Abbott Laboratories, 3M, Nihon Kohden, Omron Healthcare, Siemens Healthcare, Honeywell International Inc., Infinium Medical Inc., and others.

    View More On The Weight Monitoring And Body Temperature Monitoring Devices And Equipment Market Report 2024 –
    https://www.thebusinessresearchcompany.com/report/weight-monitoring-and-body-temperature-monitoring-devices-and-equipment-global-market-report

    Innovations Driving Market Advancements
    Innovation remains at the forefront of the weight and body temperature monitoring devices and equipment market. Industry leaders are investing in cutting-edge technologies, with a particular focus on temperature monitoring solutions. These solutions aim to provide reliable and advanced services to consumers, contributing to the market’s evolution.

    • Exemplary Technological Advancement: Konica Minolta Inc. introduced the FORXAI Temperature Monitoring App (TMA) in December 2021. This unique system utilizes an edge thermal camera to continuously capture temperature data. TMA allows users to set thresholds based on actual data, defining normal temperature using historical temperature data of the target object.

    Market Segmentation: Navigating the Diverse Landscape
    The weight monitoring and body temperature monitoring devices and equipment market is intricately segmented to address the diverse needs of end-users. Key segments include types of devices, temperature monitoring devices, and end-users.

    • Device Types: Weight Monitoring Devices, Temperature Monitoring Devices.
    • Temperature Monitoring Devices: Table Top Temperature Monitoring Devices, Hand Held Temperature Monitoring Devices, Wearable Continuous Monitoring Thermometers, Temperature Monitoring Sensors & Smart Temperature Patches.
    • End Users: Hospitals & Clinics, Home Settings, Ambulatory Surgical Centers.

    Regional Dynamics: Asia-Pacific Taking the Lead
    In 2023, Asia-Pacific emerged as the largest region in the global weight monitoring and body temperature monitoring devices and equipment market. The region’s dominance reflects the growing significance of healthcare infrastructure and technological advancements, making it a key player in the market’s global landscape.

    In conclusion, the weight and body temperature monitoring devices and equipment market’s impressive growth trajectory is fueled by a confluence of factors, including the rising demand for home healthcare, technological innovations, and strategic market segmentation. As major players continue to push the boundaries of innovation, the industry is poised for sustained expansion and evolution in the coming years.

    Request A Sample Of The Global Weight Monitoring And Body Temperature Monitoring Devices And Equipment Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=2474&type=smp

  • Global In Vitro Diagnostics Market Analysis: Estimated Market Size And Growth Rate

    Global In Vitro Diagnostics Market Analysis: Estimated Market Size And Growth Rate

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    The in-vitro diagnostics market has witnessed remarkable growth in recent years, with a robust trajectory expected to continue. From a size of $108.07 billion in 2023, the market is projected to reach $119.99 billion in 2024, boasting a Compound Annual Growth Rate (CAGR) of 11.0%. This expansion can be attributed to various factors such as the development of automated analyzers, the rise of molecular diagnostics, an aging population, disease outbreaks, evolving healthcare regulations, and the advent of personalized medicine.

    Current Market Scenario

    • The in-vitro diagnostics market is set to grow to $176.02 billion in 2028, maintaining a CAGR of 10.1%.
    • The forecast period will witness contributions from precision medicine, point-of-care testing, digital health, data analytics, and pandemic preparedness.
    • Key trends in the forecast period include technological advancements, digital health integration, personalized diagnostics, home testing kits, and molecular diagnostics.

    Surging Demand For Self-Administered Tests Reshapes The Market Landscape

    • The rising popularity of self-administered test kits is a key driver of market growth.
    • Self-administered test kits offer accessibility and convenience, enabling individuals to perform diagnostic tests at home.
    • Notably, the use of at-home COVID-19 tests increased significantly during the Delta to Omicron transition, indicating a growing trend in self-administered testing.
    • Major companies in this space include Siemens Healthineers, F. Hoffmann-La Roche AG, Danaher Corporation, Abbott Laboratories Inc., and more.

    View More On The In Vitro Diagnostics Market Report 2024 –
    https://www.thebusinessresearchcompany.com/report/in-vitro-diagnostics-global-market-report

    Incorporating Artificial Intelligence (AI) For Enhanced Precision And Efficiency

    • Major companies are integrating artificial intelligence (AI) into their products to improve testing accuracy and efficiency.
    • LooK SPOT, an AI-powered in vitro diagnostic test for COVID-19, exemplifies this trend.
    • Developed by Yas Pharmaceutical Co., Pure Health Company, and Laipac Technology Inc., LooK SPOT uses AI algorithms and machine learning to enhance testing accuracy.
    • The LooK SPOT test, which attaches to a smartphone, reduces the risk of human error and offers improved sensitivity in low-positive cases.

    Market Segmentation

    • The in-vitro diagnostics market is segmented based on various criteria:
      • Type: Point-of-Care Diagnostics Devices And Equipment, Immunochemistry Diagnostic Devices And Equipment, Clinical Chemistry Diagnostics Devices And Equipment, Molecular Diagnostics Devices And Equipment, Microbiology Diagnostic Devices And Equipment, Hemostasis Diagnostic Devices And Equipment, Hematology Diagnostic Devices And Equipment, Immunohematology Diagnostic Devices And Equipment
      • End User: Hospitals And Clinics, Diagnostic Laboratories, Other End Users
      • Type of Expenditure: Public, Private
      • Product: Instruments/Equipment, Disposables

    Geographical Significance: North America Leading the Charge

    • North America emerged as the largest region in the global in-vitro diagnostics market in 2023.
    • The region’s prominence underscores the advancements and investments in healthcare infrastructure and innovation.

    Conclusion
    The in-vitro diagnostics market is witnessing a transformative phase, driven by technological innovations, the surge in self-administered tests, and the integration of artificial intelligence. The industry’s projected growth signifies a robust future, with the market becoming increasingly dynamic and adaptable. As we move forward, it will be essential for stakeholders to navigate these changes strategically, embracing emerging trends and technologies to contribute to the evolution of diagnostic practices and healthcare at large.

    Request A Sample Of The Global In Vitro Diagnostics Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=13065&type=smp

  • Future Growth Forecast For The Anti-Parkinson Drugs Global Market 2024-2033

    Future Growth Forecast For The Anti-Parkinson Drugs Global Market 2024-2033

    The Business Research Company’s global market reports provide comprehensive analysis on the various markets in 27 industries across 60 geographies.

     The anti-parkinson drugs market has witnessed significant growth, reaching $9.73 billion in 2023 and projected to climb to $10.43 billion in 2024, reflecting a compound annual growth rate (CAGR) of 7.2%. Factors contributing to this growth include an aging population, increasing disease prevalence, advancements in healthcare infrastructure, and ongoing research initiatives.

    Anticipated Growth and Key Drivers in the Coming Years

    1. The market is poised for robust growth, reaching $13.36 billion by 2028, with a CAGR of 6.4%.
    2. Key drivers include growing awareness, biotechnological advancements, and the expansion of emerging markets.
    3. Major trends in the forecast period encompass investments in R&D, personalized medicine, disease-modifying therapies, drug repurposing, telemedicine and remote monitoring, biosimilars, and research collaborations.

    Increasing Geriatric Population In The Anti-Parkinson Drugs Market

    1. Geriatric Population as a Driving Factor
      • The rising geriatric population and the increasing incidence of Parkinson’s disease (PD) are anticipated to propel the demand for anti-parkinson drugs.
      • Globally, by 2030, 1 in 6 individuals will be 60 or older, and by 2050, this number is expected to double to 2.1 billion.
    2. Regional Perspective: UK’s Aging Population
      • In the UK, the elderly population is projected to account for 24% of the total population (17.4 million people) by 2043.
      • This demographic shift underscores the significance of anti-parkinson drugs in addressing age-related health challenges.
    3. Impact on Market Growth
      • The increasing geriatric population is a pivotal factor driving the growth of the anti-parkinson drugs market.

    View More On The Anti-Parkinson Drugs Market Report 2024 – https://www.thebusinessresearchcompany.com/report/anti-parkinson-drugs-global-market-report

    Innovative Advancements In The Anti-Parkinson Drugs Market

    1. Product Innovation for Improved Patient Services
      • Major companies are innovating products like Safinamide to enhance the quality of life for Parkinson’s patients.
      • Optimus Pharma launched Safinamide in April 2021, approved by the Drug Controller General of India, providing an affordable and accessible treatment option.
    2. AbbVie’s Strategic Acquisition
      • In October 2023, AbbVie Inc. acquired Mitokinin for $110 million, aiming to bolster its neuroscience pipeline and offer new treatment options for Parkinson patients.
      • Mitokinin specializes in providing treatments for Parkinson’s disease.

    Segmentation and Market Dynamics

    1. Market Segmentation
      • The anti-parkinson drugs market is segmented by drug class (levodopa/carbidopa, dopamine receptor agonists, MAO-B inhibitors, COMT inhibitors, anticholinergics, and others), route of administration (oral, injection, transdermal), and distribution channel (hospital pharmacies, retailer pharmacies, online pharmacies).
    2. Regional Dominance
      • North America emerged as the largest region in the anti-parkinson drugs market in 2023, highlighting the region’s pivotal role.
      • The Middle East is expected to be the fastest-growing region during the forecast period, indicating expanding opportunities.

    Conclusion: A Promising Future for Anti-Parkinson Drugs As the anti-parkinson drugs market continues to evolve, driven by the increasing aging population and innovative advancements, the future holds promising opportunities. With a focus on research collaborations, personalized medicine, and technological innovations, stakeholders in the industry are well-positioned for sustained growth. The strategic acquisitions and product innovations outlined underscore the dynamic landscape of the market, shaping the future of Parkinson’s disease management.

    Request A Sample Of The Global Anti-Parkinson Drugs Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3462&type=smp

  • Global Anti-Thyroid Drugs Market Analysis 2024: Size, Share, And Key Trends

    Global Anti-Thyroid Drugs Market Analysis 2024: Size, Share, And Key Trends

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    As per The Business Research Company’s Anti-Thyroid Drugs Global Market Report 2023, the anti-thyroid drugs market is expected to show significant growth in the forecast period.

    The anti-thyroid drugs market has demonstrated steady growth in recent years, showing resilience and adaptability within the healthcare landscape. With a size of $2.4 billion in 2023, the market is projected to reach $2.46 billion in 2024, presenting a Compound Annual Growth Rate (CAGR) of 2.5%. Key factors influencing this growth in the historic period include the prevalence of thyroid disorders, advancements in drug development, and improvements in healthcare infrastructure.

    Current Market Scenario

    • Expected CAGR of 2.8% propelling the market to $2.75 billion by 2028.
    • Factors contributing to growth in the forecast period include patient awareness and education, healthcare expenditure, patient demographics, and global economic conditions.
    • Major trends include alternatives to thyroid surgery and radioactive iodine, patient-centric care, and the integration of telemedicine and remote monitoring.

    Graves Disease And Its Influence On The Anti-Thyroid Drug Market

    • Graves’ disease, a leading cause of hyperthyroidism, is on the rise globally.
    • According to the National Library of Medicine, it is the most common cause of hyperthyroidism in developed countries.
    • Incidence is higher between ages 30 and 60, with women being 5–10 times more likely than men.
    • Genetic predisposition contributes to 79% of the risk, while environmental factors account for 21%.
    • The increasing incidence of Graves’ disease directly correlates to the growing demand for anti-thyroid drugs, driving market expansion.
    • Major companies contributing to the market include Mylan N.V., Abbott Laboratories, GlaxoSmithKline PLC, and others.

    View More On The Anti-Thyroid Drugs Market Report 2024 – https://www.thebusinessresearchcompany.com/report/anti-thyroid-drugs-global-market-report

    Innovations In The Anti-Thyroid Drug Market

    • Companies are focused on innovation to enhance products and services.
    • Levothyroxine Sodium Injection, an injectable anti-thyroid drug for the treatment of myxedema coma, demonstrates this commitment.
    • In December 2022, Hikma Pharmaceuticals PLC launched Levothyroxine Sodium Injection, providing a more convenient and efficient way to administer the medication in hospitals.
    • This innovation showcases the industry’s commitment to delivering reliable solutions to patients.

    Market Segmentation

    • The anti-thyroid drugs market is segmented based on various criteria:
      • Drug Type: Thionamides (Inhibition of hormone synthesis), Iodides (Inhibition of hormone release)
      • Route of Administration: Oral, Intravenous, Other Route of Administration
      • Distribution Channel: Wholesaler/Distributors, Retail Chain, Online Distribution, Other Distribution Channels

    Regional Dynamics: North America Leading, Middle East Emerging

    • North America emerged as the largest region in the market in 2023.
    • The Middle East is expected to be the fastest-growing region during the forecast period, indicating the global nature of the market.

    Conclusion
    The anti-thyroid drugs market’s steady growth is underpinned by factors such as the rising incidence of Graves’ disease, advancements in drug innovation, and a commitment to patient-centric care. As the market progresses, stakeholders need to navigate the changing landscape, embracing innovative treatments and technology integration. The emphasis on patient awareness, education, and the dynamic trends shaping the industry will pave the way for continued growth, ensuring that anti-thyroid drugs play a crucial role in managing thyroid disorders globally.

    Request A Sample Of The Global Anti-Thyroid Drugs Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3401&type=smp

  • How Is The Antiglaucoma Drugs Market Expected To Grow Through 2024-2033

    How Is The Antiglaucoma Drugs Market Expected To Grow Through 2024-2033

    The Business Research Company’s global market reports are now updated with the latest market sizing information for the year 2024 and forecasted to 2033

    According to The Business Research Company’s Antiglaucoma Drugs Global Market Report 2024, the antiglaucoma drugs market is expected to show promising growth in the forecast period.

    The antiglaucoma drugs market has witnessed robust growth in recent years, with the market size projected to increase from $15.07 billion in 2023 to $16.27 billion in 2024, boasting a Compound Annual Growth Rate (CAGR) of 7.9%. This growth is attributed to factors such as the aging population, increasing awareness, growing healthcare expenditure, and regulatory approvals. Looking ahead, the market is expected to continue its upward trajectory, reaching $21.9 billion in 2028, with a CAGR of 7.7%. Key drivers in the forecast period include emerging markets, reimbursement policies, and disease awareness campaigns.

    Government Initiatives Driving Awareness

    Vision Health Initiatives
    Governments worldwide are recognizing the significance of addressing eye disorders, especially with the increasing incidence of glaucoma associated with aging. Initiatives such as the Vision Health initiative by the Centers for Disease Control and Prevention (CDC) in the USA are aimed at preventing eye disorders, including glaucoma, and improving overall eye health. Moreover, in July 2021, the United Nations passed a resolution emphasizing increased efforts to include eye care services in universal health coverage, highlighting the negative effects of vision loss caused by conditions like glaucoma. These initiatives play a pivotal role in creating awareness among the population, thereby driving the demand for antiglaucoma drugs.

    Innovations Fueling Antiglaucoma Drug Market Growth

    OMLONTI: A Breakthrough Product
    Major companies in the antiglaucoma drugs market, including Santen Pharmaceutical Co. Ltd. and UBE Corporation, are focusing on innovation to bring new and effective products to market. OMLONTI (Omidenepag Isopropyl Ophthalmic Solution) is a notable example, approved by the Food and Drug Administration (FDA) in September 2022. This eye drop, designed for patients with primary open-angle glaucoma or ocular hypertension, boasts a selective prostaglandin EP2 receptor agonist, setting it apart in terms of pharmacological action. Such innovations contribute significantly to the market’s growth, providing reliable and advanced treatment options for glaucoma patients.

    View More On The Antiglaucoma Drugs Market Report 2024 – https://www.thebusinessresearchcompany.com/report/antiglaucoma-drugs-global-market-report

    Key Market Players
    Major companies contributing to the antiglaucoma drugs market include Aerie Pharmaceuticals Inc., Allergan Inc., Novartis AG, Pfizer Inc., Bayer AG, and many others. These industry giants play a crucial role in shaping the landscape through research, development, and the introduction of cutting-edge products.

    Market Segmentation: Understanding the Landscape

    Comprehensive Segmentation
    The antiglaucoma drugs market is intricately segmented based on type, product type, and disease condition type. Types include Hospital Prescription drugs and Over-the-counter drugs, providing options for both clinical and self-administered treatments. Product types range from Alpha Agonist to Prostaglandin Analogs, showcasing the diversity of treatment options available. Disease condition types encompass Open-Angle Glaucoma, Angle-Closure Glaucoma, Normal-Tension Glaucoma, Congenital Glaucoma, and Other Types of Glaucoma, offering specialized solutions for different conditions.

    Regional Dynamics: Leading and Emerging Markets

    North America Takes the Lead
    In 2023, North America emerged as the largest region in the antiglaucoma drugs market. The region’s leadership is attributed to a robust healthcare infrastructure and a proactive approach to adopting advanced healthcare solutions. However, the Middle East is expected to be the fastest-growing region in the antiglaucoma drugs market during the forecast period. Emerging markets in this region, coupled with increasing healthcare awareness, contribute to the region’s anticipated growth.

    In conclusion, the antiglaucoma drugs market’s strong growth trajectory is fueled by a combination of factors, including government initiatives, innovative product development, and comprehensive market segmentation. With ongoing technological advancements, telemedicine integration, and a focus on sustainability, the antiglaucoma drugs market is set to play a pivotal role in addressing the eye health needs of an aging population.

    Request A Sample Of The Global Antiglaucoma Drugs Market Report 2024:
    https://www.thebusinessresearchcompany.com/sample_request?id=3803&type=smp